Where It All Began
Henry Sherwin and Edward Williams started small, with a single storefront in Cleveland’s business district. Their early years were defined by two critical factors: the industrial revolution’s demand for durable coatings and the lack of a reliable domestic paint supply. Sherwin, a former pharmacist, brought chemical expertise; Williams, a painter, understood the practical needs of tradespeople. Their first products—oil-based paints and varnishes—were sold in small batches, but the business grew steadily as word spread about their quality. By 1875, they’d expanded to a second location, and by the turn of the century, Sherwin-Williams had become a regional distributor, supplying everything from barn paint to architectural finishes. The company’s survival through the Great Depression was no accident. While competitors folded under financial strain, Sherwin-Williams pivoted to selling directly to contractors, bypassing middlemen and locking in steady demand. This early focus on B2B relationships would later become a cornerstone of its financial strategy. The 1940s and 1950s saw further diversification: the introduction of latex paints, the acquisition of smaller manufacturers, and the establishment of a nationwide distribution network. By the time Sherwin-Williams went public in 1958, its sherwin williams revenue net worth had ballooned to a point where it could afford to think globally—not just as a paint seller, but as a materials conglomerate.The Early Signs
Two decisions in the 1960s revealed the company’s long-term ambition. First, it acquired the sherwin williams revenue net worth-boosting Minwax brand, expanding into wood finishes and giving it a foothold in the growing do-it-yourself market. Second, it began investing heavily in research and development, particularly in low-VOC (volatile organic compound) paints—a move that would pay dividends decades later as environmental regulations tightened. These weren’t just product upgrades; they were strategic bets on shifting consumer priorities. The company also recognized that its true strength lay in its distribution infrastructure. While competitors relied on third-party retailers, Sherwin-Williams built its own warehouses and logistics hubs, ensuring faster turnaround and tighter control over pricing. The 1970s cemented its dominance when it launched the sherwin williams revenue net worth-scaling Sherwin-Williams Color Centers, physical showrooms where customers could sample thousands of paint colors. This wasn’t just a retail innovation—it was a data play. The company began collecting consumer preferences, which it later used to refine its product lines. By the end of the decade, Sherwin-Williams had become the default choice for professional painters, not just because of its quality, but because of its reliability. The stage was set for the next act: a full-blown corporate expansion that would turn it into a global force.The Turning Point
The 1980s were the decade Sherwin-Williams stopped playing by the old rules. The company’s leadership, under CEO John G. Gamble, executed a three-pronged strategy: aggressive acquisitions, a shift toward professional customers, and the creation of a vertically integrated supply chain. The most critical acquisition was sherwin williams revenue net worth-accelerating Dutch Boy Paints in 1987, which gave the company instant access to a broader consumer base and a stronger retail presence. But the real game-changer was the decision to prioritize contractors over homeowners. While competitors chased the DIY market, Sherwin-Williams doubled down on trade sales, which proved far more recession-resistant. The company also began treating its distribution centers as strategic assets rather than cost centers. By the late 1980s, Sherwin-Williams had built a network of 400-plus locations, each stocked with inventory tailored to regional demand. This wasn’t just logistics—it was a financial moat. Competitors couldn’t replicate the scale overnight, and Sherwin-Williams used its size to negotiate better terms with suppliers, further compressing margins for rivals. The result? A sherwin williams revenue net worth that grew at a compounded rate of nearly 10% annually through the 1990s, even as the broader economy faced volatility."We didn’t just sell paint. We sold peace of mind to contractors who knew if they ran out, we’d have it tomorrow." — John G. Gamble, Sherwin-Williams CEO (1980s)
The Build-Up, Year by Year
| Period | Key Developments |
|---|---|
| 1990–1995 |
|
| 1996–2000 |
|
| 2001–2007 |
|
| 2008–2015 |
|
Lessons From the Journey
- Vertical integration is a competitive weapon. Sherwin-Williams didn’t just sell products—it controlled the entire pipeline, from raw materials to the customer’s door. This reduced reliance on third parties and insulated it from supply chain disruptions.
- Trade customers are the bedrock of stability. While consumer demand fluctuates with economic cycles, professional contractors provide steady, predictable revenue—especially during downturns.
- Innovation doesn’t always mean new products. The ColorSnap tool wasn’t just a gimmick; it was a data-gathering machine that refined Sherwin-Williams’ understanding of consumer trends.
- Acquisitions must align with core strengths. Buying Dutch Boy made sense; acquiring a random consumer brand would not have moved the needle on sherwin williams revenue net worth.
- Regulatory foresight pays off. Early investments in low-VOC paints positioned Sherwin-Williams as a leader when environmental laws tightened, rather than a laggard playing catch-up.
- Brand loyalty is earned, not bought. The company’s focus on quality and service—rather than aggressive discounting—created a customer base that sticks through economic ups and downs.
Where Things Stand Today
Sherwin-Williams is now a different beast from the Cleveland paint shop of 1866. Its sherwin williams revenue net worth in recent years has consistently topped $20 billion annually, with net income figures frequently exceeding $1.5 billion. The company operates in three main segments: U.S. Paint & Coatings, U.S. Consumer Brands, and Global Brands & Emerging Markets. While the U.S. segment remains the largest contributor, international expansion—particularly in Asia and Latin America—has become a priority. The pandemic years tested its resilience, but Sherwin-Williams thrived where others faltered, thanks to strong demand for home improvement products and its ability to pivot quickly to digital sales tools. What’s next? The company is betting heavily on sustainability—not just as a marketing angle, but as a long-term revenue driver. Its EverPaint line, designed for durability and low maintenance, aligns with growing consumer interest in eco-friendly products. Additionally, Sherwin-Williams is investing in automation and AI to optimize its supply chain, further tightening its grip on costs and margins. The question for investors and analysts isn’t whether the company will keep growing, but whether it can replicate its past success in an era where consumers are more price-sensitive and supply chains are more complex.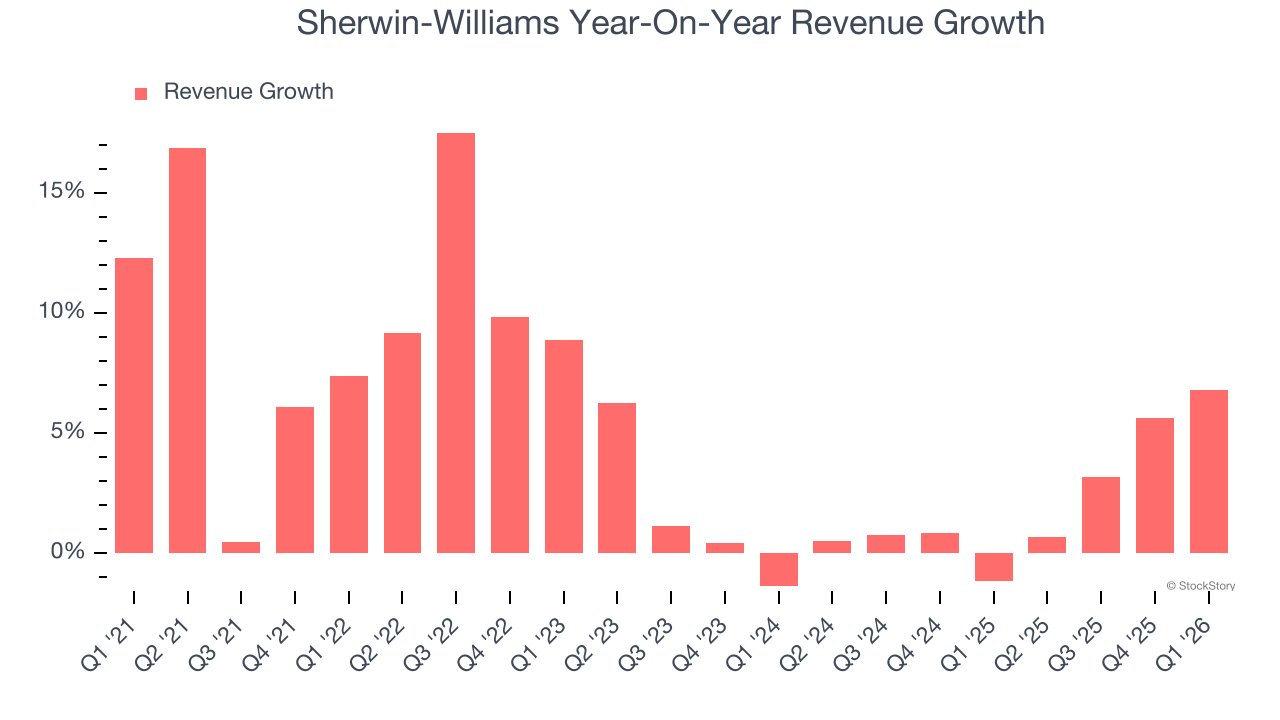
Conclusion
Sherwin-Williams’ story is one of adaptation. It didn’t become a financial powerhouse by clinging to tradition; it reinvented itself at every turn. From its early days as a regional distributor to its current status as a global coatings giant, the company’s sherwin williams revenue net worth reflects a relentless focus on controlling its destiny. The lessons are clear: dominance in an industry isn’t about luck—it’s about seeing opportunities before they’re obvious, investing in infrastructure when others cut costs, and never losing sight of the customer, whether they’re a contractor or a homeowner. The next chapter may involve new challenges—climate change, shifting consumer habits, or geopolitical disruptions—but Sherwin-Williams has always met challenges head-on. Its ability to turn raw materials into financial returns isn’t just a testament to its business acumen; it’s a blueprint for how to build an empire that outlasts its founders’ wildest dreams.Comprehensive FAQs
Q: How does Sherwin-Williams compare to its biggest rival, PPG Industries?
Sherwin-Williams and PPG Industries are both leaders in coatings, but their business models differ significantly. Sherwin-Williams generates sherwin williams revenue net worth primarily through retail and trade sales in North America, with a strong focus on consumer brands like Dutch Boy and Pratt & Lambert. PPG, on the other hand, is more diversified globally, with heavy exposure to industrial and automotive coatings. While PPG’s revenue is slightly higher (around $15–17 billion annually), Sherwin-Williams’ net income margins are typically stronger due to its retail dominance and lower exposure to cyclical industrial markets.
Q: What percentage of Sherwin-Williams’ revenue comes from trade (professional) customers vs. consumers?
Trade sales—primarily to contractors, builders, and commercial clients—account for roughly 60–65% of Sherwin-Williams’ sherwin williams revenue net worth. The remaining 35–40% comes from consumer channels, including its retail stores, e-commerce, and home improvement centers. This trade-heavy model has been a key driver of stability, as professional customers are less sensitive to short-term economic fluctuations than individual homeowners.
Q: How has Sherwin-Williams’ stock performance tracked with its financial growth?
Sherwin-Williams has been a consistent performer in the stock market, with its shares appreciating significantly over the long term. Since its IPO in 1958, the company’s stock has delivered returns well above the S&P 500, particularly during periods of economic expansion. The sherwin williams revenue net worth growth has translated into steady dividend increases, making it a favorite among income investors. However, like all stocks, it’s not immune to downturns—shares dipped during the 2008 crisis and again in early 2020, though the company’s fundamentals remained strong in both cases.
Q: What are the biggest risks to Sherwin-Williams’ financial future?
While Sherwin-Williams’ sherwin williams revenue net worth growth has been impressive, risks remain. Supply chain disruptions (e.g., raw material shortages) could squeeze margins, though the company’s vertical integration helps mitigate this. Regulatory pressures, particularly around VOC emissions and sustainability, may require costly R&D investments. Competition from private-label brands and discount retailers also poses a threat, though Sherwin-Williams’ strong brand equity has so far insulated it. Finally, geopolitical instability—especially in key markets like China—could impact its international expansion plans.
Q: How does Sherwin-Williams’ pricing power work in practice?
Sherwin-Williams’ pricing power stems from its market dominance in both retail and trade channels. As the largest paint supplier in North America, it controls a significant portion of shelf space and contractor demand, allowing it to set prices with less sensitivity to competitor actions. For example, when raw material costs spike (like during the 2021 titanium dioxide shortage), Sherwin-Williams can absorb some of the cost while still maintaining healthy margins—unlike smaller players forced to pass increases directly to customers. This pricing discipline is a key reason its sherwin williams revenue net worth remains resilient even during inflationary periods.
Q: Are there any emerging markets where Sherwin-Williams is aggressively expanding?
Yes. While North America remains its core, Sherwin-Williams is focusing on Asia-Pacific and Latin America for future sherwin williams revenue net worth growth. In China, it has partnered with local distributors to tap into the booming home renovation market. In Brazil and Mexico, it’s expanding its retail footprint to serve growing middle-class consumers. The company also sees potential in India and Southeast Asia, where urbanization is driving demand for coatings. However, these markets come with challenges, including regulatory hurdles and local competition, so growth is measured and strategic.
