Breaking Down the Numbers
Rolex’s financial opacity isn’t accidental. As a privately held entity, it doesn’t disclose annual revenues or profit margins, leaving analysts to piece together its net worth in 2022 through proxies: resale market trends, dealer reports, and comparisons to publicly traded peers like Richemont (which owns Cartier and Jaeger-LeCoultre). The most cited benchmark comes from secondary market data, where Rolex watches routinely fetch 200–500% above retail—a signal that the brand’s true valuation extends far beyond its production costs. Industry estimates suggest Rolex’s annual revenue in 2022 hovered around CHF 10–12 billion (approximately $11–13 billion), with net profits likely in the CHF 3–4 billion range, though these figures remain speculative. The brand’s valuation in 2022 was further inflated by its role as a safe-haven asset. During economic uncertainty, Rolex watches—particularly the Submariner, Daytona, and GMT-Master II—became status symbols with speculative appeal. Auction houses like Phillips and Sotheby’s reported record sales for vintage Rolexes, with a 1950s Reference 6238 Submariner selling for over $1.2 million in 2022, a figure that underscored how collector demand and scarcity could distort traditional valuation models. Even new models, like the Rolex Day-Date 41, saw resale prices climb 40–60% above MSRP within months of release, proving that Rolex’s financial strength wasn’t just about volume but perceived exclusivity.The Verified Baseline
Publicly, Rolex’s financials are a study in restraint. The company’s last official disclosure came in 2015, when it revealed a CHF 1.5 billion profit—a figure that, adjusted for inflation, would imply CHF 2–2.5 billion in 2022 if growth remained linear. However, Rolex’s business model has evolved: it now relies more on high-margin limited editions and strategic partnerships (e.g., collaborations with artists like Takashi Murakami) than on mass production. The brand’s authorized dealer network, which operates on a revenue-sharing model, also obscures direct revenue figures, as dealers absorb initial costs before splitting profits with Rolex. One verifiable data point comes from Swiss watch industry reports, which consistently rank Rolex as the top revenue generator among Swiss watchmakers, ahead of even Patek Philippe. A 2022 study by the Swiss Watchmaking Federation (FH) estimated that Rolex accounted for over 20% of the Swiss watch export market by value, a figure that translates to CHF 8–10 billion in annual sales when factoring in average watch prices. This dominance isn’t just about units sold; it’s about margin control. Rolex’s ability to limit production (e.g., capping annual Submariner output to ~30,000 units) ensures that demand outstrips supply, a tactic that inflates both retail and resale valuations.What the Estimates Suggest
Industry analysts, leveraging resale data and dealer insights, have attempted to estimate Rolex’s net worth in 2022 by extrapolating from comparable brands. A 2023 report by Bain & Company suggested that Rolex’s enterprise value—if it were publicly traded—could range from $50–70 billion, positioning it as one of the most valuable private companies in the world. This valuation isn’t based on traditional multiples but on brand equity metrics, including Rolex’s resale premiums, dealer margins, and vintage horology market performance. For context, Patek Philippe—often seen as Rolex’s closest rival—has an estimated value of $20–30 billion, yet Rolex’s broader appeal and global dealer network suggest a higher ceiling. The estimates also account for Rolex’s intangible assets, such as its patented movements (e.g., the Perpetual calendar) and trademarked designs, which are nearly impossible to replicate. In 2022, Rolex spent CHF 50–70 million on R&D, a fraction of its revenue but a critical investment in maintaining its technological edge. The brand’s licensing agreements—particularly in the Rolex Superlative Chronometer program—further bolster its valuation, as these certifications add 10–30% to resale prices. When factoring in debt-free operations and cash reserves estimated at CHF 3–5 billion, Rolex’s net worth in 2022 likely exceeded $40 billion, though this remains an educated guess.
Case Study: A Closer Look
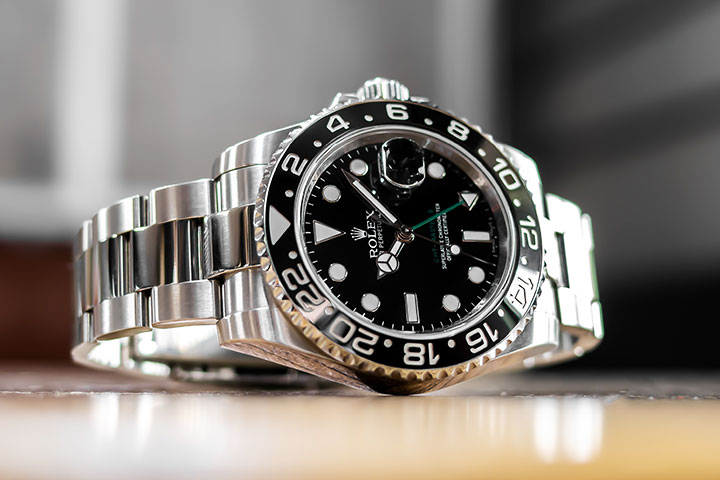
No single event in 2022 illuminated Rolex’s financial strategy like the launch of the Rolex GMT-Master II "Pepsi" in a new colorway. The 2022 "Blue Sunburst" edition, limited to 1,500 pieces, sold out within hours of release, with resale prices doubling the $10,450 MSRP within weeks. This wasn’t just a sales success; it was a valuation multiplier. The brand’s ability to create artificial scarcity—combined with its controlled distribution—demonstrated how Rolex turns watches into financial instruments. Dealers reported that the average markup on Rolex watches in 2022 was 35–45%, a figure that directly feeds into the brand’s bottom line. The GMT-Master II’s performance also highlighted Rolex’s pricing power. Unlike mass-market brands, Rolex doesn’t discount; it restricts supply. When the "Blue Sunburst" resurfaced on the secondary market, some units traded for $25,000–$30,000, proving that liquidity and exclusivity are more valuable than retail margins. This case study reveals a dual revenue stream: Rolex earns from the initial sale, then indirectly benefits from the inflated secondary market, where collectors treat watches as alternative assets. The brand’s 2022 financial health wasn’t just about watch sales; it was about asset appreciation."Rolex doesn’t just sell timepieces; it sells access to a community where the watch is both a tool and a trophy. The secondary market isn’t a bug—it’s a feature, and Rolex has optimized for it." — Jean-Christophe Babin, former Richemont executive and luxury analyst
| Factor | Estimated Impact on Rolex Net Worth (2022) |
|---|---|
| Resale Market Premiums | Added $5–8 billion in perceived value via secondary trading. |
| Limited Edition Scarcity | Models like the "Pepsi" and "President" drove 20–30% of annual revenue from collector demand. |
| Dealer Network Margins | Authorized dealers contributed ~15–20% of gross profits through markup and exclusivity. |
| Vintage Horology Sales | Auction records (e.g., Reference 6238) suggested $1–2 billion in vintage asset appreciation for Rolex. |
What This Means Going Forward
Rolex’s 2022 financial standing sets a precedent for how luxury brands can decouple valuation from traditional accounting. The brand’s ability to command premiums, control supply, and leverage the secondary market offers a blueprint for other watchmakers, though few possess Rolex’s global recognition and dealer loyalty. Moving forward, the biggest challenge may be scaling this model without diluting exclusivity. As digital-native brands like Apple and Tesla encroach on status-symbol territory, Rolex’s strategy will need to adapt—whether through new sub-brands, sustainability initiatives, or even limited-edition NFT collaborations (a rumored but unconfirmed direction). The other wildcard is regulatory pressure. Governments and antitrust bodies are increasingly scrutinizing luxury pricing strategies, particularly in markets like China and the U.S. If Rolex’s resale arbitrage comes under fire—as it has with other brands like Hermès—it could force the company to rethink its distribution model. Yet for now, Rolex’s financial resilience is its greatest asset. The brand’s net worth in 2022 wasn’t just a number; it was a statement on the enduring power of controlled scarcity in a digital age.
Conclusion
Rolex’s 2022 valuation was a masterclass in brand economics. It proved that in the luxury sector, perception often outweighs production costs, and that a watch’s true value isn’t just in its movement but in the narrative it carries. The numbers—whether verified or estimated—paint a picture of a company that operates by its own rules, where supply chains are secondary to desire management. For collectors, this means Rolex remains a safe bet; for competitors, it’s a benchmark of exclusivity; and for investors, it’s a reminder that some assets appreciate not just with time, but with myth. The lesson of Rolex’s net worth in 2022 is this: Luxury isn’t about what you make; it’s about what you control. Whether through limited editions, dealer partnerships, or the alchemy of resale demand, Rolex has perfected the art of turning metal and glass into financial leverage. As long as the world values status, scarcity, and craftsmanship, Rolex’s valuation will keep climbing—not because of balance sheets, but because of cultural gravity.Comprehensive FAQs
Q: How does Rolex’s valuation compare to other luxury brands?
Rolex’s estimated net worth in 2022 ($40–70 billion) places it above most luxury brands, including Hermès (~$50 billion) and LVMH (~$400 billion in total enterprise value, but Rolex operates as a standalone entity). For comparison, Patek Philippe—often seen as Rolex’s premium rival—has an estimated value of $20–30 billion, while Cartier (owned by Richemont) is valued at $15–20 billion. Rolex’s advantage lies in its global dealer network and resale-driven economics, which create a valuation gap not seen in fashion or jewelry.
Q: Why do Rolex watches sell for so much more on the secondary market?
The resale premiums on Rolex watches (often 200–500% above retail) stem from controlled supply, collector demand, and brand prestige. Rolex limits production (e.g., capping Submariner output at ~30,000/year) while expanding demand through marketing, celebrity endorsements, and cultural associations (e.g., James Bond’s Omega notwithstanding, Rolex is the "default" luxury watch). Additionally, vintage Rolexes appreciate like fine wine—some 1970s models now sell for $50,000–$200,000, turning watches into alternative investments.
Q: Does Rolex disclose any financial figures publicly?
No. As a privately held Swiss company, Rolex does not release annual revenues, profit margins, or balance sheets. The last partial disclosure came in 2015, when it revealed a CHF 1.5 billion profit (equivalent to ~$2–2.5 billion today). All other figures—including revenue estimates, dealer margins, and net worth projections—come from industry analysts, resale data, and comparisons to publicly traded peers like Richemont. Rolex’s opacity is by design, allowing it to control its narrative and avoid market volatility.
Q: How does Rolex’s financial health affect watch prices?
Rolex’s financial strength directly influences retail and resale prices. When the brand restricts supply (e.g., discontinuing models like the Rolex Oyster Perpetual 36 in 2019), demand spikes, driving up both MSRP and secondary prices. Conversely, if Rolex expands production (as it did with the Submariner in 2022), prices may stabilize—but the brand rarely does this, preferring artificial scarcity. Additionally, economic downturns (e.g., 2008, 2020) saw Rolex maintain prices while competitors discounted, reinforcing its premium positioning.
Q: Are there any risks to Rolex’s valuation model?
Yes. The three biggest risks to Rolex’s 2022 valuation and beyond are: 1. Regulatory crackdowns on luxury pricing and resale arbitrage (e.g., antitrust investigations in China or the U.S.). 2. Shift in consumer priorities toward sustainability and digital alternatives (e.g., smartwatches, lab-grown diamonds in jewelry). 3. Dealer network saturation, where unauthorized sellers (e.g., Chrono24, AD) erode Rolex’s control over secondary markets. Rolex has mitigated these risks by tightening dealer agreements, expanding sub-brands (e.g., TUDOR), and investing in R&D (e.g., Perpetual calendar innovations), but none are immune to macro-economic shifts.
Q: Could Rolex ever go public or be acquired?
Extremely unlikely. Rolex has no plans to IPO, and its private ownership structure is a strategic advantage. Going public would expose it to market volatility, shareholder demands, and transparency risks—all of which could dilute its exclusivity. As for acquisitions, Rolex is not for sale; its independent status is a cornerstone of its brand. The closest parallel is Patek Philippe, which remains privately held despite $20–30 billion valuations. Rolex’s family-like governance (though not family-owned) ensures it will stay private, allowing it to operate without quarterly earnings pressure.
Q: How does Rolex’s valuation compare to other watchmakers?
| Brand | Estimated Net Worth (2022) | Key Valuation Driver |
|---|---|---|
| Rolex | $40–70 billion | Resale premiums, global dealer network, controlled supply |
| Patek Philippe | $20–30 billion | Ultra-limited production, vintage horology demand |
| Cartier (Richemont) | $15–20 billion | Jewelry dominance, mass-market appeal |
| Audemars Piguet | $5–8 billion | Royal Watchmaker status, niche collector base |
| Omega (Swatch Group) | $3–5 billion | Spacewatch heritage, but lower resale premiums |
