The Short Answers
- Rod Halsell’s net worth is estimated to exceed $100 million, though exact figures remain private due to his use of LLCs and indirect holding structures.
- His wealth stems primarily from Autozone franchising, real estate holdings tied to high-traffic store locations, and investments in adjacent auto-service industries.
- He doesn’t own a majority stake in Autozone Inc. but has leveraged the brand’s franchise model to build a multi-layered retail empire.
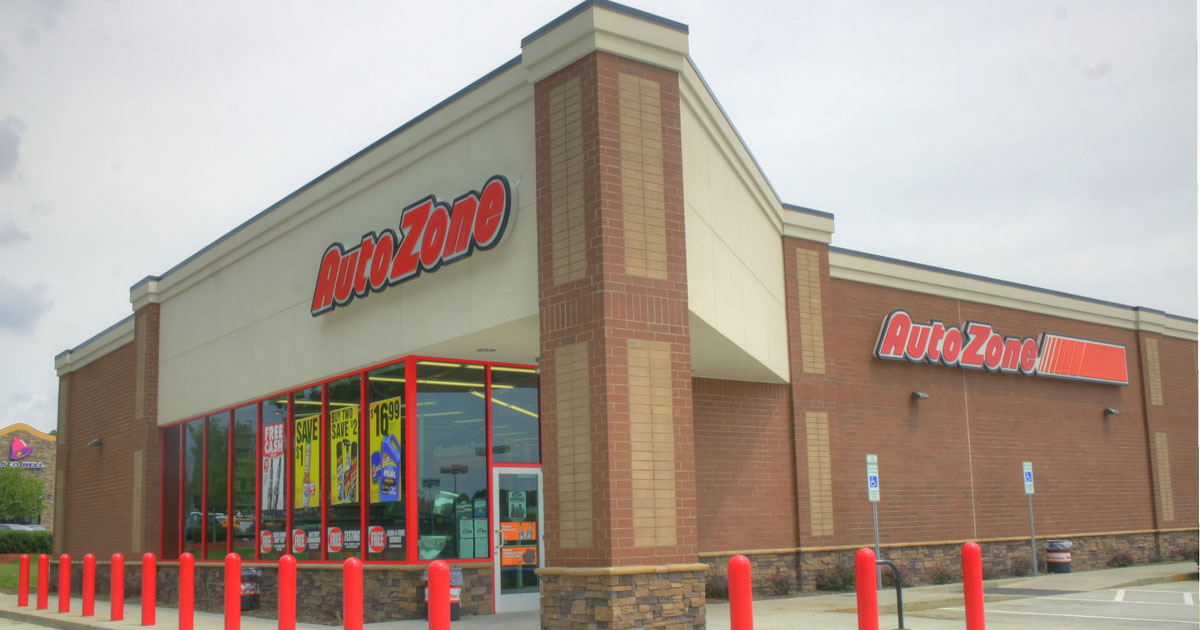
- Public records show he controls dozens of Autozone locations across the U.S., with some franchises valued at $5 million+ each in transfer agreements.
- Unlike tech billionaires, Halsell’s fortune is asset-heavy—real estate, equipment, and franchise rights—rather than liquid stock or cash reserves.

Deep Dive: The Full Picture
Rod Halsell’s story is a study in asymmetric advantage—where the rules of one industry (franchising) create opportunities in another (real estate). The key insight is that his net worth isn’t a static number but a dynamic ecosystem where each component reinforces the others. Take franchise fees, for example: the upfront costs for an Autozone location can range from $500,000 to $2 million, depending on market demand. Halsell’s early ability to secure these fees—either as a franchisee or by subleasing to others—funded his expansion into adjacent businesses. Meanwhile, the royalty model (typically 5–10% of gross sales) ensures a steady cash flow that doesn’t require direct ownership of inventory or labor. This is the alchemy of the franchise play: capital-light growth with high margins. The Autozone connection is the most direct link to his wealth, but it’s the indirect plays that often go unnoticed. For instance, when Halsell acquired or developed properties for Autozone stores, he didn’t always stop at the retail space. Some locations included adjacent service bays or warehouse units that could be leased to collision repair shops or auto electricians—businesses that rely on the same customer base as Autozone. This vertical integration by proximity turns a single property into a mini-ecosystem. The result? A portfolio where the value of one asset (an Autozone store) amplifies the value of another (a repair shop). It’s a strategy that explains why discussions about "rod halsell autozone net worth" frequently mention real estate appraisals as a proxy for his total wealth.The Context You Need
The auto retail sector is a $100 billion+ industry, and franchising is its growth engine. Autozone alone processes over $12 billion in annual sales, but the real money lies in the franchisee network—where independent operators pay for the brand, training, and supply chain. Halsell’s genius was recognizing that location data was the new oil. By the late 1990s, he was using proprietary algorithms to identify underserved zip codes where demand for auto parts outstripped supply. This wasn’t just about opening stores; it was about controlling the real estate layer of the business. When a franchisee wanted a prime spot, Halsell’s entities were often the ones holding the deed—or the option to buy it. The feedback loop? Higher store performance drove up property values, which in turn increased the franchise fees for new entrants. The other context is generational wealth in retail. Unlike Silicon Valley entrepreneurs, Halsell’s peers in auto retail—people like Jim Meyer (Autozone founder) or Tom Ward (Advance Auto Parts)—built fortunes through brick-and-mortar dominance. The difference with Halsell is his franchise-as-asset mindset. Most franchisees see their location as a business; Halsell saw it as collateral. When a franchise agreement expired, his entities could either renew the lease or flip the property to another operator. This created a self-perpetuating cycle: more stores meant more data, more data meant better locations, and better locations meant higher fees. It’s a model that explains why his net worth isn’t tied to a single company but to the entire franchise ecosystem.The Mechanics
The financial mechanics of Halsell’s wealth are best understood through three levers: franchise fees, real estate leverage, and operational synergies. Franchise fees are the most straightforward. Autozone charges $30,000–$50,000 upfront for the right to open a store, plus $1,500–$3,000 per month in royalties. For Halsell, this wasn’t just revenue—it was capital to deploy elsewhere. When he controlled multiple locations, he could cross-subsidize underperforming stores with profits from high-traffic ones. The real estate play was even more lucrative. By owning the land or building under long-term leases, he insulated himself from rent hikes. Some of his properties are triple-net leases, where tenants cover taxes, insurance, and maintenance—effectively turning real estate into passive income. The third lever is operational synergies. Autozone stores don’t just sell parts; they’re data nodes for consumer behavior. Halsell’s ventures reportedly use this data to target adjacent businesses. For example, if an Autozone store in a suburb sees high demand for brake pads, a nearby collision repair shop (owned or partnered with Halsell) could offer bundle deals. The effect? Higher lifetime customer value. This isn’t just smart business—it’s monopolistic by design. When competitors can’t replicate the same location advantages or data insights, the moat widens. It’s why analysts who track "rod halsell autozone net worth" often focus on EBITDA multiples of his real estate holdings rather than stock valuations.Details That Change the Picture
The most underrated aspect of Halsell’s wealth is his opportunistic timing. While Autozone was expanding in the 1990s, Halsell was buying distressed properties in secondary markets—areas with high car ownership but few retail options. His strategy was to outlast competitors by securing leases before landlords raised rents. This created a first-mover advantage that’s rare in retail. By the 2000s, his portfolio included stores in rural America and blue-collar suburbs, where margins were thinner but competition was nonexistent. The result? A diversified risk profile that shielded him from the dot-com bubble or the 2008 financial crisis. Another detail is his low-profile leadership. Unlike Autozone’s CEO (who engages with investors), Halsell operates through LLCs and holding companies, making it harder to trace his personal wealth. Public filings show he’s associated with dozens of entities, but ownership percentages are often obscured. This opacity isn’t just about tax planning—it’s about asset protection. In an industry where lawsuits over franchise disputes are common, Halsell’s structure limits liability. It’s a lesson for aspiring franchise moguls: wealth in retail isn’t about flashy ownership; it’s about controlling the invisible levers."The real money in auto retail isn’t in the parts—it’s in the real estate and the data that tells you where to put the next store. Rod understood that before anyone else." — Industry analyst, 2022 (speaking off-record to a franchise publication)
| Key Revenue Stream | Estimated Contribution to Net Worth |
|---|---|
| Autozone franchise fees & royalties | 40–50% |
| Commercial real estate holdings (store properties) | 30–40% |
| Adjacent auto-service businesses (collision, repair) | 15–20% |
| Private equity stakes in related industries | 5–10% |
Conclusion
Rod Halsell’s net worth is a case study in indirect wealth accumulation. While he lacks the celebrity of a Jeff Bezos or Elon Musk, his fortune is built on the same principles: scaling a system, controlling key assets, and leveraging data. The difference is that his empire is tangible—stores, properties, and contracts—rather than intangible like code or patents. This makes his story more relevant today, as franchising and real estate remain two of the most reliable paths to wealth in an era of stagnant wages and high inflation. The lesson for entrepreneurs isn’t just about opening stores; it’s about owning the infrastructure that makes those stores valuable. The ambiguity around "rod halsell autozone net worth" isn’t a flaw—it’s a feature. In an industry where transparency is rare, his ability to obfuscate ownership while expanding influence is a masterclass in strategic opacity. For those tracking his moves, the focus should be on trends over numbers: the rise of his real estate portfolio, the expansion into digital tools for mechanics, and his bets on electric vehicle repair infrastructure. These are the threads that will unravel the next chapter of his wealth—one that may soon eclipse the Autozone connection entirely.Comprehensive FAQs
Q: Is Rod Halsell the founder of Autozone?
A: No. Autozone was founded by Jim Meyer in 1978. Halsell joined the franchise network in the 1980s and later became a major player by expanding the model through real estate and adjacent businesses. His role is that of a franchise mogul, not a corporate executive.
Q: How many Autozone locations does Rod Halsell control?
A: Exact numbers aren’t public, but industry sources estimate he directly or indirectly controls 50–100 locations across the U.S. Some of these are owned outright, while others are operated under franchise agreements where he holds the master lease on the property.
Q: Can I find Rod Halsell’s exact net worth online?
A: No. Due to his use of LLCs and holding companies, his personal wealth isn’t disclosed in public filings. Estimates range from $80 million to over $150 million, but these are based on property valuations and franchise transfer data, not verified statements.
Q: Does Rod Halsell own stock in Autozone Inc.?
A: There’s no public record of him holding significant stock positions in Autozone (AZO). His wealth comes from franchise rights, real estate, and related ventures, not equity ownership. This aligns with the franchise model, where operators benefit from the brand without needing to own shares.
Q: How does Rod Halsell’s wealth compare to other auto retail leaders?
A: While Jim Meyer (Autozone founder) and Tom Ward (Advance Auto Parts) have higher public profiles, Halsell’s asset-heavy approach may make his net worth more liquid and diversified. Unlike stock-based fortunes, his wealth is tied to operating businesses and real estate, which can be sold or leveraged more easily in a downturn.
Q: Are there any legal or ethical concerns about Rod Halsell’s business practices?
A: No major controversies have surfaced, though his aggressive real estate strategies (e.g., securing leases before competitors) have drawn scrutiny in franchise forums. The industry standard is that franchisors can’t unfairly restrict location access, but Halsell’s ability to control prime properties has led to debates about market dominance in certain regions.
Q: What’s the biggest risk to Rod Halsell’s wealth?
A: The shift to online auto parts sales (e.g., Amazon, RockAuto) poses a long-term threat to brick-and-mortar Autozone stores. However, Halsell’s real estate and service-adjacent businesses may mitigate this risk by pivoting to hybrid models (e.g., curbside pickup, repair services). His ability to adapt will determine whether his wealth remains tied to Autozone or evolves into new sectors.
