
Where It All Began
Rocket Lab’s origins trace back to 2006, when Peter Beck, a 26-year-old aerospace engineer, left a job at NASA to start a company in his parents’ garage in Auckland. The idea was simple: build rockets small enough to launch from New Zealand, avoiding the regulatory and logistical nightmares of larger launch sites. Early prototypes were crude—fueled by school-bus-sized engines and held together with duct tape—but they proved a point: the world needed cheap, frequent access to space. By 2013, the company had secured $7.3 million in seed funding, enough to build its first full-scale rocket, the Electron. The first launch in 2017 was a milestone, but profitability was years away. Rocket Lab burned through cash at a rate that would have sunk many startups. Its net worth at the time was effectively zero—just a balance sheet heavy with debt and a single product line. The company’s survival hinged on two factors: the reliability of Electron and the willingness of customers to pay premium prices for dedicated launches. Early adopters like Spire Global and Planet Labs took the risk, but the real test came when Rocket Lab had to prove it could do more than one-off launches. By 2018, it had achieved that with a back-to-back mission, signaling to investors that Electron wasn’t a fluke.The Early Signs
The signs of potential were there before the IPO. In 2019, Rocket Lab announced a $140 million Series C round, valuing the company at $1.2 billion—a figure that made headlines but was still a drop in the bucket compared to SpaceX’s valuation at the time. What mattered more was the customer base. NASA’s ELaNa missions and commercial contracts from startups like BlackSky showed Rocket Lab wasn’t just a niche player. Yet the company’s financial health remained fragile. Cash burn was high, and the path to profitability was unclear. Then came the pivot: reusability. In 2019, Beck unveiled plans to recover and reuse Electron’s first stage, a move that would require a complete redesign of the rocket’s structure and recovery systems. The gamble paid off in 2022 with the first successful catch of a booster mid-air using a helicopter. The message was clear: Rocket Lab wasn’t just competing on price—it was investing in a future where rockets could be as disposable as airplanes. That shift in strategy didn’t just change the company’s technology; it redefined its valuation potential.The Turning Point
The NASDAQ listing in September 2020 was the inflection point. Rocket Lab went public at $10 per share, raising $150 million and valuing the company at $1.8 billion. The move wasn’t just about capital—it was about credibility. Overnight, Rocket Lab went from a scrappy New Zealand startup to a publicly traded entity with obligations to shareholders. The IPO also forced transparency: for the first time, the public could see the full scope of the company’s financials, including its debt load and the thin margins on each launch. What followed was a period of rapid scaling. Rocket Lab’s market capitalization fluctuated with each major contract and setback, but the trend was upward. By 2021, the company had secured a $171 million contract from the U.S. Space Force to launch satellites for the National Reconnaissance Office, a vote of confidence from the most risk-averse customers in the industry. The same year, it announced plans to build a second launch site in Virginia, doubling its capacity. The question was no longer whether Rocket Lab could grow—it was how fast, and at what cost."Space is a capital-intensive business, but the companies that survive won’t just be the ones with the deepest pockets—they’ll be the ones that can turn launches into a service, not a one-time sale." — Peter Beck, Rocket Lab CEO, 2021
The Build-Up, Year by Year
| Period | Key Developments |
|---|---|
| 2013–2016 | Seed funding secured; first Electron prototype built. Early contracts with research institutions. Net worth effectively zero, but intellectual property and launch pad infrastructure became valuable assets. |
| 2017–2018 | First successful Electron launch (2017). Back-to-back missions prove reliability. Series C round ($140M) valuing the company at $1.2B. Customer base expands to commercial satellite operators. |
| 2019–2020 | Reusability program announced. NASDAQ IPO ($1.8B valuation). First major setback: a launch failure in 2021, but quick recovery with subsequent successes. |
| 2021–2022 | $171M Space Force contract. First successful booster recovery (2022). Photon satellite platform gains traction. Revenue growth accelerates, but cash burn remains high. |
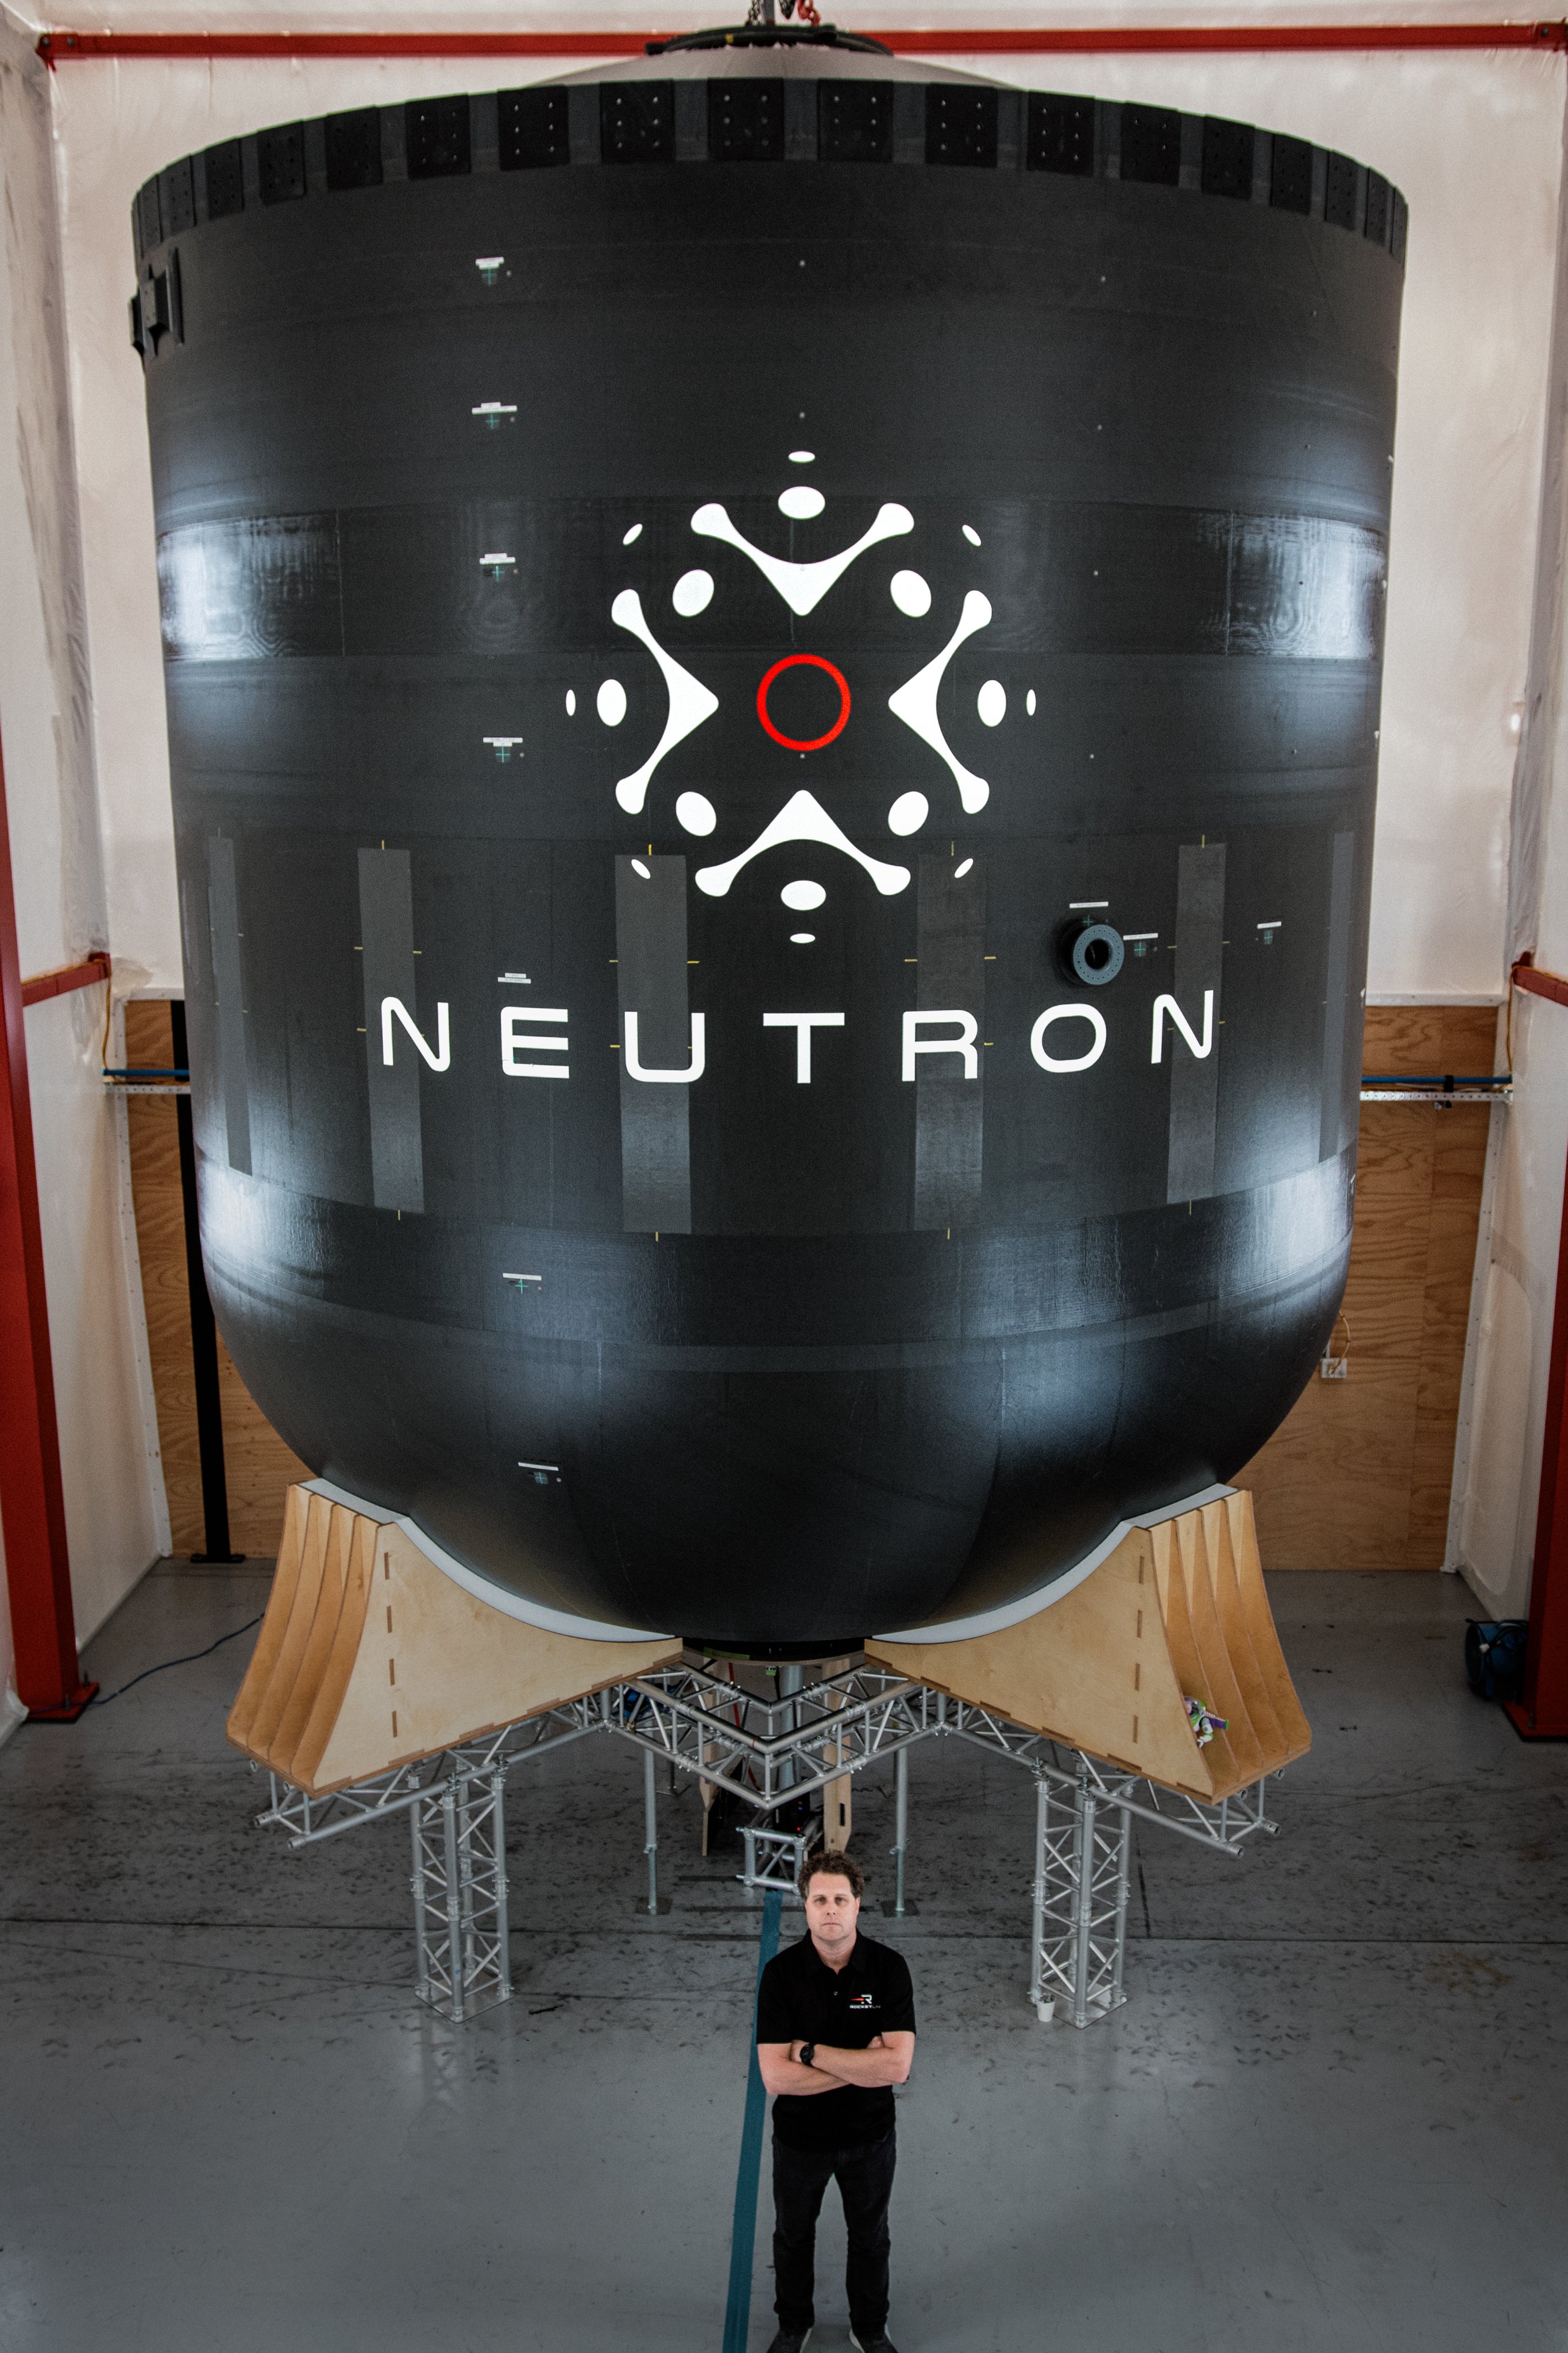
| 2023–Present | Neutron heavy-lift rocket in development (targeting 2024). Partnerships with BlackSky and others diversify revenue. Net worth estimates vary, but industry sources suggest a range between $3B–$5B, depending on Neutron’s success. |
Lessons From the Journey
- First-mover advantage in small-lift rockets created a moat, but it wasn’t enough—Rocket Lab had to innovate continuously to stay ahead.
- Reusability wasn’t just a technical challenge; it was a financial one. The bet paid off, but only after years of investment with no immediate ROI.
- Diversification beyond launches (e.g., Photon, in-orbit services) reduced reliance on volatile satellite demand.
- The IPO forced discipline. Public markets demand transparency, which in turn attracts institutional investors.
- Government contracts (NASA, Space Force) provided stability, but commercial growth remains the key to long-term valuation.
- Culture matters. Rocket Lab’s flat hierarchy and founder-led vision kept the team aligned during lean years.
Where Things Stand Today
As of 2024, Rocket Lab’s financial standing is a study in contrasts. The company’s stock price has seen volatility, reflecting broader industry trends: the satellite boom of the early 2020s has cooled, and margins remain tight. Yet the underlying assets are stronger than ever. The Neutron rocket, designed to compete with SpaceX’s Falcon 9 but at a fraction of the cost, could redefine Rocket Lab’s market position if it succeeds. The company’s net worth is now tied not just to launch services but to its ability to dominate the emerging in-orbit economy—repairing, refueling, and deploying satellites without returning them to Earth. The biggest question isn’t whether Rocket Lab will survive—it’s whether it can transition from a high-growth startup to a sustainable enterprise. The Neutron program is the acid test. If it delivers on its promise of reusability and cost efficiency, Rocket Lab’s valuation could surge. If it stumbles, the company may find itself in a familiar position: chasing the next big bet while keeping the lights on.Conclusion
Rocket Lab’s story is one of defiance. In an industry dominated by billion-dollar behemoths, it carved out a niche and then expanded it into something far larger. The company’s financial journey mirrors the broader shift in space economics: from government monopolies to a crowded, competitive market where agility matters more than scale. Yet for every success, there are reminders of the brutal math of orbital business. The satellite market is cyclical; reusability is expensive; and the margin between profit and loss is razor-thin. What sets Rocket Lab apart isn’t just its technology or its founder’s vision—it’s its ability to adapt. Whether through reusability, in-orbit services, or new launch vehicles, the company has repeatedly redefined its own future. The next chapter will be written in the stars, but the numbers on Earth will determine whether Rocket Lab’s ascent continues—or stalls.Comprehensive FAQs
Q: How is Rocket Lab’s net worth currently estimated?
Industry estimates place Rocket Lab’s valuation between $3 billion and $5 billion as of 2024, depending on the success of its Neutron rocket program and market conditions. The company’s IPO valuation in 2020 was $1.8 billion, but subsequent growth in contracts, diversified revenue streams, and intellectual property have increased its worth. However, exact figures are not publicly disclosed due to private market fluctuations.
Q: What are the biggest financial risks to Rocket Lab’s growth?
The primary risks include the cyclical nature of the satellite launch market, high development costs for Neutron, and competition from established players like SpaceX and emerging rivals. Cash burn remains a concern, particularly as the company invests in reusability and new launch sites. Additionally, regulatory hurdles and geopolitical factors (e.g., export controls on rocket technology) could impact operations.
Q: How does Rocket Lab’s financial model compare to SpaceX?
Rocket Lab operates on a leaner, more specialized model than SpaceX, focusing on small-to-medium lift launches rather than heavy payloads. While SpaceX’s valuation is in the hundreds of billions due to its dominance in large-scale missions and Starship development, Rocket Lab’s model relies on higher-margin dedicated launches and in-orbit services. SpaceX’s economies of scale make it harder for Rocket Lab to compete on price, but Rocket Lab’s niche approach has allowed it to maintain profitability in segments SpaceX ignores.
Q: Has Rocket Lab ever been profitable?
Rocket Lab has not been consistently profitable. While it reported positive net income in some years (e.g., 2021), its revenue growth has often been offset by high R&D costs and cash burn. The company’s path to sustained profitability hinges on Neutron’s success, increased launch cadence, and expansion into higher-margin services like satellite servicing and manufacturing in space.
Q: What role do government contracts play in Rocket Lab’s financial stability?
Government contracts—particularly from NASA and the U.S. Space Force—have been critical to Rocket Lab’s stability. These contracts provide long-term revenue streams and reduce exposure to volatile commercial markets. For example, the $171 million contract with the Space Force in 2021 was a major milestone, demonstrating the company’s reliability for national security missions. However, Rocket Lab continues to prioritize commercial growth to reduce dependence on government funding.
Q: Could Rocket Lab’s net worth decline in the next few years?
Yes, a decline is possible depending on several factors. If Neutron faces delays or cost overruns, investor confidence could wane. A downturn in satellite demand (as seen in 2023) could reduce launch revenue. Additionally, geopolitical tensions or shifts in space policy could disrupt operations. However, Rocket Lab’s diversified revenue streams and strong customer base provide buffers against short-term volatility.
Q: How does Rocket Lab’s stock performance reflect its valuation?
Rocket Lab’s stock (RKLB) has been volatile, reflecting both its growth potential and risks. Since its IPO in 2020, the stock has seen peaks and troughs tied to major events—such as launch successes, contract wins, and market sentiment. For instance, the 2021 launch failure caused a temporary dip, while the 2022 booster recovery announcement boosted shares. Analysts watch the stock as a barometer of investor confidence in the broader "New Space" sector, where valuation is often speculative.
Q: What’s the most undervalued aspect of Rocket Lab’s business?
Many analysts argue that Rocket Lab’s in-orbit services and Photon platform are undervalued. While launches generate most of its revenue, these ancillary services—such as satellite deployment, refueling, and manufacturing in space—represent a long-term growth opportunity. As the satellite industry matures, these services could become a larger portion of the company’s revenue mix, potentially increasing its valuation beyond launch services alone.
