Common Myths About Richemont’s Financial Power
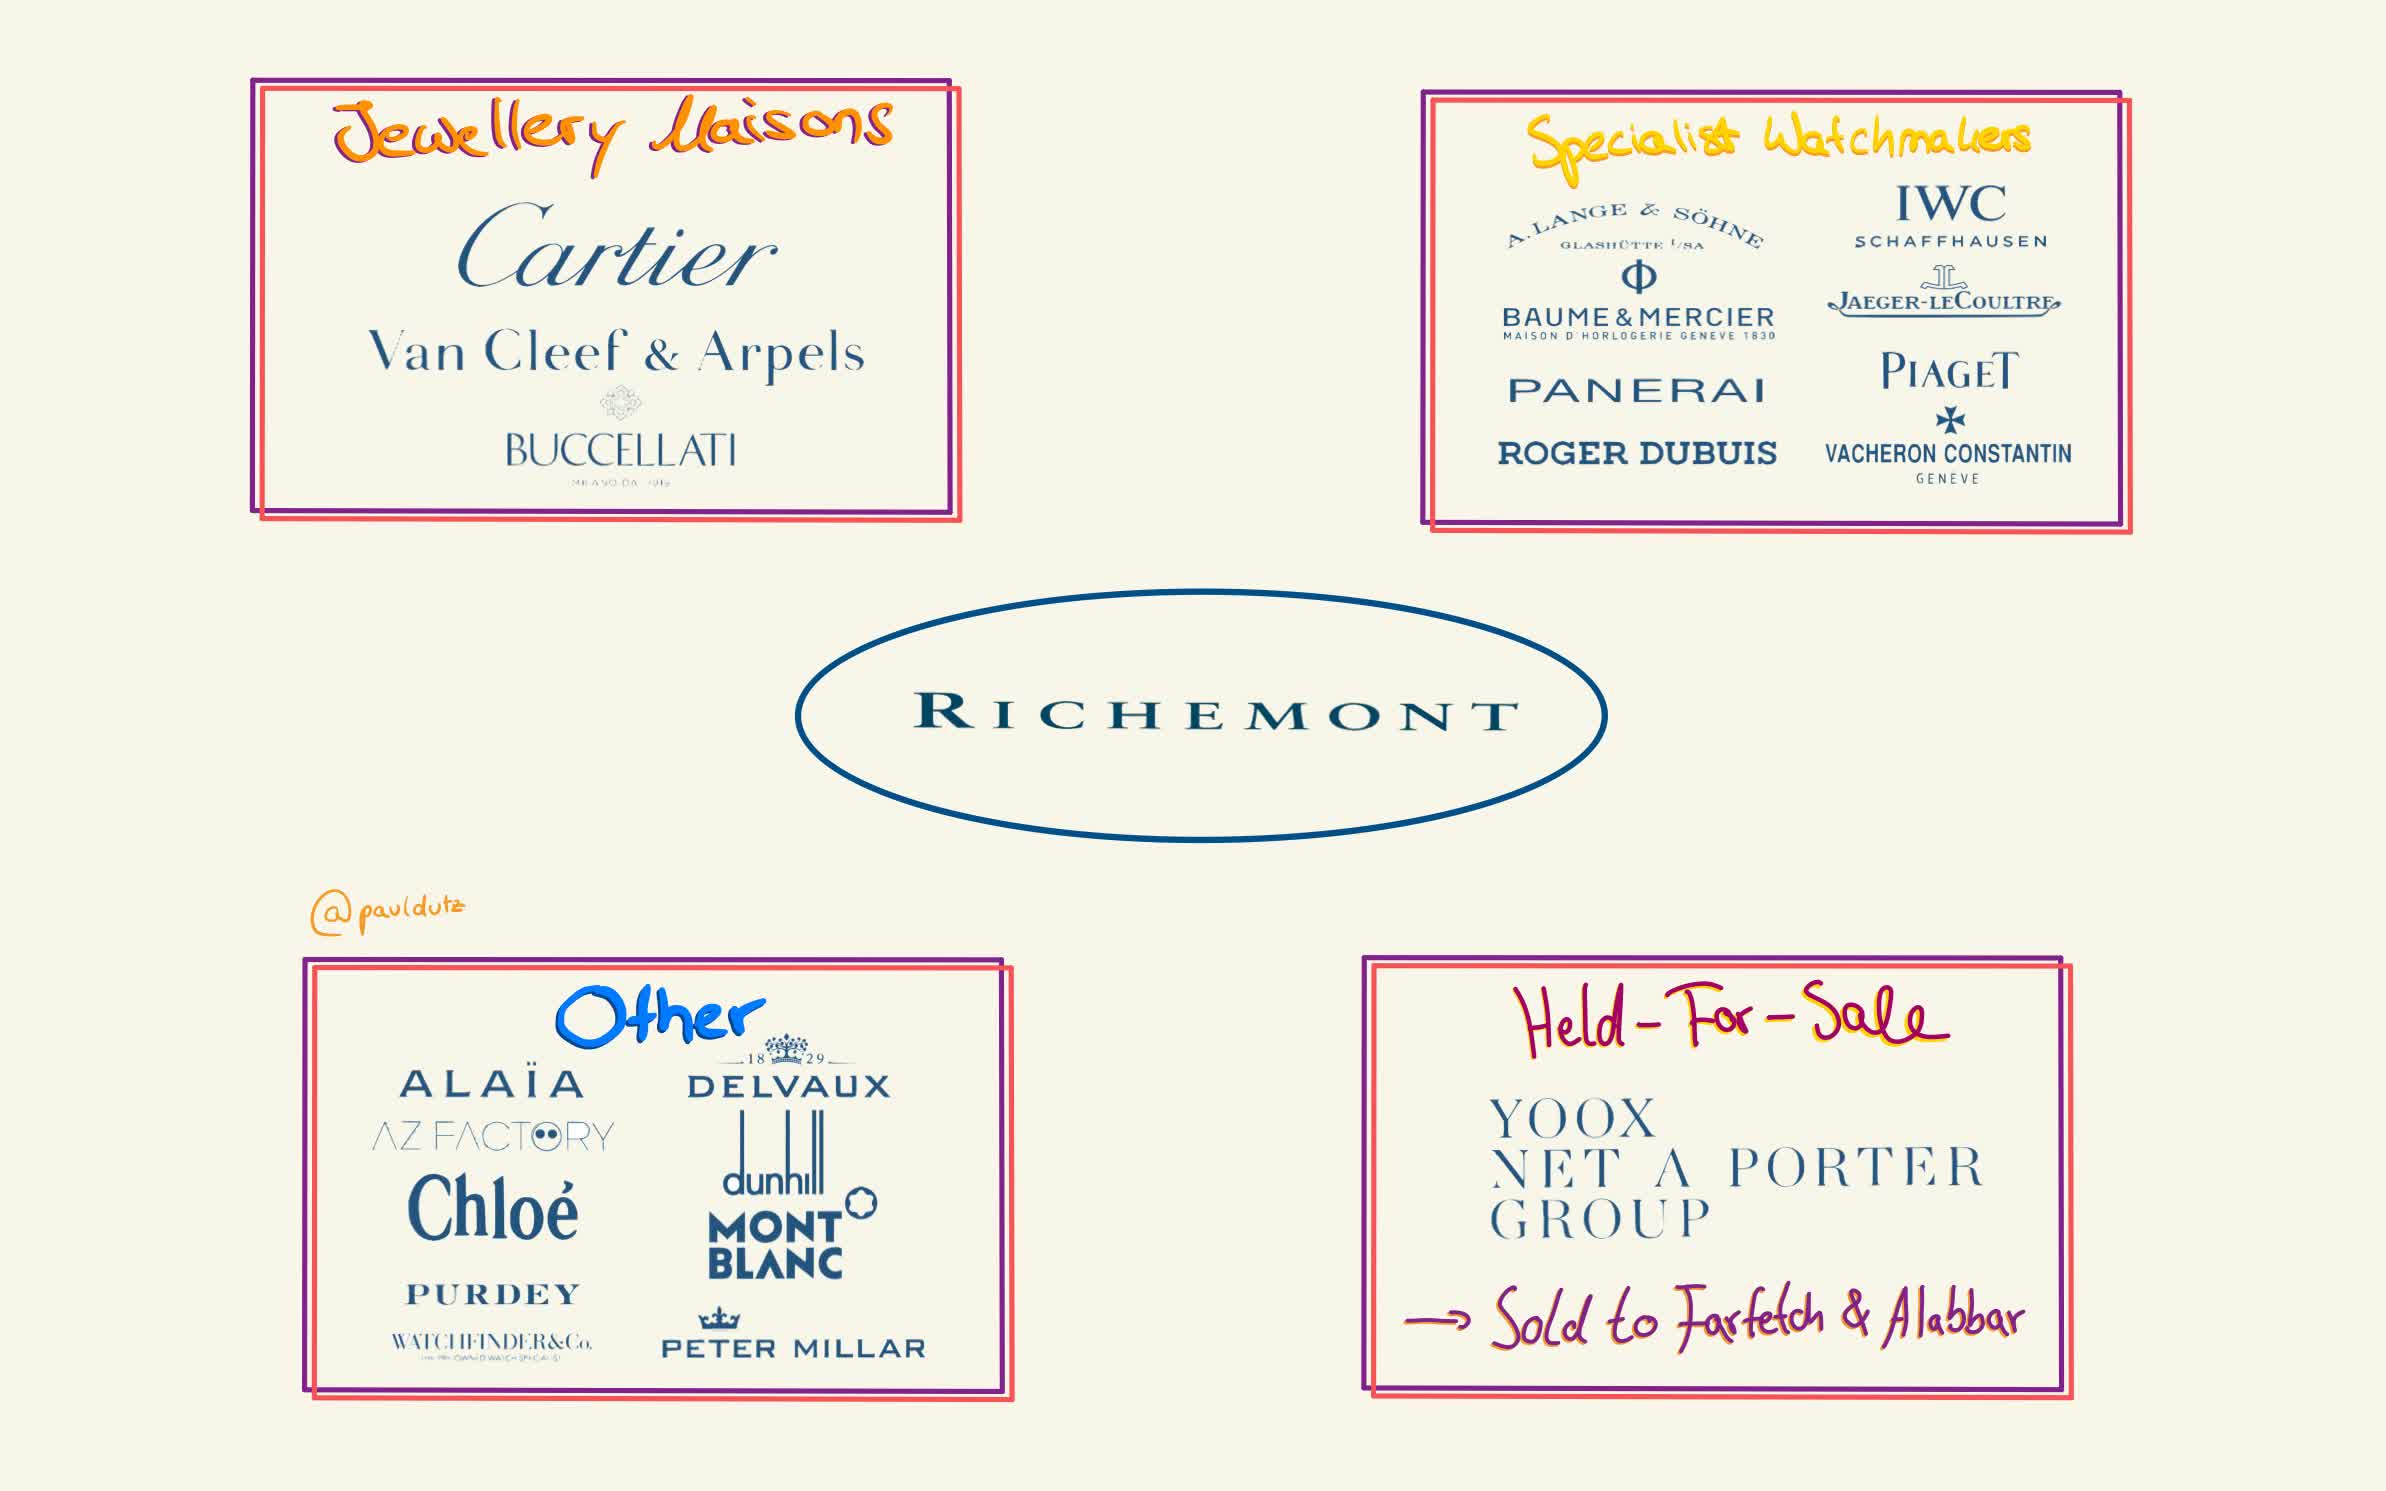
The first misconception is that Richemont net worth can be pinned down with precision, as if it were a listed company’s market cap. In reality, the group’s valuation is a moving target, influenced by private transactions, internal reinvestment, and the whims of high-net-worth collectors. Analysts often conflate Richemont’s reported revenues—which hit €18.3 billion in 2022—with its true net worth, ignoring the vast difference between turnover and equity. The company’s wealth isn’t just in what it earns but in what it owns: real estate portfolios in Geneva and Paris, private equity stakes in unrelated ventures, and the unquantifiable goodwill of its brands. Another persistent myth is that Richemont’s fortune is solely tied to jewelry. While Cartier alone accounts for roughly half of its revenue, the group’s diversification—from pens (Montblanc) to watches (Jaeger-LeCoultre) to even a stake in the London Stock Exchange—spreads risk and obscures the true scale of its assets. Critics also assume that because Richemont avoids public scrutiny, it must be stagnant or inefficient. The opposite is true: its private status lets it make bold, long-term plays, like acquiring brands during economic downturns when competitors hesitate.Myth 1: Richemont’s Net Worth Is Publicly Disclosed
The idea that Richemont’s financials are readily available is a relic of the public markets era. Unlike LVMH, which trades on Euronext Paris, Richemont has never sought an IPO. Its last major shareholder update came in 2016, when it revealed that its net worth exceeded CHF 20 billion—but even that figure was an estimate, not an audit. Private companies aren’t required to disclose earnings or asset values, and Richemont leverages this to its advantage. For instance, its 2021 annual report listed revenues but omitted key details like debt levels or minority stakes, leaving analysts to piece together fragments from regulatory filings in jurisdictions like Monaco or Switzerland. What little is known comes from third-party estimates. Bloomberg and Reuters occasionally publish Richemont net worth projections based on brand valuations and industry benchmarks, but these are educated guesses, not certainties. The group’s refusal to engage with financial media only fuels speculation. In 2020, a leaked internal document suggested its total enterprise value could exceed CHF 35 billion if certain acquisitions were finalized—but the source was never verified. The lesson? Richemont’s wealth is a construct, not a fact.Myth 2: Cartier Alone Defines Richemont’s Wealth
Cartier is the crown jewel, but it’s not the whole kingdom. The brand’s €9.5 billion in 2022 revenue (per industry leaks) makes it Richemont’s cash cow, yet the group’s net worth is a mosaic of contributions. Van Cleef & Arpels, though niche, commands premium prices; Montblanc’s pens and leather goods appeal to a different tier of clientele; and even lesser-known names like Chloé or Officine Panerai generate steady profits. Richemont’s genius lies in its ability to let each brand operate independently while centralizing back-office functions—supply chains, distribution, and digital infrastructure—to maximize margins. The danger of fixating on Cartier is overlooking Richemont’s strategic acquisitions. In 2018, it bought Net-a-Porter for £600 million, a move that diversified its digital presence. Similarly, its 2019 purchase of the London Stock Exchange’s stake in Richemont Financial Holdings (a private equity arm) expanded its financial muscle. These deals don’t show up in annual reports but quietly bolster the group’s underlying net worth. The result? A conglomerate that appears conservative on paper but is aggressively expanding behind the scenes.Myth 3: Richemont’s Wealth Is Static
The assumption that Richemont’s net worth is a fixed number ignores its dynamic nature. Private equity firms like Blackstone or KKR have made fortunes by buying undervalued assets and flipping them—Richemont does this internally, using its brands as growth vehicles. For example, Cartier’s expansion into China and the U.S. isn’t just about selling watches; it’s about locking in long-term demand for luxury goods. Richemont also reinvests profits into R&D, ensuring its brands stay ahead of trends. In 2023, whispers emerged of a potential €1 billion+ acquisition in the watch sector, though nothing was confirmed. Even its real estate plays contribute to its hidden net worth. Richemont owns prime properties in Geneva, Paris, and New York—not just for offices but as assets that appreciate independently. During the pandemic, when luxury retail faltered, Richemont’s property holdings became a silent hedge. The group’s ability to pivot—whether through e-commerce, private sales, or even cryptocurrency experiments (like its 2021 NFT collaboration with Cartier)—means its financial footprint is always evolving.
What Holds Up to Scrutiny
At its core, Richemont’s net worth is built on three pillars: brand equity, asset diversification, and operational efficiency. Cartier’s valuation alone—estimated at €20–25 billion by some analysts—dwarfs the market caps of many publicly traded companies. But Richemont’s strength isn’t just in one brand; it’s in the synergy between them. A customer who buys a Cartier tank watch might later invest in a Montblanc fountain pen or a Van Cleef & Arpels perfume, creating a self-sustaining luxury ecosystem. This vertical integration ensures recurring revenue streams that public companies envy. The group’s private status also shields it from short-term pressures. While LVMH’s stock fluctuates with investor sentiment, Richemont can take a 10-year view. Its reported profitability—with net margins often exceeding 15%—speaks to a business model that prioritizes quality over quantity. Even during economic slowdowns, Richemont’s brands retain their allure, thanks to their association with status and legacy. As one former luxury analyst noted:“Richemont doesn’t just sell products; it sells identity. That’s why its net worth isn’t just numbers on a page—it’s the intangible trust of its clients.”The table below contrasts common perceptions with verified evidence:
| Common Belief | What the Evidence Says |
|---|---|
| Richemont’s net worth is CHF 25 billion. | Estimates range from CHF 28–35 billion, but no official figure exists. |
| Cartier is Richemont’s only profitable brand. | Van Cleef & Arpels and Montblanc also contribute billions annually in pre-tax profits. |
| Richemont avoids risk by staying private. | It takes calculated risks—like its 2020 debt issuance to fund acquisitions—without market scrutiny. |
Why the Confusion Persists
Richemont’s financial opacity is by design. Private companies have no obligation to disclose earnings, debt, or even the identities of major shareholders. Richemont’s largest stakeholder, the Johannsmann family (through holding companies), operates in near-anonymity. This lack of transparency creates a vacuum that analysts and media rush to fill—often with incomplete or outdated data. For instance, a 2021 report in The Wall Street Journal suggested Richemont’s net worth had surpassed CHF 30 billion, but the claim was based on extrapolations from its 2019 figures, not recent filings. The luxury sector itself perpetuates the confusion. Brands like Richemont thrive on exclusivity, and part of that mystique is controlling the narrative. When Cartier unveils a new campaign or Montblanc launches a limited-edition pen, the focus shifts to creativity, not balance sheets. The result? A deliberate blurring of lines between art and commerce, where the true scale of Richemont’s wealth becomes secondary to the stories it tells.
Conclusion
Richemont’s net worth isn’t a number to be dissected—it’s a system to be understood. The group’s power lies not in quarterly reports but in its ability to operate outside the constraints of public markets. While LVMH’s Bernard Arnault is a household name, Richemont’s leaders—like CEO Jean-François Palus—remain shadow figures, their strategies known only to insiders. This isn’t a flaw; it’s a feature. In an era where transparency is prized, Richemont’s refusal to play by those rules makes it all the more formidable. The next time Richemont’s net worth is mentioned, remember: the real story isn’t the valuation itself but what it represents—a masterclass in how to build wealth when no one’s watching.Comprehensive FAQs
Q: Is Richemont’s net worth higher than LVMH’s?
No. While Richemont’s private valuation (estimated at CHF 30+ billion) rivals LVMH’s market cap (€250+ billion), LVMH’s scale—with brands like Dior and Louis Vuitton—dwarfs Richemont’s revenue. The comparison is apples to oranges: Richemont prioritizes exclusivity; LVMH prioritizes mass-market luxury.
Q: Does Richemont pay dividends?
Privately held companies like Richemont don’t issue dividends to the public. Any distributions go to its limited shareholders, such as the Johannsmann family, through private agreements. The group reinvests most profits into acquisitions or R&D.
Q: How does Richemont’s net worth compare to other conglomerates?
Richemont’s estimated net worth (CHF 30+ billion) places it below industrial giants like Nestlé (CHF 100+ billion) but ahead of many private equity firms. Its strength lies in brand equity, not physical assets—unlike, say, a manufacturing conglomerate.
Q: Are there rumors of Richemont going public?
No credible rumors. Richemont has repeatedly stated it has no plans for an IPO. Its private structure allows for long-term strategies that public markets would disrupt, such as patient capital deployment in luxury assets.
Q: Which Richemont brand contributes the most to its net worth?
Cartier is the undisputed leader, generating €9.5+ billion annually (2022 estimates). However, Van Cleef & Arpels and Montblanc also contribute billions in pre-tax profits, while smaller brands like Chloé or Net-a-Porter add digital and retail diversification.
Q: How does Richemont’s net worth affect its stock (if it had one)?
Richemont isn’t publicly traded, so its net worth doesn’t influence a stock price. If it were listed, its valuation would likely be higher than LVMH’s due to its focus on high-margin, niche luxury—but the lack of liquidity means no one outside its shareholders can benefit.
Q: Does Richemont’s net worth fluctuate yearly?
Yes, but not in the way public companies do. Its net worth grows through acquisitions (e.g., Net-a-Porter), reinvestment, and brand appreciation—not stock volatility. Economic downturns may slow revenue growth, but Richemont’s asset-heavy model acts as a buffer.
Q: Are there any legal restrictions on Richemont’s net worth growth?
No major legal barriers, but Switzerland’s banking secrecy laws and Richemont’s private status allow it to operate with minimal regulatory oversight. Antitrust concerns could arise if it acquires a dominant brand in a single market, but its diversification mitigates this risk.
