6 Things Worth Knowing About Private Placement Life Insurance in Canada for High Net Worth Individuals
The distinction between PPLI and conventional life insurance begins with structure. While standard policies offer fixed death benefits, PPLI functions as an insured investment account. Premiums fund a segregated fund or hedge fund managed by the insurer, with policyholders directing allocations across asset classes—often including alternative investments unavailable in retail products. This dual nature (insurance + investment) creates both opportunity and complexity.1. Policyholders Control Asset Allocation Within Limits
PPLI policies in Canada are not one-size-fits-all. High-net-worth individuals can typically choose from pre-approved portfolios—ranging from conservative (60% bonds, 40% equities) to aggressive (private equity, commodities, or even art). Some insurers, like Manulife or Canada Life, offer bespoke PPLI structures where clients collaborate with portfolio managers to tailor allocations. The catch? Performance hinges on the underlying investments, and poor choices can erode both the death benefit and cash value. Industry data suggests that policies with higher equity exposure have outperformed fixed-income-heavy alternatives over the past decade, though volatility remains a persistent risk.2. Tax Advantages Are the Primary Driver
The tax efficiency of private placement life insurance for Canadian high-net-worth families stems from two key levers. First, policy growth is tax-deferred until payout—meaning capital gains, dividends, and interest compound without triggering annual taxes. Second, death benefits are paid tax-free to beneficiaries, provided the policy meets Canada Revenue Agency (CRA) requirements for "exempt life insurance." This contrasts sharply with taxable estates or investment accounts, where beneficiaries may face probate fees or capital gains taxes. For families with assets exceeding $10 million, the potential tax savings can reach hundreds of thousands annually, though exact figures depend on provincial estate laws.3. CRA Compliance Is Non-Negotiable
The CRA’s 2017 policy update tightened scrutiny on PPLI policies, particularly those with high cash values relative to premiums. Insurers must now demonstrate that the policy’s death benefit exceeds its "adjusted cost base" (ACB) by at least 10% annually to avoid classification as a taxable investment. Failure risks recharacterization as a taxable policy, stripping the tax advantages. High-net-worth clients often work with tax lawyers to structure premiums and investments in a way that maintains compliance—though this adds complexity and legal fees. Industry estimates suggest that 30% of PPLI policies in Canada undergo CRA audits, with non-compliant cases facing retroactive tax assessments.4. Liquidity and Access to Cash Values Vary Widely
Unlike traditional whole life policies, PPLI cash values are not immediately accessible. Policyholders must submit requests to withdraw or borrow against accumulated funds, a process that can take weeks. Some insurers impose surrender charges for early withdrawals, and loans may accrue interest. For high-net-worth individuals needing liquidity, this rigidity can be a drawback—though it aligns with the long-term wealth preservation goal. A 2022 report by Deloitte noted that only 15% of PPLI policyholders in Canada access cash values before age 65, with most using the policy as a legacy tool rather than a liquid asset.5. Cross-Border Wealth Transfer Is a Common Use Case
Canadian high-net-worth families with U.S. or international assets often use PPLI to simplify estate distribution. By holding policy assets in Canadian dollars and naming foreign beneficiaries, families avoid currency fluctuations and double taxation. For example, a Canadian resident with a U.S. LLC can structure the PPLI to hold shares in the business, then transfer ownership to heirs without triggering U.S. estate taxes (assuming the policy remains compliant with CRA rules). This strategy is particularly popular among Canadian expatriates and global families, though it requires coordination with both Canadian and foreign tax authorities.6. Costs and Fees Can Erode Returns
PPLI is not cheap. Policyholders face annual management fees (typically 1–2% of assets), underwriting costs, and sometimes additional charges for custom portfolios. These fees can reduce net returns by 0.5–1.5% annually, depending on the insurer. High-net-worth clients must weigh these costs against the tax benefits and flexibility. Some insurers, such as RBC Insurance, offer fee structures that scale with policy size, making PPLI viable for ultra-high-net-worth individuals with $20 million+ in assets. Smaller policies may struggle to justify the expense, particularly if returns fail to outpace inflation.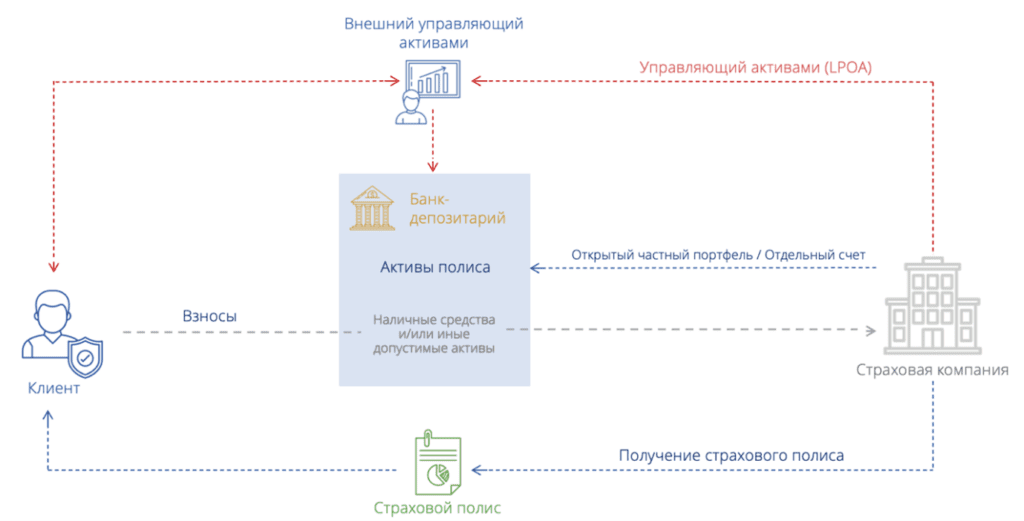
How These Facts Connect
The interplay between tax advantages, asset control, and regulatory hurdles defines private placement life insurance in Canada for high-net-worth individuals as both a tool and a puzzle. The tax-deferred growth and creditor protection are undeniable benefits, but they come with strings: CRA compliance, liquidity constraints, and fees that demand meticulous planning. For families prioritizing wealth transfer over immediate access to capital, PPLI’s strengths align with their goals. Those needing flexibility may find the rigid structure frustrating—though hybrid approaches (combining PPLI with other insurance products) can mitigate this. The data reveals a clear pattern: PPLI thrives where traditional insurance falls short. Policies with aggressive allocations outperform conservative ones, but only if managed by experienced advisors. Cross-border families leverage PPLI to navigate complex tax landscapes, while domestic estates use it to shield assets from probate. The cost of entry remains high, yet for clients with $5 million+ in investable assets, the trade-offs often favor PPLI over alternatives like trusts or corporate structures.| Key Factor | High-Net-Worth Benefit | Primary Risk | Best Use Case | Cost Consideration |
|---|---|---|---|---|
| Tax-Deferred Growth | Eliminates annual capital gains taxes | CRA reclassification if ACB rules breached | Families with $10M+ in taxable assets | 1–2% annual management fees |
| Asset Allocation Control | Access to hedge funds/private equity | Poor performance erodes death benefit | Investors seeking alternative assets | Underwriting costs for custom portfolios |
| Cross-Border Transfer | Avoids currency/tax issues for global heirs | Complexity in dual-tax jurisdictions | Canadian expats with foreign assets | Legal fees for compliance structuring |
| Liquidity Constraints | Protects assets from creditors | Withdrawals take weeks/months | Legacy-focused wealth preservation | Surrender charges for early access |
| CRA Compliance | Maintains tax-free death benefits | Audit risk if ACB thresholds missed | Families with complex estates | Tax lawyer fees ($10K–$50K+) |
Conclusion
Private placement life insurance in Canada is not a panacea, but for high-net-worth individuals with the right goals—tax efficiency, asset protection, and long-term growth—it offers unmatched advantages. The key lies in alignment: policies must match the client’s risk tolerance, estate plan, and liquidity needs. Those who treat PPLI as a "set and forget" solution often regret it; success requires active management of allocations, fees, and compliance. As Canada’s wealth landscape evolves, PPLI will likely remain a staple for families seeking to pass wealth across generations without the drag of taxes or probate. The conversation around PPLI is shifting. Insurers are refining product offerings to address liquidity concerns, while advisors emphasize the importance of integrating PPLI with broader financial plans. For the ultra-affluent, the question is no longer whether to consider PPLI, but how to structure it to serve their unique circumstances.Comprehensive FAQs
Q: What’s the minimum premium required for PPLI in Canada?
A: There’s no strict minimum, but insurers typically require $50,000–$100,000 in annual premiums to justify the administrative costs. Policies below $200,000 may face higher fees relative to returns, making them less viable for smaller high-net-worth portfolios.
Q: Can PPLI be used to buy private businesses or real estate?
A: Yes, but with restrictions. Some insurers allow allocations to private equity or real estate funds, though direct ownership (e.g., holding a business’s shares) may violate CRA rules. Policyholders must ensure the investment aligns with the insurer’s approved asset classes.
Q: How does PPLI compare to a trust for estate planning?
A: PPLI offers tax-deferred growth and creditor protection, while trusts provide control over asset distribution. PPLI is simpler for cross-border transfers but lacks the flexibility of trusts for complex family dynamics. Many high-net-worth individuals use both: PPLI for liquid assets and trusts for illiquid holdings.
Q: Are there alternatives to PPLI for tax-efficient wealth transfer?
A: Yes, including whole life insurance, corporate-owned policies, or charitable remainder trusts. However, PPLI stands out for its investment flexibility and global asset access. Whole life policies lack growth potential, while corporate structures add administrative burden.
Q: What happens if a PPLI policy lapses?
A: The insurer may liquidate assets to cover unpaid premiums, with remaining funds paid to beneficiaries (minus fees). Lapses often trigger taxable events if the policy’s cash value exceeds premiums paid. High-net-worth clients should model scenarios to avoid this outcome.
Q: How do insurers determine eligibility for PPLI?
A: Underwriting focuses on health, financial stability, and the policy’s purpose. Insurers may require proof of liquidity to fund premiums and assess whether the policy aligns with legitimate insurance needs (not just tax avoidance). Rejection rates for PPLI are higher than for standard policies.
Q: Can PPLI be used for charitable giving?
A: Indirectly. High-net-worth individuals can name charities as beneficiaries, but PPLI’s primary purpose remains wealth transfer to heirs. Charitable remainder trusts or donor-advised funds are more straightforward for philanthropic goals.
