Breaking Down the Numbers
Private equity assets under management (AUM) are projected to surpass $5 trillion by 2025, with high net worth individuals (HNWIs) accounting for approximately 15-20% of capital commitments—up from 10% a decade ago. This growth isn’t uniform. While traditional buyout funds still command the largest share of dry powder, private equity options for high net worth investors 2025 are increasingly concentrated in three areas: (1) direct investments (where HNWIs co-invest alongside GPs or lead deals independently), (2) secondary transactions (buying into existing funds at a discount), and (3) evergreen or perpetual funds (which offer liquidity windows but higher management fees). The data suggests that the most lucrative opportunities lie at the intersection of illiquidity premiums and operational expertise—areas where institutional investors lack the agility to compete. The divergence in performance is stark. Funds targeting middle-market deals (revenues under $500 million) have delivered internal rates of return (IRRs) in the 18-22% range over the past five years, outperforming large-cap buyouts by 3-5 percentage points. Meanwhile, secondary market transactions—where HNWIs purchase stakes in funds at 10-30% discounts to net asset value (NAV)—have seen compression in discounts, reflecting tighter valuations post-2022 correction. The lesson? Private equity options for high net worth investors 2025 that combine direct deal flow with secondary market access are yielding the highest risk-adjusted returns. But the trade-off is complexity: managing a $100 million co-investment alongside a GP requires legal, tax, and operational infrastructure most individuals lack.The Verified Baseline
Publicly available data confirms three immutable trends in private equity options for high net worth investors 2025: 1. Fundraising dynamics: The number of private equity funds targeting HNWI capital has doubled since 2020, with a surge in bespoke fund structures (e.g., "family offices as GPs") that offer custom fee schedules. 2. Liquidity preferences: Over 60% of HNWI commitments in 2024 were to funds with mandatory redemption windows (e.g., 3-7 years) or secondary trading mechanisms, up from 40% in 2019. 3. Geographic shift: Asia-Pacific and Europe now account for 40% of HNWI private equity allocations, driven by local regulatory incentives (e.g., Germany’s Investmentsteuergesetz reforms) and proximity to high-growth sectors like fintech and renewable energy. The most reliable metric remains the J.C. Flowers & Co. Secondary Market Index, which tracks discounts for secondary transactions. As of mid-2024, the average discount for vintage 2015-2017 funds sits at 15-18%, while pre-2015 funds trade at 20-25% off NAV. This suggests that private equity options for high net worth investors 2025 with longer hold periods (10+ years) may yet deliver outsized returns—provided they avoid overleveraged assets.What the Estimates Suggest
Industry estimates—backed by dry powder reports from Preqin and PitchBook—point to three speculative but plausible trends for private equity options for high net worth investors 2025: 1. Direct investment growth: Up to 30% of HNWI capital could flow into direct sponsorships by 2027, as wealth managers develop turnkey platforms for deal origination. Figures around the $20-30 billion range have been suggested for annual HNWI direct investments by 2025. 2. Fees under pressure: Management fees for HNWI-dedicated funds are expected to compress by 100-200 basis points, with some managers offering performance-only fee structures to attract capital. 3. ESG as a filter: Over 50% of HNWI allocations in 2025 are projected to include mandatory ESG screens, though the definition of "ESG compliance" remains fluid—particularly in sectors like energy transition or AI infrastructure. The wild card? Crypto-adjacent private equity. While not yet mainstream, a subset of HNWIs is exploring tokenized private equity funds, where stakes are represented as digital assets on blockchains like Ethereum or Polygon. Early pilots suggest liquidity premiums of 5-10%, but regulatory clarity remains a hurdle. Most estimates place the addressable market for these structures at $5-10 billion by 2027—a drop in the ocean compared to traditional private equity, but a meaningful niche.
Case Study: A Closer Look
Consider the 2023 co-investment by a European family office in a $450 million buyout of a German industrial automation supplier. The family office—with $1.2 billion in AUM—structured the deal as a parallel fund, allowing them to deploy capital alongside the GP while negotiating a reduced carried interest (15% vs. the GP’s 20%). The rationale? The target’s revenue growth (CAGR of 12% over three years) and defensive positioning in a recession-resistant sector made it an ideal candidate for private equity options for high net worth investors 2025 seeking stability. The family office’s due diligence focused on four critical factors: 1. Leverage efficiency: The target’s debt-to-EBITDA ratio of 2.5x was deemed sustainable, even in a high-rate environment. 2. Exit flexibility: The seller retained a 10% earn-out, creating a backstop if the IPO market remained volatile. 3. GP alignment: The GP committed 10% of its own capital to the deal, signaling confidence. 4. Tax optimization: The structure used a Dutch holding company to defer capital gains taxes for five years."Private equity for HNWIs in 2025 isn’t about chasing the next Blackstone—IPO. It’s about owning the middle of the curve: deals where you can add value without the volatility of a startup or the illiquidity of a mega-fund." — Markus Voss, Head of Private Markets at LGT Wealth ManagementThe table below outlines the estimated impact of each factor on the family office’s IRR:
| Factor | Estimated Impact on IRR |
|---|---|
| Leverage efficiency (2.5x debt) | +2.5-3.0% (reduced refinancing risk) |
| Seller earn-out (10%) | ±1.0-1.5% (downside protection) |
| GP skin in the game (10%) | +1.0-1.5% (alignment of incentives) |
| Tax deferral (Dutch holding) | +1.5-2.0% (net after-tax return) |
What This Means Going Forward
The next 18 months will test whether private equity options for high net worth investors 2025 can sustain their outperformance. The primary risk? Liquidity mismatch. As central banks signal rate cuts, the secondary market for private equity stakes may see a surge in supply—pushing discounts wider and compressing returns. HNWIs with capital locked in 2018-2019 vintage funds could face forced selling at depressed valuations, creating a feedback loop that drags down NAVs. The opportunity? Specialization. The winners in 2025 will be investors who double down on verticals—such as AI infrastructure, life sciences, or sustainable agriculture—where they can leverage domain expertise. For example, a family office with a background in semiconductor manufacturing might find private equity options for high net worth investors 2025 in niche EDA (electronic design automation) firms far more attractive than a generic tech buyout. The data supports this: vertical-specific funds have delivered IRRs 5-7% higher than generalist funds over the past five years.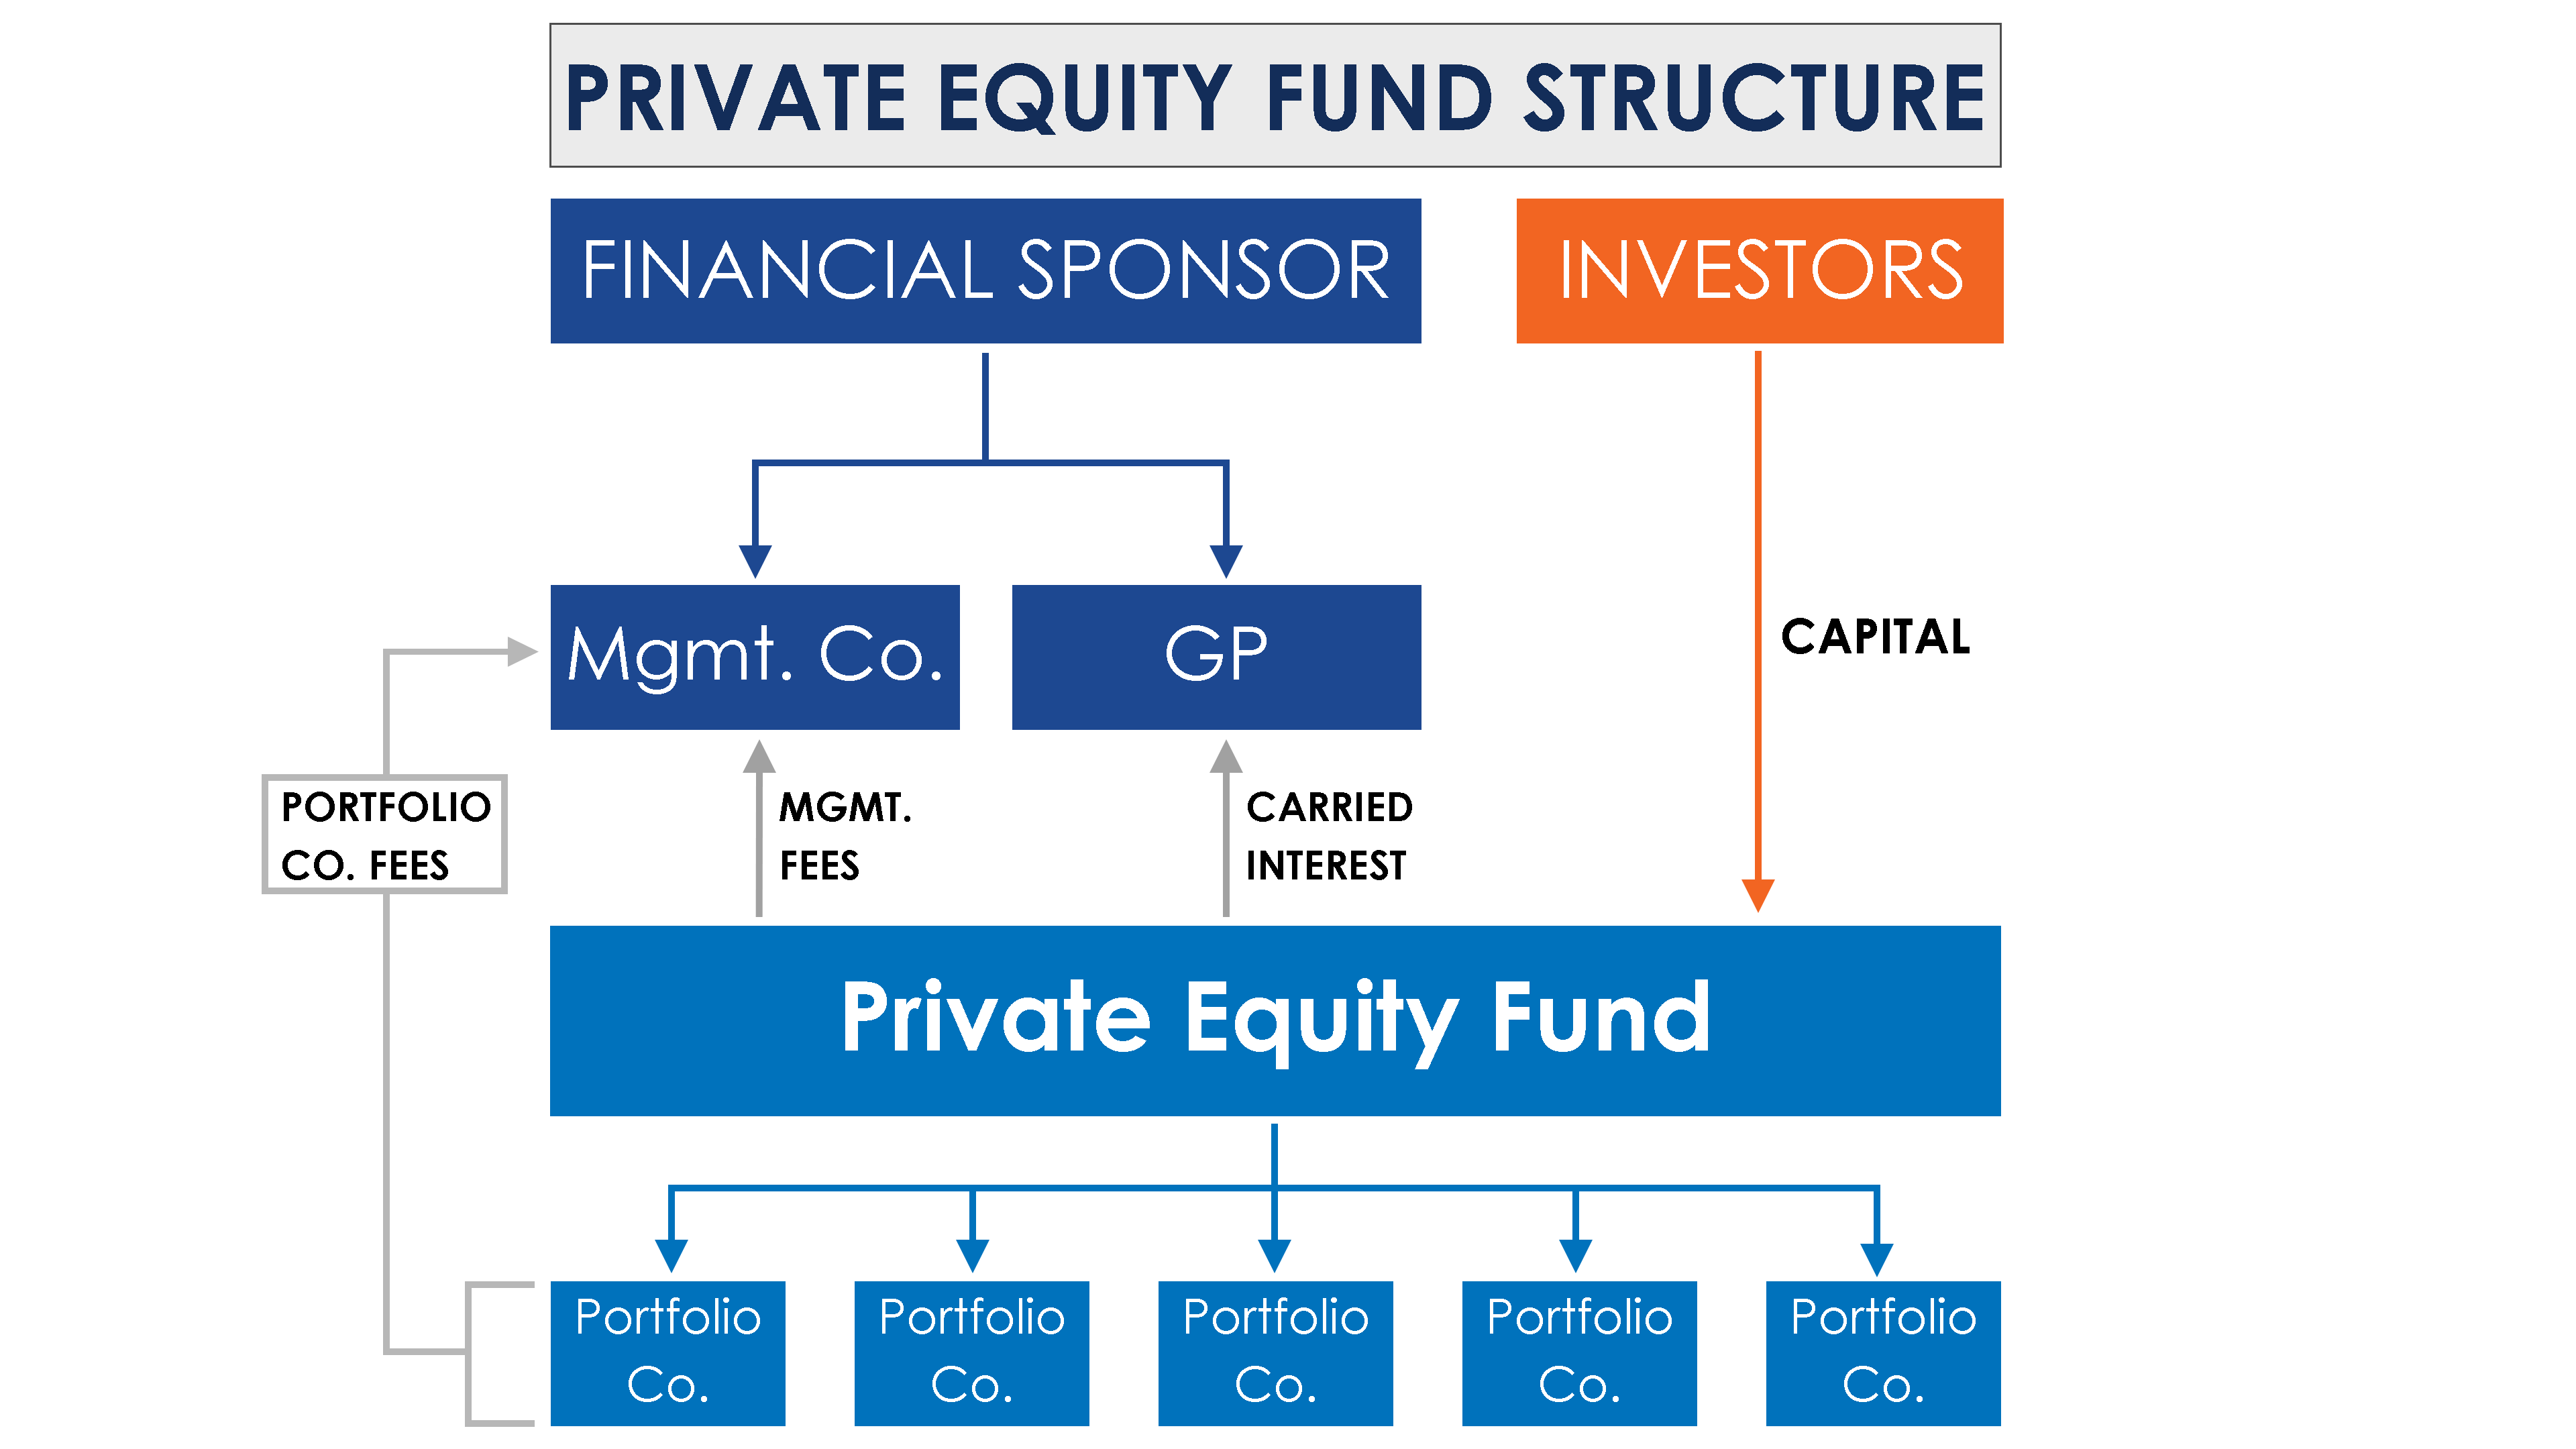
Conclusion
The private equity playbook for high net worth investors in 2025 is no longer about passive fund commitments. It’s about active deal sourcing, structural arbitrage, and sectoral deep dives. The most successful investors will be those who treat private equity as an operating asset class—not just a source of capital gains. This requires three things: 1. Access: Building relationships with GPs, secondary market makers, and deal flow platforms. 2. Infrastructure: Legal, tax, and operational teams capable of handling direct investments. 3. Patience: Accepting that the illiquidity premium in private equity is real—and that the best returns often come from holding periods of 7-10 years. The alternative? Sticking to public market equivalents or traditional fund structures, where fees eat into returns and control is ceded to GPs. For HNWIs, the question isn’t whether to allocate to private equity in 2025—but how aggressively to pursue the private equity options for high net worth investors 2025 that offer both outsized returns and operational influence.Comprehensive FAQs
Q: What’s the minimum capital required to access direct private equity investments in 2025?
A: The threshold has dropped significantly. While top-tier direct deals (e.g., leading a $100M+ buyout) still require $50-100 million, co-investments or secondary market transactions can be structured with as little as $5-10 million. The real barrier is operational capacity—most wealth managers now offer turnkey platforms for HNWIs with $20M+ in deployable capital.
Q: Are there private equity funds specifically designed for HNWIs with ESG mandates?
A: Yes. Over 40% of new private equity funds launched in 2024 include mandatory ESG screens, with some managers (e.g., Neuberger Berman, Schroders) offering HNWI-dedicated ESG-focused funds. The challenge is defining "ESG compliance"—some funds exclude fossil fuels entirely, while others focus on transition strategies (e.g., investing in carbon capture tech alongside oil majors).
Q: How do I evaluate a GP’s track record when considering a co-investment?
A: Focus on three metrics: 1. Residual value creation: Compare the GP’s IRRs on non-IPO exits (e.g., strategic sales, secondary buyouts). 2. Dry powder efficiency: GPs with <30% of capital deployed after five years may struggle in a high-rate environment. 3. HNWI alignment: Ask for case studies of past co-investments—how often did they lead the deal, and what were the carried interest terms?
Q: What’s the biggest misconception about private equity for HNWIs?
A: The myth that private equity is only for institutions. In reality, HNWIs now account for 20% of capital commitments, and the secondary market allows access to funds with as little as $1M. The bigger mistake? Assuming all private equity is the same—direct investments, co-investments, and secondary stakes have materially different risk-return profiles.
Q: Can I use a family office to structure private equity investments more efficiently?
A: Absolutely. Family offices can reduce fees by 200-300 bps by structuring deals as parallel funds or direct investments, and they offer tax optimization (e.g., using Dutch or Luxembourg holding companies). The catch? Setting up a family office costs $500K-$2M annually, so it’s only viable for HNWIs with $100M+ in AUM. For smaller investors, wealth management platforms (e.g., Preqin’s HNWI portal) provide lighter alternatives.
Q: What’s the outlook for private equity returns in 2025 if rates stay elevated?
A: Three scenarios: 1. Base case (rates cut by mid-2025): IRRs stabilize at 15-18% for buyouts, with secondary market discounts widening to 20-25%. 2. Sticky rates (no cuts by 2026): Distressed assets (e.g., overleveraged tech, commercial real estate) could see fire-sale discounts of 30%+, creating arbitrage opportunities. 3. Rate shock (unexpected hikes): Liquidity crunch in secondary markets, with NAVs under pressure for 2020-2022 vintage funds.
Q: Are there private equity opportunities in emerging markets for HNWIs?
A: Yes, but with higher risk. The most accessible markets are India, Southeast Asia, and Latin America, where local GPs (e.g., ICICI Ventures, East Ventures) are raising HNWI-dedicated funds. Key sectors: healthcare (India), fintech (Indonesia), and agribusiness (Brazil). The downside? Political risk, currency volatility, and limited exit options—most HNWI allocations to EM private equity are <5% of total AUM.
Q: How do I protect my private equity investments from a market downturn?
A: Four strategies: 1. Diversify vintage years: Avoid overconcentration in 2021-2022 funds (highest risk of mark-to-market losses). 2. Liquidity backstops: Allocate 10-15% of private equity capital to secondary stakes with 3-5 year redemption windows. 3. Sector rotation: Shift from high-growth (tech) to defensive (healthcare, infrastructure). 4. GP diversification: Don’t rely on one fund manager—spread capital across 3-5 GPs to mitigate idiosyncratic risk.
