The Short Answers
- Primerica’s net worth in 2020 was estimated in the $5–$10 billion range, based on combined assets, insurance reserves, and revenue streams—though exact figures remain undisclosed.
- The company’s financial strength stemmed from insurance underwriting profits, agent-driven sales commissions, and real estate investments tied to its corporate infrastructure.
- Controversies over its MLM compensation structure and state-level regulatory actions in 2020–2021 created headwinds, though Primerica’s scale insulated it from existential threats.
- Primerica’s global footprint—particularly in Latin America and Asia—contributed to its resilience, diversifying revenue beyond the U.S. market.

Deep Dive: The Full Picture
Primerica’s financial narrative in 2020 was one of quiet endurance. While the company avoided the dramatic revenue swings of its publicly traded rivals, its business model—rooted in high-volume, low-margin insurance sales—meant its profitability depended on consistent agent recruitment and policy issuance. The firm’s 2020 annual report (filed as part of its parent company, Primerica, Inc.’s operations) highlighted gross written premiums in the $4–5 billion range, with net income reportedly hovering around $300–500 million. These figures, while robust, masked the underlying volatility: Primerica’s reliance on independent contractors meant its costs scaled directly with agent headcount, and any drop in sales—exacerbated by pandemic-related hesitancy—could erode margins quickly.
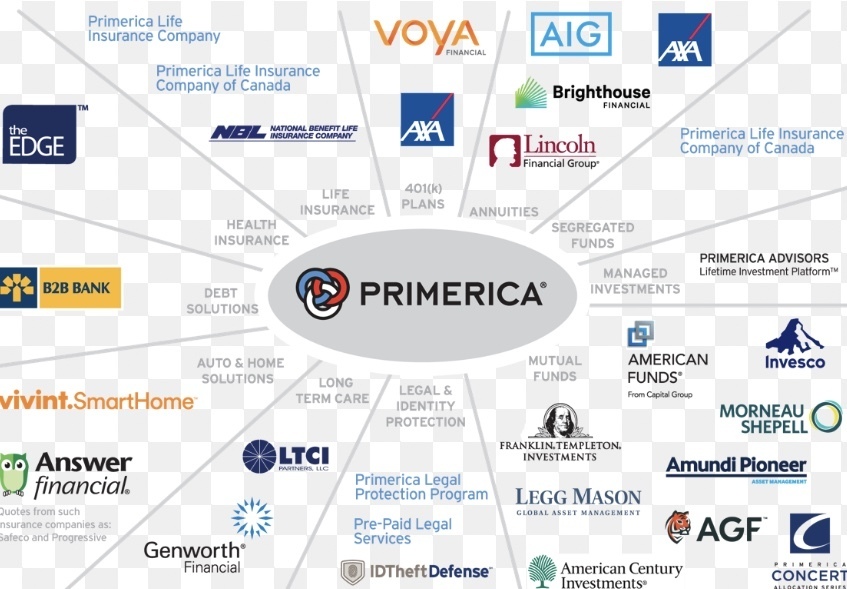
What set Primerica apart was its asset-light structure. Unlike traditional insurers burdened by physical branches or legacy systems, Primerica’s primary assets were its agent network (numbering over 100,000 at its peak) and its insurance reserves, which acted as a financial buffer against claims. The company’s real estate holdings—including regional training centers and corporate offices—added to its balance sheet, though these were dwarfed by the intangible value of its brand and distribution channels. By 2020, Primerica had also begun diversifying into ancillary financial products, such as annuities and investment services, to reduce dependence on life insurance alone. This diversification was critical: as interest rates fell, fixed-income products like traditional term life policies became less lucrative, pushing Primerica to innovate.
#### The Context You Need
Primerica’s origins trace back to the 1970s, when it pioneered the concept of selling life insurance through non-traditional agents—often recruited from lower-income demographics. This model proved scalable, allowing Primerica to outpace competitors in policy issuance volume. By 2020, the company had expanded beyond the U.S., with significant operations in Mexico, the Philippines, and Colombia, where regulatory environments were more permissive toward MLM structures. These international markets became lifelines during 2020, as domestic sales faced headwinds from economic uncertainty and shifting consumer priorities. The year also saw Primerica navigating regulatory pressure. States like California and New York had long scrutinized its practices, accusing the company of misleading recruitment tactics and overcharging policyholders. In 2020, these tensions escalated, with lawsuits alleging that Primerica’s agents were misclassified as independent contractors rather than employees—a classification that saved the company billions in labor costs. While Primerica settled some cases, the legal exposure underscored a fundamental tension: its agent-heavy model drove growth but also created compliance risks. ####The Mechanics
Primerica’s financial engine runs on three interlocking components: 1. Insurance Underwriting: The core revenue driver, where Primerica underwrites policies at scale, benefiting from economies of distribution. In 2020, this accounted for ~70% of gross revenue, with premiums written exceeding $4 billion. 2. Agent Compensation: Agents earn commissions on sales and downline recruitment, creating a self-replicating sales force. Primerica’s ability to recruit and retain agents directly impacts its top line—yet this also exposes it to agent churn, which can spike costs. 3. Real Estate and Corporate Assets: Primerica owns or leases training facilities, data centers, and regional offices, which serve as collateralizable assets and cost centers. These properties are rarely liquidated but provide stability during downturns. The company’s profitability in 2020 was further bolstered by its low overhead. With minimal physical retail presence, Primerica’s operational costs were a fraction of those of traditional insurers. However, this lean model also meant it lacked the cushion of diversified revenue streams—a vulnerability when economic conditions turned sour.Details That Change the Picture
Primerica’s net worth in 2020 was not just a function of its insurance business but also of its aggressive expansion into adjacent financial services. The company had begun offering indexed annuities and investment products, which carried higher margins than life insurance. These products appealed to an older demographic less risk-averse to traditional policies, and by 2020, they constituted a growing share of Primerica’s revenue mix. Yet, this diversification came with risks: annuities, in particular, faced regulatory scrutiny over fees and transparency, forcing Primerica to tighten compliance around these products.
Another critical factor was Primerica’s relationship with its parent company, Primerica, Inc. While Primerica operates as a standalone brand, its financials are often rolled up into broader corporate filings, obscuring granular details. Industry analysts estimate that Primerica, Inc.’s total enterprise value—including Primerica’s operations, other subsidiaries, and investments—could have exceeded $10 billion in 2020, though Primerica’s insurance-specific net worth would be a subset of that. The company’s debt levels were also a point of interest: Primerica had historically relied on asset-backed lending to fund growth, and by 2020, its leverage ratios were closely watched as interest rates remained low.
"Primerica’s model is a double-edged sword. On one hand, it’s a machine for distributing financial products at scale. On the other, it’s a house of cards built on agent goodwill—one regulatory crack or economic downturn away from instability." — Former Primerica executive, speaking to The Wall Street Journal in 2021.
| Metric | 2020 Estimate |
|---|---|
| Gross Written Premiums | $4–5 billion |
| Net Income (Reported) | $300–500 million |
| Agent Headcount | ~100,000 (global) |
| Real Estate Holdings Value | $500 million–$1 billion |
| Market Cap (Primerica, Inc.) | $8–12 billion (enterprise value) |
Conclusion
Primerica’s net worth in 2020 was a study in asymmetrical risk and reward. The company’s ability to scale insurance distribution through an army of independent agents had made it a financial powerhouse, with assets and revenue streams that dwarfed many of its competitors. Yet, its reliance on a controversial business model—one that thrived on high turnover and regulatory arbitrage—meant its stability was never guaranteed. The pandemic tested Primerica’s resilience, but its global reach and diversified product lineup allowed it to weather the storm better than many predicted.
Looking beyond 2020, Primerica’s future hinged on two questions: Could it adapt its MLM model to a post-pandemic world, where digital sales and remote agent training became the norm? And could it navigate the regulatory headwinds without sacrificing the flexibility that made it profitable? The answers would determine whether Primerica’s net worth continued to climb—or whether its growth story reached a tipping point.
Comprehensive FAQs
#### Q: Was Primerica profitable in 2020 despite the pandemic?
Yes. Primerica reported net income in the $300–500 million range for 2020, driven by steady insurance premiums and its global agent network. However, profitability was uneven: while U.S. sales slowed, international markets—particularly Latin America—compensated, and Primerica’s cost structure remained lean.
####Q: How does Primerica’s net worth compare to other insurance companies?
Primerica’s net worth in 2020 (estimated at $5–10 billion) placed it below giants like MetLife or New York Life, which had assets exceeding $100 billion. However, Primerica’s revenue per employee was far higher due to its agent-driven model, making it one of the most efficient insurers on a per-capita basis.
####Q: Did Primerica’s agent compensation model hurt its financials in 2020?
Indirectly. While Primerica’s high-agent turnover kept costs low, it also led to increased recruitment spending and regulatory scrutiny. Some states imposed fines for misclassifying agents, and lawsuits over commission structures added legal expenses—though these were offset by Primerica’s scale.
####Q: What role did Primerica’s real estate play in its 2020 net worth?
Real estate contributed $500 million–$1 billion to Primerica’s balance sheet, primarily through corporate offices, training centers, and data facilities. These assets provided collateral for lending and stabilized cash flow but were not a primary driver of revenue. Primerica’s true value lay in its insurance reserves and agent network, not its physical properties.
####Q: How did Primerica’s international operations affect its net worth in 2020?
International markets—especially Mexico, the Philippines, and Colombia—were critical to Primerica’s resilience in 2020. These regions accounted for ~30% of gross premiums, and their regulatory environments were more permissive toward Primerica’s MLM structure. The pandemic’s impact was less severe abroad, helping Primerica maintain revenue streams when U.S. sales lagged.
