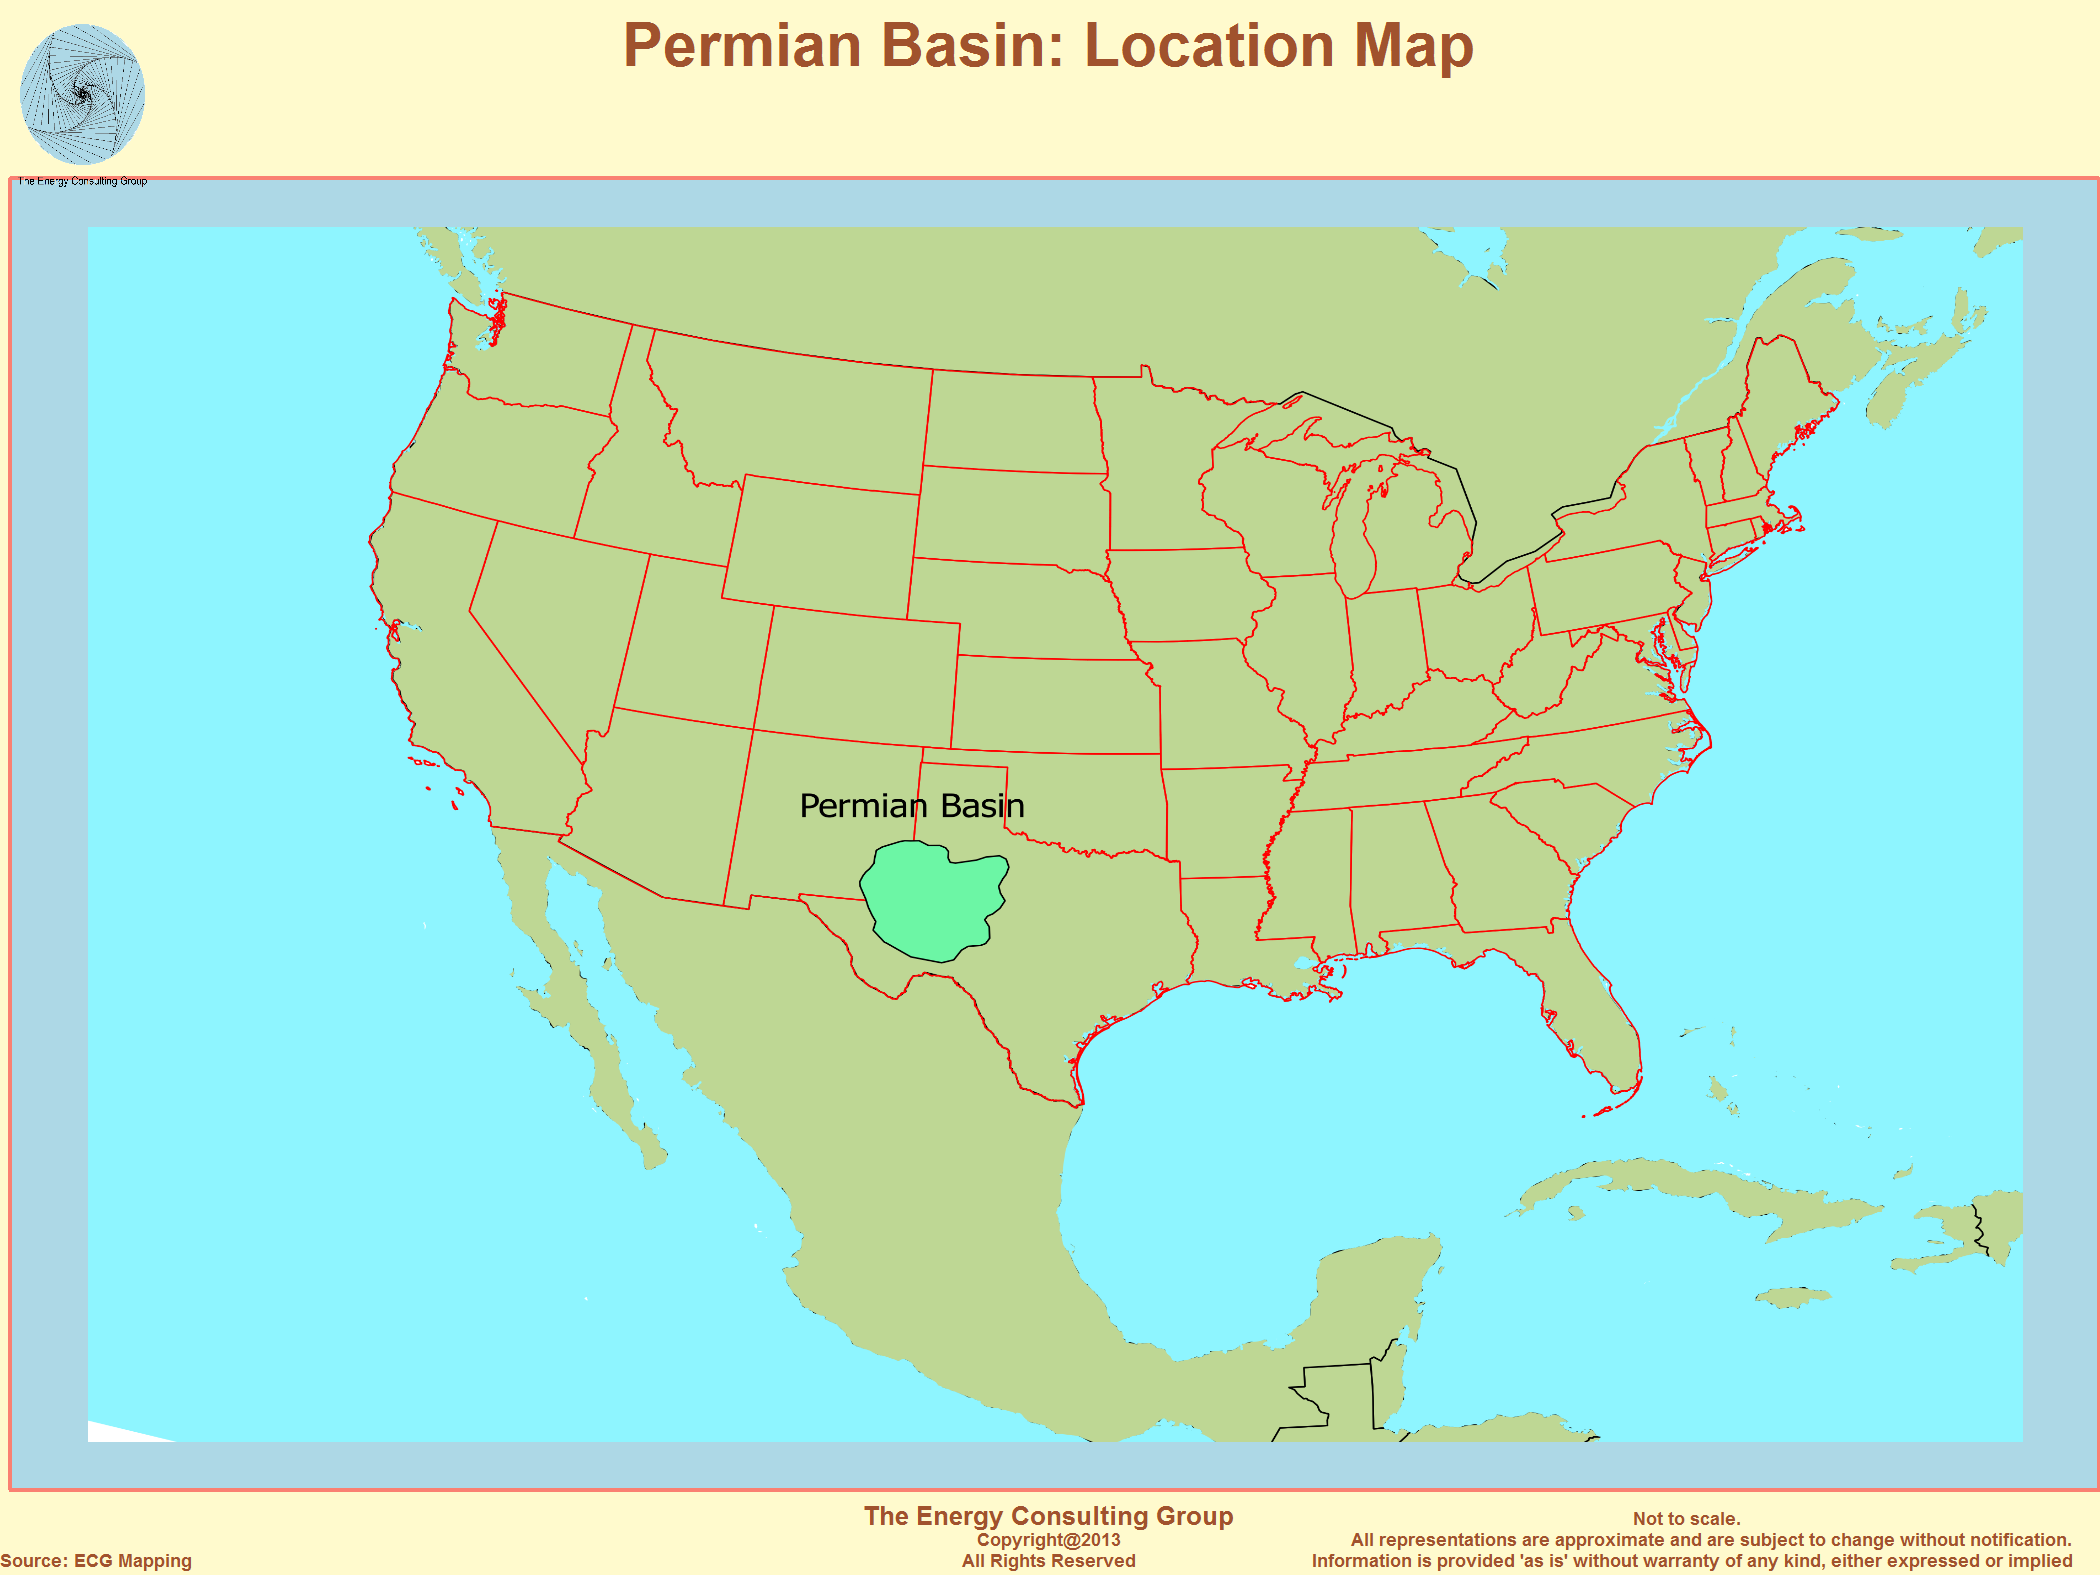
The Complete Overview of Permian Acreage Valuation
The Permian Basin’s net acreage market operates on two parallel tracks: publicly traded deals and private transactions. Publicly announced acquisitions—like Occidental’s $5.8 billion buy of Anadarko’s Permian assets in 2019—set the benchmark, but private sales often reflect true market rates. For instance, when ExxonMobil acquired XTO Energy’s Permian leases in 2010 for $41 billion, the implied $15,000–$20,000 per net acre valuation seemed astronomical at the time. Today, that figure would adjust for inflation, commodity hedges, and midstream integration costs. The Permian’s valuation isn’t uniform. Core areas—like the Midland Basin’s Spraberry formation or the Delaware’s Bone Spring—trade at $10,000–$15,000 per net acre, while outer rings (e.g., Ector County’s Wolfcamp) might fetch $4,000–$7,000. The disparity stems from drillability, well productivity, and infrastructure density. A 2023 report by Enverus highlighted that how much is 85,000 net Permian acres worth? in the Delaware’s core could exceed $1 billion, whereas the same acreage in less developed plays might only justify $300–$500 million. The variable? Proved reserves per acre. What’s often overlooked is the time value of acreage. In the Permian, lease expiration risks loom large. If an operator doesn’t drill within 3–5 years, they lose the lease—unless they farm it out. This creates a race to drill, where acreage values spike when drilling rigs are scarce and plummet when rig counts surge. During the 2014–2016 downturn, how much is 85,000 net Permian acres worth? collapsed to $1,000–$3,000 per net acre as operators shed leases. The rebound in 2017–2019 proved how commodity-driven cycles dictate Permian economics.Historical Background and Evolution
The Permian’s modern valuation era began in the 1980s, when horizontal drilling and hydraulic fracturing unlocked the Spraberry and Wolfcamp formations. Before then, the Permian was a mature conventional play—valued primarily for secondary recovery and enhanced oil rates (EOR). The 1990s saw the first acreage trades, but valuations remained tied to proven reserves rather than unproven potential. It wasn’t until 2008–2010—with the shale revolution—that net acreage became a speculative asset class. Operators like Chesapeake Energy and Apache paid $5,000–$8,000 per net acre for undeveloped leases, betting on future well productivity. The 2014 oil crash acted as a reset button. How much is 85,000 net Permian acres worth? in 2015? $1,500–$2,500 per net acre, as distressed sellers unloaded leases. But the 2016–2018 recovery saw a valuation reset, with core Delaware acres rebounding to $7,000–$10,000 per net acre. The COVID-19 downturn in 2020 briefly depressed prices, but by 2022, midstream bottlenecks and high crude prices pushed valuations back toward $9,000–$12,000 per net acre. The historical trend is clear: Permian acreage is a cyclical asset, and how much is 85,000 net Permian acres worth? depends on where you are in the cycle. Today, the Permian’s valuation is institutionally driven. BlackRock, KKR, and Apollo have all entered the space, buying undrilled leases and producing assets as yield-focused investments. This shift has compressed spreads between core and fringe acreage, as financial buyers pay premiums for location agnosticism. Meanwhile, E&P operators still prioritize high-grading—acquiring only the best-in-class acreage with stacked pay and midstream access.Core Mechanisms: How It Works
Permian acreage valuation follows three core principles: location, infrastructure, and operator strength. Location is non-negotiable. A Delaware Basin lease with Bone Spring pay is worth 2–3x a Wolfcamp lease in Reeves County. Infrastructure—specifically midstream access—adds $2,000–$5,000 per net acre to a parcel’s value. If an acreage package includes direct pipeline connections to Cactus II or Enterprise GT, buyers will pay more. Operator strength matters too: EOG or Diamondback-operated leases command higher multiples than independently held ones. The drilling economics behind how much is 85,000 net Permian acres worth? are brutal. A Wolfcamp well might cost $8–$10 million to drill, but if it produces 2,000–3,000 BOE/day, the internal rate of return (IRR) could justify $10,000–$12,000 per net acre. But if the well underperforms—<1,500 BOE/day—the IRR drops, and acreage valuations stagnate. This is why operators hedge deals with production guarantees or minimum well commitments. Another critical factor is leasehold structure. Net mineral acres (where the buyer owns the minerals but not the surface) trade differently than fee simple acres (full ownership). Net mineral leases are cheaper but come with royalty risks. Fee simple is premium-priced but offers long-term control. The Permian’s mineral ownership is also fractionalized—multiple working interest owners may share a single lease. This dilution can reduce valuation unless the lead operator is financially strong.Key Benefits and Crucial Impact
The Permian’s net acreage market isn’t just about oil and gas—it’s about capital efficiency. Operators with low-cost acreage can outperform peers by drilling fewer, higher-return wells. How much is 85,000 net Permian acres worth? in 2024 depends on whether the buyer can monetize it quickly. Midstream access ensures higher wellhead prices, while stacked pay reduces per-well risk. The Permian’s economics are scale-dependent: a smaller operator might struggle with $85,000 net acres, while a major like Chevron can leverage midstream and hedging to make it profitable. The tax advantages of Permian acreage are often understated. Intangible drilling costs (IDCs) allow operators to write off 100% of drilling expenses in the first year. Depletion allowances further reduce taxable income. For a $1 billion acreage deal, this could mean $200–$300 million in upfront tax savings. How much is 85,000 net Permian acres worth? after taxes? Significantly higher than the gross valuation suggests."The Permian isn’t just about oil—it’s about capital allocation. You’re not buying rock; you’re buying future cash flow at a discount." — Energy analyst at Rystad Energy (2023)
Major Advantages
- High-graded locations in the Delaware or Midland Basin offer proven upside with lower drilling risk.
- Midstream-locked acreage eliminates takeaway constraints, ensuring higher realized prices.
- Stacked pay zones reduce per-well exposure, improving IRR profiles.
- Tax benefits (IDCs, depletion) boost after-tax returns by 20–30%.
- Operated leases command premiums due to better well performance and lower overhead.
Comparative Analysis
| Factor | Permian Basin (85,000 Net Acres) | Eagle Ford (Equivalent) | Bakken (Equivalent) |
|---|---|---|---|
| Valuation Range (2024) | $500M–$1.2B (core Delaware) | $300M–$600M (higher gas exposure) | $200M–$400M (lower liquids mix) |
| Key Driver | Midstream access + stacked pay | Crude quality (light sweet) | Drilling efficiency (lower costs) |
| Risk Factor | Lease expiration, water availability | Regulatory (RAF, flaring rules) | Commodity price volatility |
| Tax Efficiency | High (IDCs, depletion) | Moderate (state taxes) | Low (North Dakota taxes) |
Future Trends and Innovations
The next 5–10 years will see three major shifts in how much is 85,000 net Permian acres worth?: 1. AI-driven drilling optimization will reduce per-well costs, increasing acreage valuations. 2. Carbon capture and storage (CCS) could add a premium to low-emission Permian acreage. 3. Private equity’s role will grow, compressing spreads between core and fringe acreage. The Permian’s long-term value depends on infrastructure expansion. If Cactus II and Enterprise GT add new takeaway capacity, acreage near those pipelines will appreciate. Conversely, if regulatory hurdles slow new pipeline projects, fringe acreage could depreciate. How much is 85,000 net Permian acres worth? in 2030 may hinge on whether the Permian transitions into a low-carbon hub—or remains a high-emission play.
Conclusion
How much is 85,000 net Permian acres worth? isn’t a single answer—it’s a range defined by location, infrastructure, and operator strategy. In 2024, core Delaware acreage could fetch $800–$1.2 billion, while Wolfcamp fringe might settle for $300–$500 million. The Permian’s valuation is cyclical, commodity-sensitive, and infrastructure-dependent. For buyers, the key is high-grading: midstream access, stacked pay, and operated leases drive premiums. The Permian isn’t just an oil play—it’s a financial asset. Operators who understand the valuation mechanics can outperform peers by buying low and selling high. But the Permian’s volatility means timing matters. How much is 85,000 net Permian acres worth? today may not be what it’s worth in two years—unless the buyer has a clear exit strategy.Comprehensive FAQs
Q: What’s the difference between gross acres and net acres in Permian deals?
A: Gross acres include all leased land, while net acres reflect the owner’s working interest (WI) percentage. For example, if you own 75% WI on 100 gross acres, you have 75 net acres. How much is 85,000 net Permian acres worth? assumes 100% net ownership—if it’s non-operated, the value drops due to royalty dilution.
Q: Do Permian acreage valuations include existing wells?
A: Yes, but separately. Producing wells add PV-10 (present value) value, while undeveloped leases trade on future potential. A package with 500 BOE/day might add $50–$100 million to how much is 85,000 net Permian acres worth? depending on well decline rates and commodity prices.
Q: How do midstream contracts affect Permian acreage valuation?
A: Locked-in midstream capacity can increase valuation by 20–30%. If an acreage package includes guaranteed pipeline access, buyers pay premiums because takeaway risks are eliminated. How much is 85,000 net Permian acres worth? without midstream? $20–$30% less than with it.
Q: Are Permian mineral leases transferable?
A: Yes, but with restrictions. Net mineral leases can be sold, traded, or farmed out, but surface access rights may complicate transfers. Fee simple acres are fully transferable, making them more liquid but more expensive. How much is 85,000 net Permian acres worth? depends on whether the buyer wants surface rights.
Q: What’s the biggest risk in Permian acreage deals?
A: Lease expiration and water availability. If an operator doesn’t drill within 3–5 years, they lose the lease. Water scarcity in core Delaware can delay drilling, reducing acreage value. How much is 85,000 net Permian acres worth? in drought-prone areas? $10–$20% less than in water-rich zones.
Q: Do Permian acreage deals include environmental liabilities?
A: Yes, but varies by lease. Older leases may have unplugged wells or orphaned sites, adding cleanup costs. Newer deals often include environmental indemnities, shifting risk to the seller. How much is 85,000 net Permian acres worth? with known liabilities? $5–$15% discount depending on remediation scope.
Q: Can private equity buy Permian acreage directly?
A: Yes, but indirectly. PE firms typically acquire E&P companies (e.g., Apache, Diamondback) rather than raw leases. However, some funds (like BlackRock’s energy arm) buy undrilled leases as yield plays. How much is 85,000 net Permian acres worth? to a PE buyer? $5–$10% less than to a strategic operator due to lack of operational synergies.
Q: What’s the tax treatment of Permian acreage sales?
A: Capital gains rates apply (15–20% for corporations, 0–20% for individuals). IDCs and depletion can offset gains, but depreciation recapture may apply if assets were previously written off. How much is 85,000 net Permian acres worth? after taxes? $10–$20% less than the gross sale price for high-net-worth sellers.
