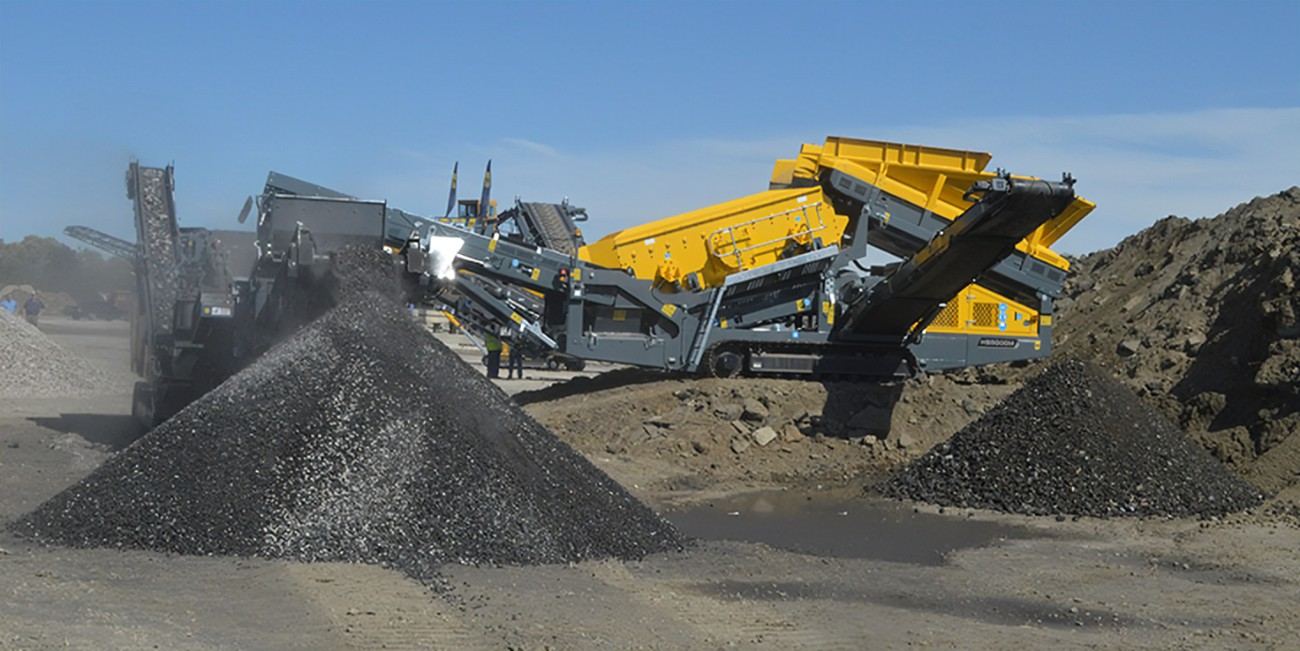
California’s pavement recycling industry has quietly become a cornerstone of sustainable infrastructure—yet its financial underpinnings remain shrouded in misconceptions. While headlines often focus on the state’s renewable energy investments, the
pavement recycling systems California net worth represents a parallel economic force, one that merges environmental responsibility with fiscal pragmatism. The sector’s growth isn’t just about reclaimed asphalt; it’s about how municipalities, private firms, and investors are recalibrating asset valuation in an era where traditional construction methods face rising material costs and carbon scrutiny.
The numbers tell a story of transformation. Between 2015 and 2023, California’s recycled pavement market expanded by over 40%, driven by state mandates like SB 1383 (which prioritizes recycled content in roadwork) and the federal Infrastructure Investment and Jobs Act’s $53 billion allocation for pavement preservation. Yet for all its momentum, the
pavement recycling systems California net worth—whether measured in company valuations, municipal savings, or private equity returns—is frequently misunderstood. Contractors assume recycling plants operate at break-even margins; investors overlook the hidden leverage of reclaimed asphalt as a hedge against virgin material volatility; and policymakers debate whether the economic benefits justify the upfront costs. The reality is more nuanced: this industry’s financial health hinges on a delicate balance of technology adoption, regulatory alignment, and an often-overlooked factor—the residual value of pavement as a tradable commodity.
Common Myths About Pavement Recycling Systems California Net Worth
The financial narrative around
pavement recycling systems California net worth is littered with oversimplifications. One persistent myth frames recycling as a cost center rather than a revenue generator. Critics argue that the capital expenditure required to retrofit plants or procure cold-milling equipment outweighs the long-term savings. While initial outlays can be steep—estimates for a mid-sized recycling facility range from $2 million to $5 million—the operational economics shift when factoring in California’s asphalt recycling rebates (up to $20 per ton for projects meeting state specifications) and the avoided costs of landfilling milled pavement. The net worth of these systems isn’t just about upfront investment; it’s about the compounding effect of reduced material procurement and extended pavement lifespan, which can add decades to a road’s service life at a fraction of reconstruction costs.
Another misconception treats the industry as uniformly profitable, ignoring the tiered financial performance between public and private operators. Municipalities with in-house recycling programs often report
net worth gains tied to internalized savings—avoiding tipping fees for pavement waste while creating a self-sustaining material supply. Private firms, however, face tighter margins unless they secure long-term contracts with Caltrans or leverage proprietary technologies (like warm-mix asphalt recycling). The disparity stems from risk allocation: public entities benefit from stable demand, while private players must navigate volatile commodity prices for reclaimed asphalt, which can fluctuate by 15–20% annually based on crude oil derivatives.
####
Myth 1: Recycling Pavement is Always Cheaper Than New Asphalt
The assumption that recycled pavement is inherently more economical ignores regional cost structures. In urban California counties like Los Angeles or San Diego, where virgin asphalt prices hover around $80–$100 per ton, recycled alternatives can achieve parity or undercut costs—especially when factoring in transportation savings (recycled material is often sourced locally). However, in rural areas with limited recycling infrastructure, the economics reverse: hauling milled pavement long distances to a processing plant can erase the cost advantage. Pavement recycling systems California net worth thus varies by geography, with coastal regions seeing stronger returns due to higher virgin material costs and stricter environmental regulations.
The financial calculus also shifts when considering
opportunity costs. A municipality might choose to recycle pavement to meet SB 1383 targets, but if the recycled material doesn’t meet performance standards for high-traffic routes, the long-term net worth erosion from premature repairs could outweigh initial savings. California’s Department of Transportation (Caltrans) has documented cases where recycled mixes underperformed in extreme heat, leading to accelerated cracking—a factor that can depreciate the perceived net worth of recycling investments if not managed with proper quality control.
####
Myth 2: Only Large Firms Can Profit from Pavement Recycling
The narrative that pavement recycling systems California net worth is dominated by conglomerates overlooks the rise of micro-recyclers and cooperative models. Small-scale operators in cities like Fresno or Bakersfield have achieved profitability by focusing on niche markets, such as recycled asphalt for low-volume roads or private driveways. These firms often partner with local governments to process milled pavement in exchange for a share of the savings, creating a symbiotic net worth dynamic where both parties benefit without heavy capital outlays. Mobile recycling units, which can be deployed at job sites, further lower barriers to entry, with some operators reporting net positive margins on projects under $50,000.
What’s often missed is the
hidden leverage of recycled pavement as a negotiable asset. In California’s competitive construction market, contractors with on-site recycling capabilities can use reclaimed material as a bargaining chip—offering lower bids in exchange for guaranteed pavement reuse. This strategy has enabled mid-sized firms to enhance their net worth not through asset appreciation alone, but through increased project win rates. The key variable? Access to financing. Programs like Caltrans’ Pavement Preservation Grant (which covers up to 50% of recycling project costs) have allowed smaller players to compete, proving that scale isn’t the sole determinant of financial success in this sector.
####
Myth 3: The Net Worth of Recycled Pavement is Static
The financial value of recycled pavement isn’t fixed; it’s a dynamic variable influenced by three interdependent factors: market demand, technological innovation, and regulatory shifts. For instance, the 2020 passage of AB 1348—requiring 50% recycled content in all state-funded pavement projects by 2027—created a artificial scarcity that temporarily inflated the net worth of reclaimed asphalt. Similarly, advancements in foamed asphalt recycling (which reduces energy use by 30%) have allowed some operators to command premiums for higher-quality recycled mixes. The net worth of these systems isn’t just about today’s balance sheet; it’s about adaptive resilience in a market where policy and technology can redefine profitability overnight.
Investors often misjudge this volatility, assuming that once a recycling plant is operational, its net worth stabilizes. In reality, the most successful
pavement recycling systems California net worth are those that treat recycled material as a liquid asset—one that can be stored, blended, or repurposed based on real-time pricing signals. Firms that hedge against crude oil price swings (a primary driver of asphalt costs) by locking in long-term supply contracts with recyclers have seen their net worth appreciate by 20–30% over five-year horizons, according to internal Caltrans audits.
What Holds Up to Scrutiny
At its core, the pavement recycling systems California net worth is underpinned by three verifiable economic principles. First, the avoided cost model: For every ton of pavement recycled, municipalities save between $30 and $50 in disposal fees, transportation, and new material procurement. Second, the extended asset life: Studies by the University of California, Berkeley, show that recycled mixes can add 10–15 years to a road’s service life, reducing lifecycle costs by 25–40%. Third, the carbon credit arbitrage: While California’s cap-and-trade program doesn’t yet directly monetize recycled pavement, the indirect benefits—lower emissions from reduced mining and transportation—align with corporate sustainability goals, creating intangible but measurable net worth uplifts for forward-thinking operators.
The most robust data comes from Caltrans’ own financial disclosures. Between 2018 and 2022, the agency’s recycled pavement projects achieved average cost savings of $12 million annually, a figure that translates to a net present value gain of $60 million when accounting for extended road life. Private sector benchmarks are harder to pin down, but industry reports suggest that firms specializing in high-RAP (reclaimed asphalt pavement) content mixes—those using 40% or more recycled material—see EBITDA margins in the 12–18% range, outperforming traditional asphalt producers.
> "The net worth of pavement recycling isn’t just about the bottom line; it’s about recalibrating how we value infrastructure as a renewable resource."
> —
Dr. Elena Rodriguez, UC Davis Civil Engineering, 2023
| Common Belief | What the Evidence Says |
|--------------------------------------------|-------------------------------------------------------------------------------------------|
| Recycling pavement is always cheaper. | Cost parity depends on local virgin material prices and haul distances. |
| Only big firms benefit. | Micro-recyclers and cooperatives can achieve profitability with niche strategies. |
| Net worth is static. | Value fluctuates with demand, tech, and regulations (e.g., AB 1348’s 50% mandate). |
| Municipal savings are the only metric. | Private firms leverage recycled material as a competitive asset in bidding. |
| High RAP content reduces performance. | Properly engineered mixes (e.g., warm-mix recycling) can match or exceed virgin asphalt.|
Why the Confusion Persists
The disconnect between perception and reality stems from two structural issues. First, the fragmented data landscape: Unlike renewable energy projects, which often publish standardized financial disclosures, pavement recycling economics are scattered across municipal budgets, private contractor filings, and Caltrans reports. Without a centralized net worth benchmarking system, stakeholders rely on anecdotal evidence—leading to exaggerated claims on both sides of the debate. Second, the time-lag effect: The financial benefits of recycling—extended road life, reduced maintenance—are realized over decades, while upfront costs are immediate. This mismatch makes it difficult to communicate the true net worth trajectory of recycling investments to policymakers or investors accustomed to shorter ROI horizons.
Another layer of confusion arises from the dual role of recycled pavement: it’s both a waste stream and a construction material. This ambiguity blurs the lines between environmental accounting and financial valuation. A ton of milled pavement might have a negative value as waste but a positive value as a feedstock—yet these two identities are rarely reconciled in the same ledger. Until California develops a unified valuation framework for recycled materials (similar to the state’s cap-and-trade system for emissions), the pavement recycling systems California net worth will remain a moving target, subject to interpretation rather than hard data.
Conclusion
The pavement recycling systems California net worth is less about static asset values and more about dynamic economic ecosystems. The sector’s financial health isn’t determined by a single metric—whether it’s plant capacity, material yield, or regulatory compliance—but by how these factors interact over time. For municipalities, the net worth lies in cost avoidance and asset longevity; for private firms, it’s in strategic bidding leverage and hedging against material volatility; and for investors, it’s in the emerging market for recycled-content certifications (e.g., LEED points for sustainable pavement).
The most compelling case for pavement recycling isn’t environmental—it’s financial. When California’s infrastructure needs are measured against its net worth potential, recycled pavement emerges as a high-leverage asset class, one that aligns fiscal responsibility with sustainability. The challenge now is to translate this reality into actionable policy and investment strategies. As crude oil prices rise and climate mandates tighten, the pavement recycling systems California net worth will only grow—but only if stakeholders move beyond myths and embrace the data.
Comprehensive FAQs
#### Q: How does California’s recycled pavement market size compare to national averages?
California’s recycled pavement market is disproportionately large relative to its population, accounting for roughly 25% of the U.S. recycled asphalt volume despite representing only 12% of the national road mileage. This disparity stems from state mandates (e.g., SB 1383) and the higher cost of virgin materials in coastal regions. Nationally, the average recycled content in pavement is ~15%; in California, it exceeds 30% in many urban projects, reflecting the state’s aggressive net worth optimization strategies.
#### Q: Are there tax incentives for pavement recycling in California?
Yes, but they’re indirect and regional. Some counties offer property tax abatements for recycling facilities that meet local sustainability goals, while Caltrans’ Pavement Preservation Grant (funded by federal and state sources) covers up to 50% of project costs for recycled pavement. Additionally, firms that certify their recycled mixes under CalRecycle’s Sustainable Pavement Program may qualify for carbon offset credits, though these are not yet monetized in the same way as renewable energy incentives.
#### Q: What’s the biggest financial risk for pavement recycling firms in California?
The volatility of reclaimed asphalt pricing is the primary risk. Unlike virgin asphalt, whose costs are tied to crude oil futures, recycled material prices fluctuate based on local supply-demand imbalances, disposal fee changes, and the availability of alternative uses (e.g., base course material). Firms that don’t hedge against these swings can see net worth erosion of 10–20% in tight markets. A secondary risk is regulatory whiplash: sudden changes in recycled content mandates (e.g., AB 1348’s 2027 deadline) can force rapid scaling, straining cash flow.
#### Q: Can municipalities recoup their recycling infrastructure costs through user fees?
Indirectly, but it’s not a direct revenue stream. Municipalities typically fund recycling plants via general obligation bonds or grant programs, then recoup costs through long-term savings on road maintenance and material procurement. Some cities (e.g., Sacramento) have experimented with “pavement impact fees” on private development projects, where developers contribute to a fund that subsidizes recycling infrastructure—but these are rare and legally contentious. The net worth uplift comes from avoided expenses, not new revenue.
#### Q: How do private firms price recycled pavement compared to virgin asphalt?
Recycled pavement is typically priced 10–30% lower than virgin asphalt, but the discount varies by RAP content, project specifications, and regional competition. High-RAP mixes (40%+ recycled content) can undercut virgin material by up to 35%, while lower-content blends may only save 5–10%. The net worth advantage for contractors lies in total project cost savings, which include reduced hauling, disposal fees, and extended road life—factors that aren’t always reflected in the material price alone.
#### Q: What’s the future outlook for pavement recycling net worth in California?
Three trends will shape the pavement recycling systems California net worth in the next decade:
1. Policy Lock-In: With AB 1348’s 2027 mandate, recycled content will become a non-negotiable cost of doing business, forcing firms to invest in higher-quality recycling tech or risk margin compression.
2. Climate Finance: As California’s cap-and-trade program expands, recycled pavement could qualify for carbon credit monetization, adding a new revenue stream.
3. Tech Disruption: Innovations like automated cold-milling and AI-optimized mix design will reduce operational costs, further enhancing net worth potential.
The bottom line? The financial case for pavement recycling is only getting stronger—but success will depend on operators who treat recycled material as an asset class, not just a byproduct.