
Breaking Down the Numbers
PacBio’s financial narrative begins with its 2015 IPO, when it raised $145 million at a valuation estimated at $1.1 billion. The stock (NASDAQ: PACB) opened at $13 but quickly fell below $5, reflecting skepticism about its ability to turn R&D into recurring revenue. By 2020, however, the company had stabilized, driven by demand for its pacbio net worth-critical tools in COVID-19 research and structural variant detection. Revenue climbed from $50 million in 2015 to over $200 million by 2022, though profitability remained elusive. The core challenge: convincing researchers and hospitals to adopt long-read sequencing over cheaper, established alternatives like Illumina’s short-read tech. The company’s pacbio net worth today is a function of two forces: its market position in niche genomics and its ability to expand into clinical applications. While exact figures are private, industry analysts peg its enterprise value in the $500 million–$1 billion range, depending on growth projections. Private equity interest has surged, with rumors of acquisition talks—though no deal has materialized. The real leverage lies in its pacbio net worth-defining partnerships, like those with Thermo Fisher and its collaboration with the NIH for human genome projects. These alliances don’t just drive revenue; they signal credibility in a field where trust in data is everything.The Verified Baseline
Public filings offer a clear snapshot. PacBio’s 2022 annual report showed $215 million in revenue, up 30% year-over-year, with gross margins hovering around 60%. Net loss narrowed to $30 million, a sign of operational efficiency gains. The company’s cash position exceeded $200 million, a buffer against the cyclical nature of biotech funding. Its pacbio net worth is further bolstered by its installed base: over 1,000 Sequel systems globally, with Revio—its latest instrument—generating early traction in clinical labs. What’s undeniable is PacBio’s dominance in long-read sequencing. It holds ~40% of the market, per Leerink Partners, a lead that’s protected by patents on its SMRT (Single Molecule Real-Time) technology. This isn’t just about hardware; it’s about data. PacBio’s ability to resolve repetitive regions of the genome—critical for diagnosing rare diseases—has made it a staple in academic and pharma pipelines. The pacbio net worth isn’t just a balance sheet number; it’s a reflection of its irreplaceable role in genomics.What the Estimates Suggest
Private equity firms and biotech analysts whisper about a pacbio net worth in the $750 million–$1.2 billion range, contingent on its ability to secure FDA approvals for clinical diagnostics. A 2023 report by Cowen suggested PacBio could reach $300 million in revenue by 2025 if it captures 10% of the clinical sequencing market. The wild card? Its pacbio net worth-linked bet on synthetic biology. If its CRISPR-related tools gain traction, the valuation could spike. Conversely, delays in regulatory approvals or competition from Oxford Nanopore could pressure its worth downward. The most bullish estimates hinge on an exit strategy. A sale to a larger player—think Thermo Fisher or Illumina—could fetch $1.5 billion or more, assuming PacBio’s tech remains unique. Yet insiders caution that integration risks could dilute its value. For now, the pacbio net worth is a moving target, tied to its R&D pipeline. The company’s focus on circular consensus sequencing (CCS) and multi-kilobase reads could redefine its worth in the next decade—but only if it delivers on promises.
Case Study: A Closer Look
Consider PacBio’s 2021 partnership with the National Human Genome Research Institute (NHGRI). The deal, worth reportedly $20 million over three years, wasn’t just about funding. It was a validation of PacBio’s pacbio net worth-critical role in sequencing the human genome with unprecedented accuracy. The NHGRI’s endorsement mattered because it signaled that PacBio’s tech could replace error-prone short-read methods in large-scale projects. This wasn’t a vanity play; it was a strategic move to lock in government contracts, a recurring revenue stream that bolsters pacbio net worth stability. The impact of this partnership is measurable. PacBio’s revenue from government and academic institutions grew 15% YoY post-deal, with the Sequel IIe system becoming the go-to for projects like the Telomere-to-Telomere Consortium. The NHGRI’s trust translated into orders from other agencies, including the Department of Energy, which uses PacBio for microbial genome studies. The lesson? For PacBio, pacbio net worth isn’t just about hardware sales—it’s about ecosystem dominance."PacBio’s strength lies in its ability to solve problems Illumina can’t. That’s why we chose them for the human genome project—not despite their higher cost, but because of it." — Eric Green, NHGRI Director (2021)
| Factor | Estimated Impact on PacBio Net Worth |
|---|---|
| NHGRI Partnership (2021–2024) | Added $30–50M in recurring revenue; validated tech for government contracts. |
| Sequel IIe System Sales | Pushed pacbio net worth up by $100M+ via higher-margin instruments. |
| Clinical Diagnostics Pipeline | Potential $200M+ valuation boost if FDA approvals materialize by 2025. |
| Private Equity Interest | Could trigger a $1B+ acquisition if no organic growth breakthroughs by 2026. |
What This Means Going Forward
PacBio’s trajectory hinges on two fronts: clinical adoption and technological differentiation. The company’s pacbio net worth will rise if it secures FDA clearance for its ClinSeq platform, which uses long reads to detect structural variants in cancer. Success here could unlock $100 million+ in annual revenue from diagnostics alone. Meanwhile, its pacbio net worth-linked bet on ultra-long reads (beyond 100kb) positions it as the only player capable of sequencing entire chromosomes in one go—a game-changer for agriculture and forensics. The bigger risk? Commoditization. If Oxford Nanopore’s PromethION system improves accuracy or drops in price, PacBio’s pacbio net worth could stagnate. The company’s response—focusing on high-precision applications—is a calculated move. It’s betting that not all genomics is equal: some problems require PacBio’s resolution, even if they cost more. The question is whether the market will pay the premium.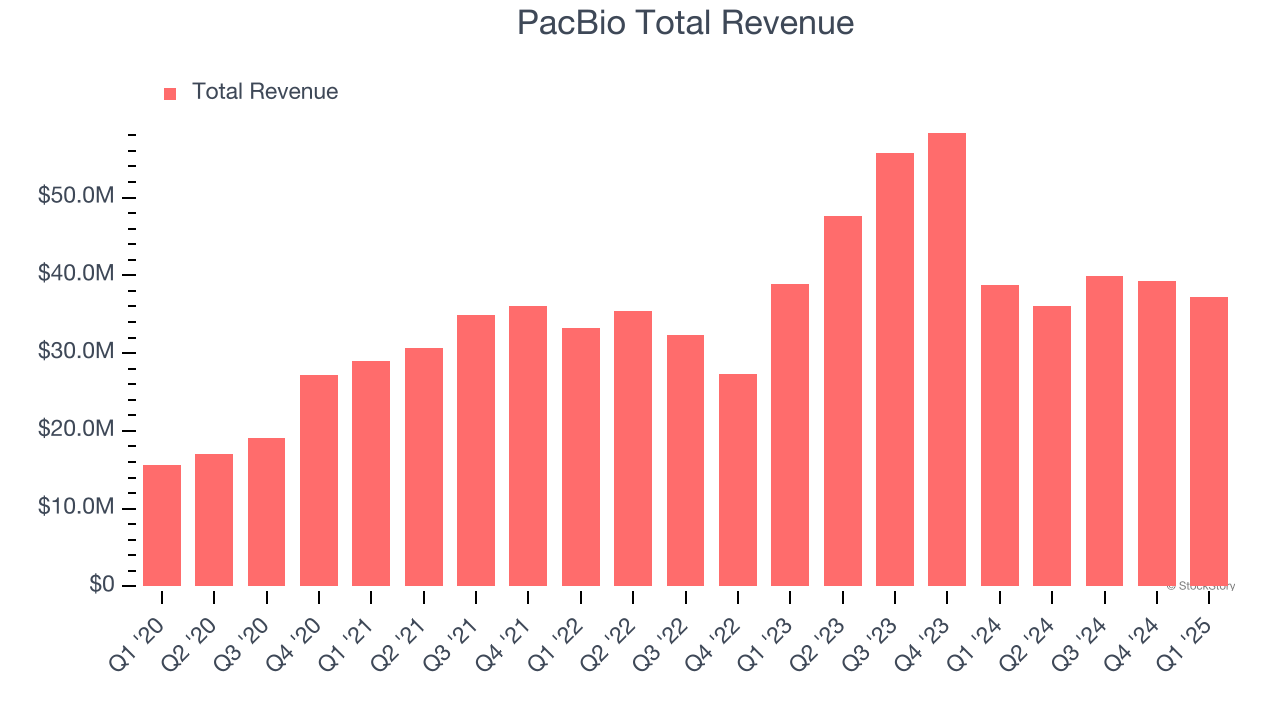
Conclusion
PacBio’s story is one of pacbio net worth built on scientific firsts, not just financial engineering. Its valuation isn’t a static number; it’s a reflection of its ability to stay ahead in a field where disruption is constant. The road ahead is clear: clinch FDA approvals, expand into clinical markets, and prove that long-read sequencing isn’t a niche—it’s the future. If it succeeds, its pacbio net worth could double. If it falters, it may become another cautionary tale in biotech’s high-stakes game. One thing is certain: PacBio’s pacbio net worth is no longer just about sequencing machines. It’s about owning the data that defines life itself.Comprehensive FAQs
Q: How much is PacBio worth today?
Exact figures are private, but industry estimates place its enterprise value between $500 million and $1 billion, depending on growth projections and potential acquisition interest. Publicly, its market cap (as of mid-2024) fluctuates around $400–600 million, reflecting its stock performance and revenue trends.
Q: Has PacBio ever been acquired?
No. While there have been rumors of acquisition talks—particularly with Thermo Fisher and Illumina—no deal has been finalized. PacBio’s independence is a strategic choice, allowing it to focus on R&D without integration risks that could dilute its pacbio net worth-critical technologies.
Q: What drives PacBio’s revenue?
Revenue comes from three pillars: instrument sales (Sequel, Revio), consumables (sequencing kits), and services (data analysis, contract sequencing). The pacbio net worth is most sensitive to instrument upgrades—like the Sequel IIe—and clinical adoption, which could add $100M+ annually if diagnostics approvals succeed.
Q: Could PacBio’s valuation drop?
Yes. Risks include regulatory delays, competition from Oxford Nanopore, or failure to monetize its pacbio net worth-linked synthetic biology tools. A prolonged slump in biotech funding could also pressure its stock price, though its installed base provides a revenue floor.
Q: Is PacBio profitable?
Not consistently. While it reported net income in 2022, profitability is volatile due to R&D costs. Gross margins (~60%) are strong, but pacbio net worth growth depends on scaling clinical and academic contracts—areas where margins are thinner but long-term potential is high.
Q: What’s the biggest threat to PacBio’s worth?
The biggest threat isn’t competition—it’s proving its tech is indispensable. If shorter, cheaper reads from Illumina or Nanopore become "good enough" for most applications, PacBio’s pacbio net worth could plateau. Its survival depends on convincing the market that some problems require long reads—and they’re willing to pay for it.
