Breaking Down the Numbers
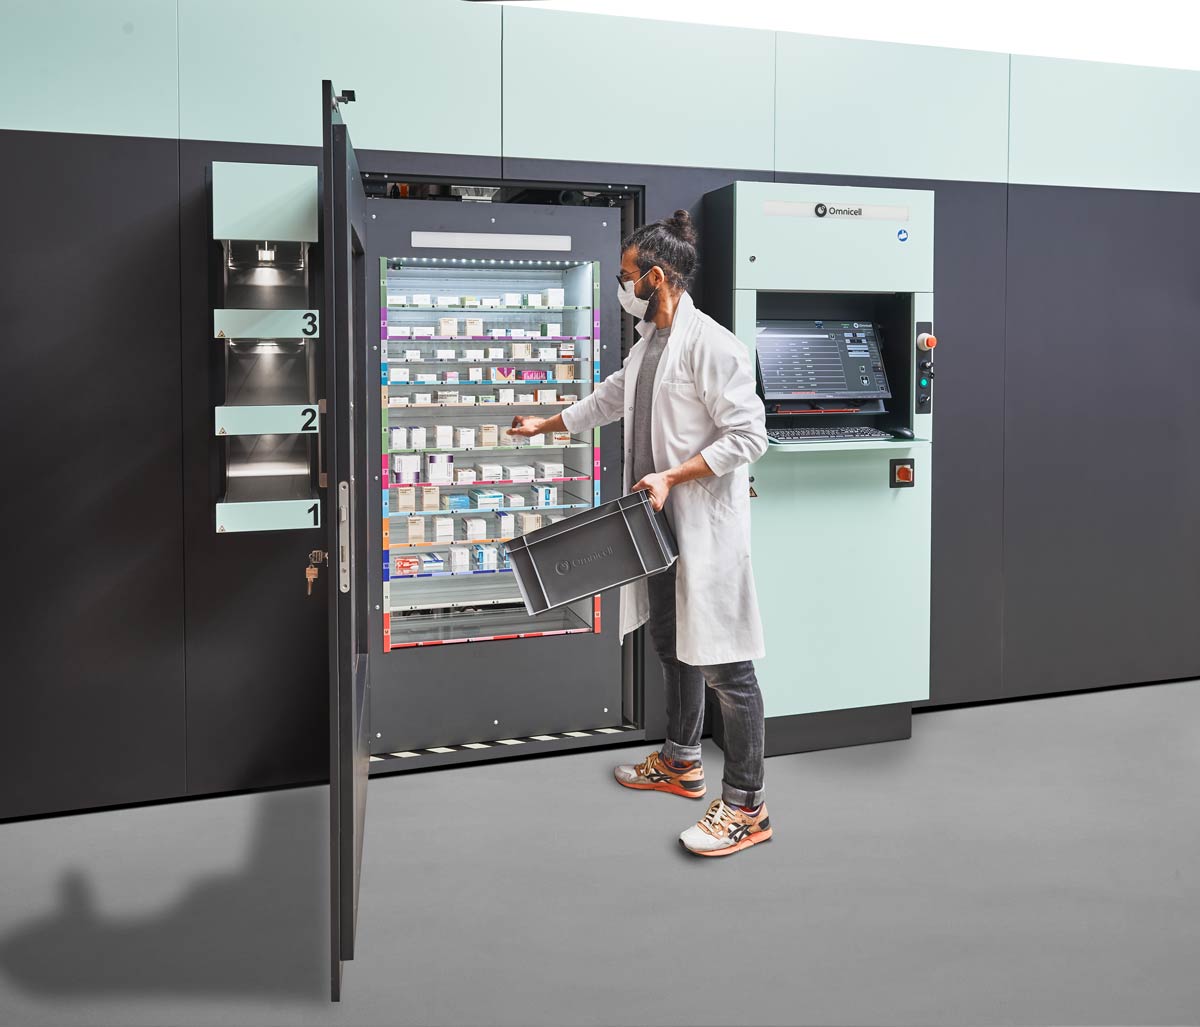
Omnicell’s financial narrative unfolds in two distinct layers: the verifiable data available through regulatory filings and the speculative estimates that fill the gaps. The company’s revenue streams—primarily hardware sales, software licenses, and service contracts—paint a picture of a business built on high-margin, low-volatility transactions. Unlike pharmaceutical firms exposed to R&D risks, Omnicell’s model thrives on predictable demand: hospitals will always need automated medication systems, regardless of economic cycles. This stability is both its strength and the reason its Omnicell net worth is rarely dissected in financial media. The challenge lies in translating these revenue streams into a net worth figure. Private companies don’t disclose profit margins or asset valuations, forcing analysts to rely on comparable benchmarks from similar healthcare tech firms. Omnicell’s closest public peers—companies like Cerner or Epic Systems—suggest that a firm of its scale could command a valuation in the $500 million to $1 billion range, but Omnicell’s private ownership structure means even these estimates are educated guesses. The company’s acquisition of smaller competitors (like its 2019 purchase of Parata Systems) further complicates the picture, as these deals are rarely disclosed with financial details.The Verified Baseline
Omnicell’s most concrete financial disclosures come from its FDA registrations and state-level healthcare contracts, which occasionally surface in public records. For instance, a 2022 procurement filing in California revealed a $12 million contract for automated dispensing systems at a single hospital network—a figure that, when multiplied across its global client base, underscores the scale of its operations. The company’s 2023 revenue has been reported by industry publications to exceed $300 million annually, though exact numbers are never confirmed. Beyond revenue, Omnicell’s patent portfolio offers another window into its valuation. The company holds over 100 patents related to medication automation, including key technologies for real-time inventory tracking and compliance monitoring. While patents alone don’t determine net worth, they do signal a moat against competitors—a critical factor in private company valuations. Omnicell’s refusal to license these patents externally suggests it views them as strategic assets rather than revenue generators, further embedding its Omnicell net worth in long-term operational value.What the Estimates Suggest
Industry analysts who specialize in healthcare technology often place Omnicell’s enterprise valuation in the $700 million to $1.2 billion range, though these figures are based on multiples applied to revenue rather than audited financials. The lower end of this spectrum assumes a conservative profit margin (around 20%), while the higher end accounts for its untapped potential in AI-driven supply chain optimization. Private equity firms, which have shown interest in Omnicell in the past, would likely value the company at the upper end of this range, given its recurring revenue model and global expansion. The wild card in Omnicell’s Omnicell net worth equation is its software-as-a-service (SaaS) transition. Historically a hardware-centric business, the company has increasingly shifted toward subscription-based analytics platforms, which offer higher margins than one-time equipment sales. If this pivot gains traction, some analysts speculate its valuation could double within five years, assuming it achieves $500 million in annual revenue—a target it’s on track to hit by 2026. However, this remains speculative, as Omnicell has not disclosed a clear roadmap for its software division.
Case Study: A Closer Look
Few deals illustrate Omnicell’s financial strategy better than its 2019 acquisition of Parata Systems, a smaller player in automated medication dispensing. The acquisition was widely reported to cost tens of millions, though exact figures were never released. What’s clear is that Parata’s specialized software for high-risk medications (like opioids) aligned perfectly with Omnicell’s push into compliance-driven healthcare solutions. The move didn’t just expand its product line—it locked in additional revenue streams from hospitals upgrading their systems to meet stricter regulatory demands. The impact of this acquisition can be measured in two key areas: customer retention and technological differentiation. Omnicell’s existing clients, now able to access Parata’s real-time overdose prevention tools, became more sticky—reducing churn and increasing the lifetime value of each installation. Meanwhile, the integration of Parata’s algorithms into Omnicell’s core systems created a competitive moat, making it harder for rivals like Arxium or Pyxis to replicate its offerings. This case study underscores how Omnicell’s Omnicell net worth isn’t just about top-line growth, but about strategic acquisitions that compound its market position."Omnicell doesn’t just sell machines—it sells peace of mind. Hospitals pay for reliability, not just features, and that’s why its contracts are worth more than the hardware alone." — Healthcare IT analyst, 2023
| Factor | Estimated Impact on Valuation |
|---|---|
| Recurring SaaS Revenue | Could add $200M–$400M to enterprise value if scaled aggressively. |
| Patent Portfolio | Provides defensive moat; industry estimates suggest $100M–$200M in intangible value. |
| Global Hospital Contracts | Multi-year deals with top 50 U.S. hospitals may represent $1B+ in total contract value (TCV). |
| AI/Analytics Expansion | Untapped potential; could double valuation if monetized effectively. |
| Private Ownership | Lack of public scrutiny may understate true worth by 30–50% compared to public peers. |
What This Means Going Forward
Omnicell’s financial trajectory hinges on two competing forces: its ability to monetize data and the pace of healthcare automation adoption. The company’s Omnicell net worth will likely grow if it successfully transitions from hardware sales to data-driven services, but this requires convincing hospitals to pay premiums for analytics they’ve historically treated as a secondary benefit. The alternative—staying a pure-play equipment vendor—risks stagnation as competitors like Amazon’s healthcare division enter the supply chain space with lower-margin but high-volume solutions. The bigger risk isn’t competition, but regulatory shifts. If new laws mandate interoperability standards for medication systems, Omnicell’s proprietary platforms could face pressure to open their APIs—or even lose market share to open-source alternatives. This would directly impact its Omnicell net worth by reducing the exclusivity of its contracts. However, Omnicell’s deep relationships with C-suite hospital executives (many of whom have used its systems for decades) suggest it’s well-positioned to lobby against disruptive regulations, ensuring its financial model remains intact.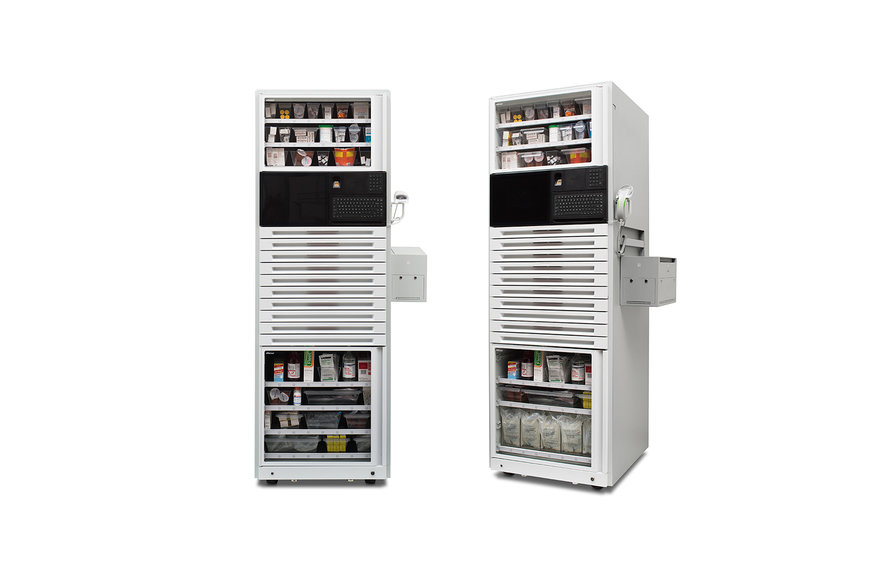
Conclusion
Omnicell’s story is one of quiet dominance—a company that has spent years building an invisible empire within healthcare infrastructure. Its Omnicell net worth may never be publicly confirmed, but the evidence points to a business that has mastered the art of recurring revenue in a capital-intensive industry. The lack of a public valuation isn’t a weakness; it’s a feature, allowing Omnicell to avoid the short-termism that plagues many tech firms. For investors, the real question isn’t what its net worth is, but how much higher it could climb if it fully leverages its data assets. The healthcare automation sector is entering a golden age of consolidation, and Omnicell is perfectly positioned to be a consolidator—or the next acquisition target for a larger player like UnitedHealth or Roche. Either path would see its Omnicell net worth surge, but the company’s current strategy suggests it prefers organic growth over a forced sale. In an era where data is the new oil, Omnicell’s true wealth may lie not in its balance sheet, but in the terabytes of medication distribution data it controls—a figure no financial statement can capture.Comprehensive FAQs
Q: Is Omnicell profitable, and how does that affect its net worth?
Omnicell is reportedly profitable, with industry estimates suggesting net margins in the 15–25% range due to its high-margin software and service contracts. Profitability directly influences its Omnicell net worth by improving its ability to reinvest in R&D and acquisitions, but private companies like Omnicell rarely disclose exact earnings. Analysts use EBITDA multiples (typically 8–12x for healthcare tech) to estimate its valuation, but these remain speculative without audited financials.
Q: Has Omnicell ever been acquired, or is it likely to be sold?
Omnicell has not been acquired and shows no signs of seeking a sale, though it has explored private equity partnerships in the past. Its private ownership structure allows it to avoid shareholder pressure, making an acquisition less likely unless a strategic buyer (e.g., a large hospital network or pharma company) offers a premium valuation—possibly $1.5B or more—for its technology and customer base. Rumors of a potential sale often resurface when healthcare tech consolidation heats up, but Omnicell’s leadership has consistently signaled a long-term growth strategy.
Q: How does Omnicell’s valuation compare to public healthcare tech firms?
Omnicell’s estimated enterprise value ($700M–$1.2B) would place it below publicly traded peers like Cerner ($20B+ market cap) or Epic Systems (reportedly valued at $6B+ privately), but its profitability per employee and customer concentration suggest it could rival niche players in the $1B–$2B range if it went public. The key difference is Omnicell’s focus on automation hardware/software, whereas larger firms derive revenue from EHR systems, lab services, or insurance, making direct comparisons difficult. Its private status also means it avoids the dilution risks that plague public companies, potentially allowing its Omnicell net worth to grow at a steadier clip.
Q: What’s the biggest threat to Omnicell’s financial growth?
The biggest existential threat isn’t competition from traditional rivals like Arxium or Pyxis, but disruptive innovation—specifically, AI-driven supply chain platforms that could make Omnicell’s hardware obsolete. If a tech giant (e.g., Google Health, Amazon) enters the space with lower-cost, cloud-based alternatives, Omnicell’s Omnicell net worth could stagnate unless it pivots aggressively to software and data services. Another risk is regulatory overreach: if new laws force Omnicell to open its systems to third-party integrations, it could lose control over its recurring revenue model, directly impacting its valuation. However, its decades-long customer relationships remain its strongest defense against these threats.
Q: Could Omnicell go public in the next 5 years?
A public offering isn’t impossible, but it’s not a priority for Omnicell’s current leadership. The company has no urgent need for capital and would likely face valuation pressures if it listed at its current size. If it does pursue an IPO, the optimal window would be after its SaaS revenue hits $100M+ annually, which could happen by 2026–2027. A public listing would also expose its Omnicell net worth to market speculation, which its private owners may prefer to avoid. That said, private equity firms have shown interest in healthcare automation, so a strategic sale to a larger player remains a more plausible exit than an IPO in the near term.
