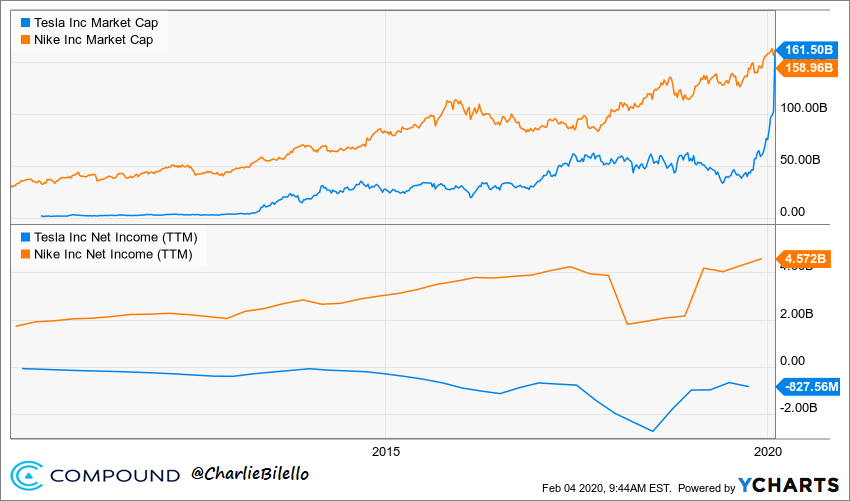
Breaking Down the Numbers
The Nike market cap 2024 sits at a crossroads where financial discipline meets brand mystique. As of mid-year, the company’s valuation hovered around $200 billion, a figure that underscores its position as the world’s most valuable sportswear brand—but one that’s increasingly scrutinized for how it balances growth with sustainability. Unlike tech giants that scale through user acquisition, Nike’s growth relies on premium pricing, limited-edition drops, and global retail partnerships. This model has kept its margins robust, but it also makes the brand vulnerable to economic downturns where discretionary spending tightens. What’s less discussed is how Nike’s valuation now reflects two distinct business models: its traditional wholesale operations (where margins are thinner) and its booming DTC segment (where margins exceed 50%). The shift toward DTC—accelerated by the pandemic—has been a key driver of its market cap resilience. Yet this strategy isn’t without trade-offs: over-reliance on digital sales exposes Nike to cybersecurity risks, and its supply chain bottlenecks (notably in Southeast Asia) have led to delayed restocks, eroding goodwill among hardcore collectors.The Verified Baseline
Public filings and earnings calls provide a clear starting point. Nike’s fiscal 2024 first-quarter report (released in May) showed revenue of $12.8 billion, up 11% year-over-year, with net income of $1.3 billion. While these figures are strong, they mask regional disparities: North America and Europe grew, but Greater China saw a 3% decline, a red flag for a brand that’s long relied on Asian demand. The company’s free cash flow—a critical metric for investors—remained healthy at $2.1 billion, but this was partly offset by $1.8 billion in capital expenditures, much of it tied to automation in factories and digital infrastructure. One verifiable outlier is Nike’s brand valuation, independently assessed by firms like Interbrand. In 2023, Nike was valued at $35 billion, but this figure doesn’t translate directly to market cap. The gap highlights how Nike’s intangible assets—its swoosh logo, heritage, and cultural cachet—are now as valuable as its physical inventory. This disconnect is why analysts argue that Nike’s true market cap 2024 should account for its unlisted IP portfolio, which includes licensing deals worth billions annually.What the Estimates Suggest
Industry estimates for Nike’s market cap 2024 vary widely, depending on assumptions about macroeconomic trends. Conservative forecasts (from firms like Goldman Sachs) suggest a valuation between $180 billion and $210 billion, factoring in potential slowdowns in China and rising labor costs. More bullish projections, however, point to $250 billion or higher if Nike successfully pivots to AI-driven personalization in its app and expands its Nike House retail concept globally. A lesser-discussed variable is the impact of resale markets. Sites like StockX and GOAT now account for 20-30% of Nike’s secondary revenue, a figure that’s hard to quantify but erodes primary sales margins. Some estimates suggest this could shave 3-5% off Nike’s gross margins by 2025 if the gray market grows unchecked. Meanwhile, the rising cost of synthetic materials (used in its Flyknit lines) has added upward pressure on production costs, though Nike has offset this with vertical integration—owning more of its supply chain than ever before.
Case Study: A Closer Look
Few decisions in recent years have tested Nike’s market cap resilience like its 2023 supply chain overhaul. After factory fires in Vietnam and labor strikes in Indonesia, Nike accelerated its "Made to Order" program, shifting production closer to demand centers. The move was risky: it increased per-unit costs by 10-15% in some cases, but it also reduced waste and improved delivery times. By mid-2024, this strategy had paid off, with on-time delivery rates exceeding 90%—a critical metric for maintaining its Just Do It brand equity. The trade-off? Nike’s gross margins dipped slightly in Q1 2024, but the long-term play is clear: reducing reliance on overseas manufacturing aligns with its sustainability goals (net-zero by 2050) and insulates it from geopolitical disruptions. This case study reveals a broader truth about Nike’s market cap 2024: its valuation isn’t just about quarterly earnings but about strategic bets on agility."Nike’s supply chain isn’t just about shoes—it’s about controlling the narrative. If they can’t deliver, the story becomes about scarcity, not exclusivity." — Retail analyst at Bernstein Research
| Factor | Estimated Impact on Market Cap (2024) |
|---|---|
| China consumer slowdown | Potential $5–10 billion drag if growth stalls further |
| DTC margin expansion | Could add $15–20 billion if scaling continues |
| Resale market erosion | Marginal $3–7 billion headwind if unchecked |
| AI-driven personalization | Upside of $10–15 billion if adopted widely |
| Supply chain automation | Cost savings of $2–4 billion annually by 2025 |
What This Means Going Forward
The Nike market cap 2024 isn’t just a number—it’s a report card on capitalism’s intersection with culture. As brands like Adidas and Lululemon chase Nike’s dominance, the key differentiator remains its ability to reinvent itself without diluting its core. The challenge ahead is balancing profitability with purpose: investors reward Nike’s financial discipline, but its most loyal customers demand social responsibility. This tension will define its valuation in the coming years. One wildcard is generational shift. Gen Z’s spending habits—prioritizing experiences over products—could force Nike to rethink its business model. If the sneaker resale market continues to grow, Nike may need to embrace secondary sales or risk losing relevance. Meanwhile, its betting on esports and gaming (via partnerships with Riot Games and the NBA) could unlock new revenue streams, but these remain long-term plays that won’t move the needle on market cap until 2025 or later.
Conclusion
Nike’s market cap in 2024 is a study in contradictions: a brand that’s both a global monolith and a nimble underdog, a company that thrives on scarcity while grappling with oversaturation. Its valuation isn’t just about sneakers—it’s about owning the future of movement, whether that’s through running shoes, digital avatars, or sustainable materials. The numbers tell one story; the culture tells another. And for now, the two are still aligned. Yet the writing isn’t set in stone. If macroeconomic headwinds intensify, or if Gen Z’s priorities shift further away from traditional retail, Nike’s market cap could face its first real test in a decade. The brand’s playbook has always been to anticipate disruption, not react to it. Whether that playbook holds in 2024 will determine if Nike remains the undisputed king of sport—or just another legacy brand playing catch-up.Comprehensive FAQs
Q: How does Nike’s market cap compare to Adidas and Under Armour?
As of mid-2024, Nike’s market cap (~$200 billion) dwarfs Adidas (~$40 billion) and Under Armour (~$4 billion). The gap reflects Nike’s global dominance in athletic footwear, stronger brand loyalty, and higher margins—though Adidas has been gaining ground in sustainable materials and European markets.
Q: Will Nike’s market cap grow if it enters the metaverse?
Potentially, but indirectly. Nike’s virtual sneaker drops (e.g., with Roblox and Fortnite) are more about brand engagement than revenue. Analysts estimate metaverse-related income could add $1–3 billion annually by 2027, but this won’t significantly move the needle on its $200 billion+ market cap unless it becomes a major profit driver—unlikely in the near term.
Q: How does inflation affect Nike’s market cap?
Inflation hits Nike in two ways: rising production costs (materials, labor) and consumer price sensitivity. While Nike has raised prices to offset costs, this risks alienating budget-conscious buyers. In 2024, inflation’s net impact on market cap is neutral to negative unless demand remains resilient in key regions like the U.S. and Europe.
Q: Could Nike’s market cap shrink if China’s economy worsens?
Yes. China accounts for ~20% of Nike’s revenue, and a prolonged slowdown could shave $10–20 billion off its market cap. However, Nike’s diversified supply chain (Vietnam, Indonesia, Mexico) and strong DTC sales in the West provide buffers. A China-specific downturn would hurt, but not derail the business.
Q: Is Nike’s market cap overvalued?
Valuation depends on perspective. By P/E ratio (30x), Nike is pricier than peers, but its brand moat and pricing power justify premium multiples. Some argue its $200 billion+ market cap is sustainable if it maintains 10%+ revenue growth and 40%+ margins—both achievable with its current strategy.
Q: How does Nike’s market cap relate to its stock price?
Market cap = stock price × outstanding shares. Nike’s ~750 million shares mean even small price movements (e.g., $100 → $110) can swing its $200 billion+ market cap by $7.5 billion. In 2024, its stock has been volatile due to China risks and interest rates, but long-term investors focus on dividend growth (currently ~0.5%) and buybacks.
Q: What’s the biggest threat to Nike’s market cap in 2024?
The resale market. While Nike benefits from secondary demand (via collaborations), the gray market erodes primary sales and margins. If resale platforms like StockX grow further, Nike may need to partner with them or risk losing control—a move that could pressure its market cap by $5–15 billion if not managed carefully.
Q: Can Nike’s market cap reach $300 billion?
Unlikely in the short term. Hitting $300 billion would require doubling its current valuation, which would need explosive growth (e.g., 20%+ revenue CAGR) or a merger/acquisition (unlikely given its independence). More plausible is a gradual climb to $250 billion by 2026 if its DTC and digital strategies pay off.
