The Short Answers
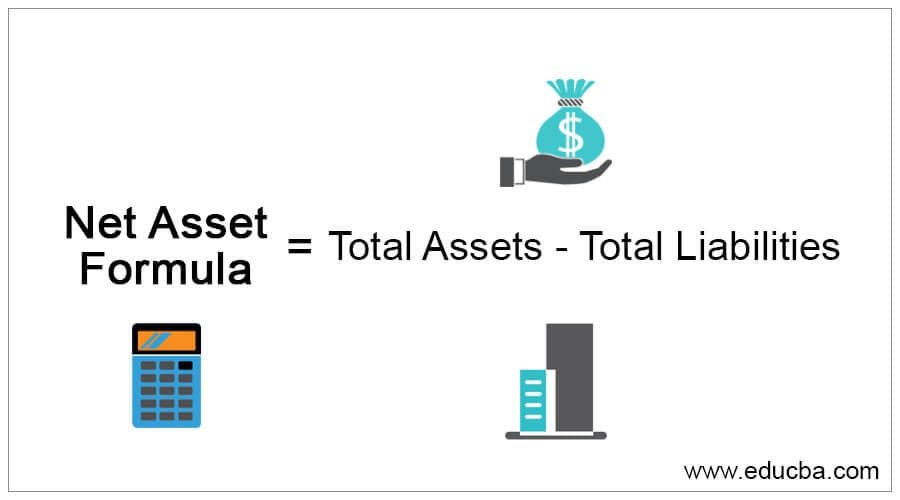
- Net worth is the broadest measure: total assets minus total liabilities, including intangibles like goodwill or unrecognized future income.
- Net assets focus on tangible, liquid, or immediately realizable assets—what remains after deducting all liabilities, including hidden or contingent ones.
- Corporate net asset value (NAV) is critical for investors in funds or REITs, as it reflects the true value of holdings after fees and debt.
- Personal net worth often overstates financial security by excluding illiquid assets or pending legal judgments.
- The gap between the two reveals leverage, off-balance-sheet risks, and the true cost of maintaining wealth.
Deep Dive: The Full Picture
The net asset vs net worth debate cuts to the heart of how value is perceived—whether in a multinational corporation’s annual report or a family’s private ledger. At its core, net worth is a snapshot: a momentary assessment of what you own versus what you owe. It’s the figure often cited in media profiles of billionaires or in personal finance advice, but it’s also the most malleable. A private jet listed at $50 million on a net worth statement might be worth $30 million in a forced sale, yet the discrepancy is rarely noted. Meanwhile, net assets strip away such distortions by zeroing in on what can realistically be converted to cash—after accounting for taxes, transaction costs, and market downturns.
The confusion arises because net worth is frequently used as a shorthand for financial success, while net assets demand a forensic approach. Take the case of a hedge fund: its net asset value (NAV) per share is calculated daily, but this figure assumes all assets can be sold at fair market value—a assumption that collapsed during the 2008 financial crisis when liquidity dried up. For individuals, the divide is equally stark. A doctor’s net worth might include a medical practice valued at $2 million, but the net assets figure could drop by 40% if patient receivables turn out to be uncollectible or malpractice claims emerge.
#### The Context You Need
The net asset vs net worth distinction becomes critical in three scenarios: 1. Investment decisions, where a fund’s NAV might differ wildly from its market price due to redemption pressures or illiquid holdings. 2. Mergers and acquisitions, where acquirers scrutinize net assets to uncover hidden liabilities (e.g., environmental cleanup costs or pending lawsuits). 3. Personal financial planning, where retirees must differentiate between paper wealth (e.g., a stock portfolio) and spendable assets (e.g., a cash reserve). Historically, the terms were nearly synonymous until the rise of complex financial instruments in the 1980s. Today, net worth is the vanity metric—easy to inflate with appreciating assets—while net assets is the stress-test figure, revealing how much you’d actually have in a crisis. The disconnect is most glaring in private equity, where buyout firms use net worth multiples to justify premiums, only for net assets to shrink post-acquisition due to integration costs. ####The Mechanics
Calculating net worth is straightforward: sum all assets (cash, investments, property, intellectual property) and subtract all liabilities (debt, taxes owed, legal judgments). The result is a static number, but its accuracy hinges on two variables: valuation methodology and what’s included. A family home might be valued at $1.5 million in a net worth statement, but its net asset contribution could be zero if it’s encumbered by a mortgage and local market conditions have soured. Net assets, by contrast, require a deeper dive. They exclude intangibles like goodwill or unproven patents and focus on: - Liquid assets (cash, marketable securities) - Realizable assets (property that can be sold without penalty) - Liabilities adjusted for recoverability (e.g., a loan where the borrower is creditworthy) The process mirrors how accountants prepare a statement of financial position, but with an emphasis on going-concern adjustments. For example, a luxury watch collection might appear as an asset on a net worth sheet, but its net asset value could be near zero if it’s tied to a vintage dealer’s inventory—and thus unsaleable at full price.Details That Change the Picture
The most overlooked factor in net asset vs net worth comparisons is off-balance-sheet risk. A corporation’s net worth might exclude contingent liabilities—such as guarantees on a subsidiary’s debt—until they materialize. Similarly, an individual’s net worth could ignore the cost of caring for an aging parent or the potential loss from a pending divorce settlement. These items don’t appear on standard financial statements but can erode net assets overnight.
Another critical variable is time horizon. A young professional’s net worth might surge with a rising stock market, but their net assets—if they’ve maxed out credit cards or taken on student loans—could remain stagnant. Conversely, a retiree’s net worth might include a pension valued at $1 million, but the net asset equivalent would account for inflation, longevity risk, and the pension fund’s solvency.
"Net worth is the number you brag about. Net assets are the number that keeps you up at night." — Financial advisor to ultra-high-net-worth families (anonymous)
| Metric | Key Difference |
|---|---|
| Net Worth | Includes all assets and liabilities, regardless of liquidity or realizability. |
| Net Assets | Focuses on assets that can be converted to cash after accounting for all liabilities, including hidden ones. |
| Corporate NAV | Used in funds to reflect per-share value after fees, expenses, and debt—but assumes liquidity. |
| Personal Net Worth | Often inflated by appreciating assets (e.g., art, real estate) that may not be saleable. |
| Net Asset Value (NAV) in Private Equity | Can drop sharply post-acquisition due to integration costs, even if the "net worth" multiple was high. |

Conclusion
The net asset vs net worth divide isn’t a technicality—it’s the difference between a polished financial narrative and the unvarnished truth. For investors, ignoring the gap can lead to overpaying for assets or underestimating risk. For individuals, conflating the two can result in overleveraging or poor retirement planning. The key is to treat net worth as a starting point and net assets as the reality check.
As financial systems grow more complex, the ability to distinguish between the two becomes non-negotiable. Whether you’re evaluating a startup’s pitch deck, your own investment portfolio, or a public company’s balance sheet, the question isn’t just how much is it worth?—it’s how much can you actually access, and at what cost?
Comprehensive FAQs
#### Q: Can my net worth ever be negative?
A: Yes. If your total liabilities exceed your total assets, your net worth is negative—a common scenario for highly leveraged individuals (e.g., those with significant student debt or business loans). However, net assets would likely be even lower, as they exclude intangible assets that might not cover liabilities in a forced liquidation.
####Q: Why do some companies report net asset value (NAV) separately from net worth?
A: Companies like mutual funds or REITs use NAV to reflect the per-share value of their underlying assets after deducting all expenses and liabilities. This is distinct from net worth, which might include goodwill or other non-liquid components. The separation ensures transparency for investors about the fund’s true liquidity.
####Q: Does including a home in net worth overstate my financial health?
A: Often, yes. While a home contributes to net worth, its net asset value depends on mortgage levels, local market conditions, and transaction costs. In a downturn, you might owe more on the mortgage than the home is worth, turning an asset into a liability in net asset terms.
####Q: How do private equity firms manipulate net asset vs net worth in acquisitions?
A: Firms may inflate net worth by including synergies or future revenue projections, while the actual net assets post-acquisition are eroded by integration costs, debt restructuring, or unrecognized liabilities. This is why acquirers often demand net asset audits before finalizing deals.
####Q: Can my net assets be higher than my net worth?
A: No, net assets are always equal to or lower than net worth, since they represent a subset of assets (those that are liquid or realizable) minus all liabilities. The only way net worth exceeds net assets is if your balance sheet includes non-realizable items (e.g., a collectible with no market).
####Q: How often should I recalculate my net assets vs net worth?
A: Net worth can be tracked annually or quarterly, especially if your asset mix is stable. Net assets, however, should be reassessed during major life events (e.g., inheritance, divorce, market downturns) or when liquidity needs arise (e.g., retirement planning). The goal is to ensure your net asset figure aligns with your actual spending capacity.
####Q: What’s the biggest red flag in a company’s net worth vs net asset discrepancy?
A: A large gap between the two often signals off-balance-sheet liabilities, aggressive asset valuation, or excessive leverage. For example, if a company’s net worth includes a "strategic asset" valued at $500 million but its net assets show only $100 million in liquid reserves, it’s a sign of potential overvaluation or hidden risk.
####Q: How do I protect my net assets from legal or financial shocks?
A: Diversify liquid assets, maintain an emergency fund equal to 12–24 months of expenses, and structure liabilities (e.g., mortgages, loans) to minimize exposure to single points of failure. For high-net-worth individuals, asset protection trusts or limited liability entities can shield net assets from creditors or lawsuits.
