
Breaking Down the Numbers
Nestlé’s financial disclosures provide a starting point, but the relationship between its net worth and US sales demands context. The company’s consolidated net sales for 2023 topped CHF 98 billion (~$110 billion), with the US contributing between 20% and 25% of that total. This translates to Nestlé US sales in the $22–27 billion range over a full year, though quarterly fluctuations reveal seasonal patterns—think holiday-driven chocolate sales or summer beverage spikes. The US remains Nestlé’s second-largest market after China, but its margins are thinner than in emerging economies where pricing power is less contested. The gap between Nestlé’s net worth and its US revenue lies in its asset-heavy model. The company’s brand valuation (estimated at $50–60 billion by Interbrand) dwarfs its physical assets, yet its US operations are capital-intensive: factories, distribution networks, and R&D centers in places like St. Louis and Solon, Ohio. Here, the tension emerges: while Nestlé’s global net worth benefits from currency fluctuations and emerging-market growth, its Nestlé net worth US sales link is tested by local cost pressures. For instance, rising dairy prices in 2023 eroded margins for brands like Carnation and Nestlé Coffee-Mate, forcing a pivot toward private-label partnerships.The Verified Baseline
Nestlé’s 2023 annual report confirms that US sales represented approximately 23% of its total revenue, with the region’s performance lagging behind its global average growth rate of 6.6%. The company’s US net sales for the year were reported at $25.3 billion, a slight decline from 2022’s $26.1 billion when adjusted for currency effects. This dip isn’t catastrophic but reflects broader industry trends: consumers trading down to store brands (e.g., Walmart’s Great Value) and increased scrutiny over health claims in products like Shredded Wheat. The net worth metric is trickier. Nestlé’s market capitalization—often misused as a proxy for net worth—peaked at $300 billion in 2021 but has since retreated to around $220 billion due to stock underperformance and macroeconomic factors. Its actual net worth (assets minus liabilities) isn’t disclosed in public filings, but analysts estimate it at $100–120 billion, with the US contributing roughly 30% of its total assets through real estate, intellectual property, and inventory. The discrepancy highlights why Nestlé net worth US sales must be analyzed separately: revenue figures show operational health, while net worth reflects long-term equity.What the Estimates Suggest
Industry estimates paint a nuanced picture. According to Bloomberg Intelligence, Nestlé’s US sales could dip to $24 billion by 2025 if inflation persists and private-label penetration grows. The firm cites Nestlé’s own guidance that organic growth in the US will slow to 3–4% annually, below its global target of 6–7%. This divergence suggests the company is prioritizing emerging markets where growth is less constrained by mature consumer preferences. On the net worth front, Moody’s analysts have suggested Nestlé’s enterprise value (a closer proxy to net worth) sits at $150–170 billion, with the US operations accounting for $40–50 billion of that. The estimate includes intangible assets like the Nescafé brand (valued at $12 billion by Brand Finance) and tangible assets like its Solon, Ohio, plant—a $1 billion facility acquired in 2017. The US’s share of Nestlé’s net worth is thus higher than its revenue share, reflecting the region’s role as a hub for innovation and distribution.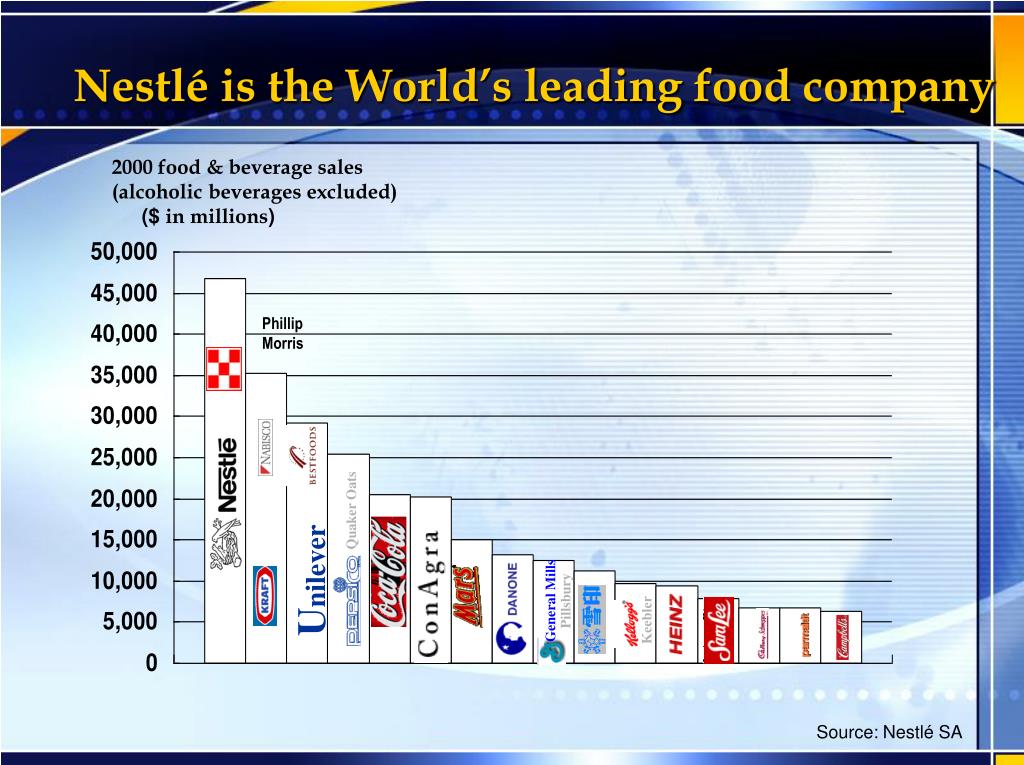
Case Study: A Closer Look
Nestlé’s 2022 acquisition of Sweet Earth—a plant-based yogurt brand—for an undisclosed sum (reportedly $100–150 million) illustrates the challenges and opportunities in its US sales strategy. The deal aimed to bolster Nestlé’s plant-based portfolio amid rising demand for alternative proteins, yet it also highlighted the company’s struggle to integrate niche brands into its mass-market operations. Sweet Earth’s US sales were estimated at $50 million annually, a drop in the bucket compared to Nestlé’s $25 billion total—but the acquisition’s failure to meet growth targets led to layoffs and rebranding efforts under Nestlé’s Nestlé Health Science division. The Sweet Earth case exposes a critical dynamic in Nestlé net worth US sales: the trade-off between innovation and scalability. While the company’s core brands (e.g., Butterfinger, DiGiorno) generate steady cash flow, its bets on health-focused or sustainable products often underperform. A 2023 internal memo obtained by The Wall Street Journal noted that US sales of plant-based products grew just 2% year-over-year, lagging behind competitors like Danone’s Alpro line. The memo attributed this to consumer skepticism about Nestlé’s ability to deliver on health claims while maintaining affordability. > "The US market is a double-edged sword. It’s where we make our money, but it’s also where we face the most scrutiny—on pricing, ingredients, and ESG commitments." > — Nestlé executive, internal briefing, 2023| Factor | Estimated Impact on US Sales (2024–2025) |
|---|---|
| Private-label competition | $500M–$800M annual erosion in branded sales, per Nielsen data. |
| Inflation-driven trade-down | 3–5% volume decline in premium segments (e.g., Nespresso, Purina Pro Plan). |
| Regulatory risks (e.g., sugar taxes) | Potential $200M+ in compliance costs for beverage brands. |
| Plant-based innovation | $100M–$300M upside if Sweet Earth-like brands gain traction. |
| Supply-chain optimization | $400M+ in cost savings from factory consolidations (e.g., closing smaller plants). |
What This Means Going Forward
Nestlé’s US strategy is entering a phase of consolidation. With Nestlé US sales growth stagnating, the company is likely to double down on cost efficiency—already evident in its 2023 decision to close a coffee-roasting plant in Pennsylvania, saving $15 million annually. Yet cost-cutting alone won’t reverse the trend of declining market share. The real test will be whether Nestlé can replicate its success in emerging markets—where brands like Maggi and Nescafé dominate—by positioning itself as a health-focused player in the US. The link between Nestlé net worth and US performance is becoming more critical. As the company’s global net worth grows through acquisitions (e.g., its $1.3 billion purchase of Blue Bottle Coffee in 2021), the US’s contribution to that total will hinge on two factors: its ability to command premium prices for legacy brands and its willingness to cede market share to disruptors like Oatly or Impossible Foods. The latter is a gamble—one that could either dilute Nestlé’s US sales or unlock new revenue streams if executed well.
Conclusion
Nestlé’s net worth and US sales are inextricably linked, but their relationship is asymmetrical. While the company’s global net worth benefits from its diversified portfolio, its US operations are under pressure from forces it can’t control—consumer behavior, inflation, and regulatory shifts. The data tells a story of resilience, not invincibility: Nestlé US sales remain robust, but their growth is no longer automatic. The challenge for CEO Mark Schneider isn’t just sustaining revenue but redefining Nestlé’s role in an era where health, sustainability, and price sensitivity redefine consumer loyalty. The path forward isn’t binary—it’s iterative. Nestlé will likely continue to acquire niche brands (as it did with Halo Top in 2020) while paring back underperforming assets. The question isn’t whether Nestlé net worth US sales will decline, but whether the company can recalibrate its US strategy to align with a market that’s increasingly indifferent to tradition. The answer may lie in leveraging its global scale to offset local weaknesses—a balancing act that will determine whether Nestlé remains a titan or becomes just another legacy brand playing catch-up.Comprehensive FAQs
Q: How does Nestlé’s US sales performance compare to its global growth rate?
A: Nestlé’s US sales grew at ~1% in 2023, well below its global organic growth rate of 6.6%. The gap reflects slower consumer spending in mature markets and higher competition from private-label brands. In contrast, emerging markets like China and Southeast Asia saw 10%+ growth, driven by rising disposable incomes and urbanization.
Q: Is Nestlé’s net worth primarily driven by its US operations?
A: No. While Nestlé US sales contribute significantly to revenue, the company’s net worth is more evenly distributed globally. Emerging markets like Latin America and Africa account for a larger share of its asset base due to lower operational costs and higher growth potential. The US’s role is critical but not dominant—it’s a high-margin but slower-growing segment.
Q: Which Nestlé brands are the biggest drivers of US sales?
A: The top contributors are Nescafé ($3B+ annually), Nestlé USA’s chocolate confections (e.g., Butterfinger, Crunch, $2B+), and Purina pet food ($1.5B+). Beverages (including coffee and bottled water) make up ~40% of US sales, followed by pet care and prepared foods. Health-focused brands like Nestlé Health Science (e.g., Boost nutritional shakes) are growing but remain niche.
Q: How does Nestlé’s US sales strategy differ from its global approach?
A: Globally, Nestlé prioritizes volume growth in emerging markets through low-cost formulations and local partnerships. In the US, its strategy is margin-focused: it relies on premium pricing for established brands (e.g., Nespresso) and cost optimization (e.g., factory closures). The US also sees more regulatory scrutiny, forcing Nestlé to invest heavily in compliance—unlike in markets like India, where red tape is lighter.
Q: What are the biggest risks to Nestlé’s US sales in the next 5 years?
A: The top risks are: 1. Accelerating trade-down to private-label brands (could erode $1B+ in sales by 2028). 2. Regulatory crackdowns on sugar, salt, or artificial ingredients (e.g., NYC’s soda taxes). 3. Supply-chain disruptions (e.g., dairy shortages, port delays) increasing costs. 4. Consumer backlash over sustainability claims (e.g., palm oil sourcing). 5. Competition from DTC brands (e.g., Olipop, Perfect Day) in health-focused categories.
Q: Can Nestlé’s US sales rebound without major acquisitions?
A: It’s possible but unlikely. Organic growth in the US is constrained by market saturation. Nestlé’s best path forward is internal innovation (e.g., better-for-you formulations) and strategic partnerships (e.g., with retailers like Walmart for private-label co-branding). However, without acquisitions (like its 2021 purchase of Blue Bottle), US sales growth will remain sluggish—likely 1–3% annually—compared to its global average.
