Where It All Began
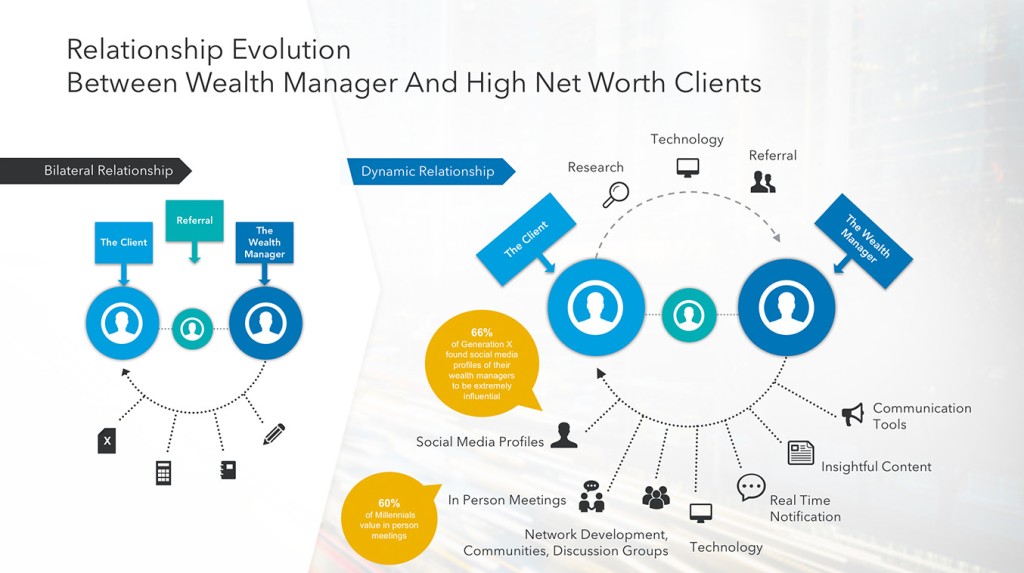
The first true "family office" emerged in 1936, when J. Paul Getty hired a team to manage his oil fortune after inheriting $500 million (equivalent to ~$10 billion today). But Getty’s operation was a luxury problem: a private secretary, a ledger, and a safe. It wasn’t until the 1970s—when tax laws in the U.S. and Europe forced ultra-wealthy families to professionalize their financial operations—that wealth management services for high-net-worth individuals became a distinct industry. The pioneers were often ex-bankers or accountants who realized that trust funds and static investments weren’t cutting it in a world where inflation and capital controls were becoming global tools. The early signs were subtle. In the 1980s, Swiss private banks began offering "discretionary management" accounts, where clients could delegate entire portfolios to a single advisor—no questions asked. This wasn’t just about returns; it was about deniability. A family in Geneva might instruct their bank to "diversify" a portfolio into gold, art, and offshore bonds without ever seeing the trades. The bank’s job wasn’t to explain; it was to execute. By the late 1990s, the first "multi-family offices" appeared, pooling resources for groups of HNWIs who couldn’t justify the cost of a single-family setup. These were the seeds of what would become today’s scalable ultra-wealth solutions.The Early Signs
The real inflection point arrived with the 2008 financial crisis. Overnight, the idea that a diversified portfolio could protect against systemic collapse was exposed as a myth. Families who had relied on traditional wealth management services for high-net-worth individuals found themselves locked out of liquidity, watching their "safe" assets plummet. The response? A scramble toward alternative assets—private equity, distressed debt, and even hard assets like farmland or timber, which were suddenly seen as "non-correlated" to market swings. What followed was a quiet revolution. The first single-family offices emerged in the early 2010s, often staffed by former hedge fund managers or ex-bankers who had grown frustrated with institutional constraints. These weren’t just investment vehicles; they were private corporations with CFOs, legal teams, and in-house compliance officers. The message was clear: if you’re worth billions, you don’t just need a portfolio—you need a governance structure. By 2015, the first AI-driven risk models appeared, allowing families to simulate everything from political coups to currency devaluations before making a move.The Turning Point
The shift from passive wealth preservation to active wealth architecture accelerated in 2017, when a single event changed everything: the introduction of MiFID II in Europe. The regulation forced wealth managers to disclose conflicts of interest, fee structures, and even the cost of advice—something HNWIs had long taken for granted. For the first time, ultra-wealthy clients had to audit their own advisors. The result? A mass exodus from traditional banks to independent wealth platforms, where transparency was a selling point, not a liability. The turning point wasn’t just regulatory—it was technological. The same year, a London-based family office became the first to integrate blockchain-based ledgers for tracking private asset ownership. No more spreadsheets. No more "lost" shares. Just an immutable record of who owned what, and where. The implication was staggering: if wealth could be tokenized, then so could control. By 2020, the first smart contracts for inheritance were being tested, where a trust could automatically distribute assets based on predefined conditions—no probate, no legal battles, just code as law."By 2025, the question isn’t whether you can afford wealth management—it’s whether your wealth management can keep up with you." — Head of Ultra-Wealth Strategy, Boston Consulting Group (2024)

The Build-Up, Year by Year
| Period | What Happened / What Changed |
|---|---|
| 2015–2018 | The rise of multi-asset class family offices, where private equity, real estate, and even venture capital were bundled under one roof. The first AI-driven portfolio rebalancing tools emerged, allowing for real-time adjustments based on macroeconomic data. |
| 2019–2021 | The pandemic effect: HNWIs accelerated demand for liquidity management tools, including private credit lines and pre-negotiated exit strategies for illiquid assets. The first climate-aligned investment funds appeared, catering to families who wanted to align wealth with ESG criteria without sacrificing returns. |
| 2022–2025 | The regulatory arms race: New laws in the U.S., EU, and Asia forced wealth managers to adopt dynamic compliance systems, where tax strategies could be adjusted in real time based on legislative changes. The first quantum-resistant encryption protocols were integrated into family office infrastructure, future-proofing against cyber threats. |
Lessons From the Journey
- Liquidity is no longer a given. In 2025, the ability to access capital—whether through private credit, pre-sold assets, or digital collateral—is the defining feature of elite wealth management.
- Privacy is the new currency. The families who thrive are those who operate in jurisdictional gray zones, where legal structures are designed to evade—not just taxes, but oversight.
- Technology is the trustee. AI now handles more than just portfolio allocation; it manages family governance, predicting conflicts before they arise and suggesting resolutions.
- Legacy planning is real-time. The old model—drafting a will and forgetting about it—is dead. In 2025, succession plans are living documents, updated with biometric verification and blockchain-backed directives.
- Compliance is a competitive advantage. The families who navigate regulatory shifts smoothly are the ones who treat lawyers and tax strategists as core team members, not afterthoughts.
- Wealth is no longer static. The most successful HNWIs in 2025 aren’t those with the largest portfolios, but those who can reinvent their wealth—shifting from cash to crypto, from real estate to intellectual property, and back again.
Where Things Stand Today
Wealth management services for high-net-worth individuals in 2025 operate on two parallel tracks. The first is visible: the high-profile family offices, the billion-dollar private equity deals, the yacht purchases that make headlines. The second is invisible—the quiet restructuring, the offshore entities being repurposed, the AI systems running simulations on "what if Scenario X happens tomorrow." The biggest change? Speed. A decade ago, moving $100 million required weeks of paperwork, legal reviews, and bank approvals. Today, with instant settlement systems and digital signatures, the same transfer can happen in hours—if the right protocols are in place. The families who benefit aren’t just the ones with the most money; they’re the ones who move fastest. But the real story is in the fragmentation. No single firm dominates wealth management for high-net-worth individuals anymore. Instead, there’s a marketplace of specialists: cybersecurity firms for digital assets, tax strategists for jurisdictional plays, and even privacy consultants who help families navigate the new surveillance economy. The days of the "one-stop shop" are over. In 2025, the ultra-wealthy don’t have advisors—they have networks.
Conclusion
The evolution of wealth management services for high-net-worth individuals over the past decade hasn’t been about getting richer—it’s been about staying richer. The families who will dominate in 2025 aren’t the ones with the best stock picks; they’re the ones who’ve built unhackable systems. Systems where money isn’t just an asset, but a strategic resource. Systems where every move—from a real estate purchase to a crypto stake—is part of a larger game. The question for any HNWI in 2025 isn’t whether they need wealth management. It’s whether their current approach is future-proof. And the answer, more often than not, is no.Comprehensive FAQs
Q: What’s the biggest difference between wealth management for HNWIs in 2025 and 2015?
The shift from static portfolios to dynamic, real-time wealth architectures. In 2015, HNWIs relied on diversified funds and periodic rebalancing. Today, wealth is managed through automated liquidity tools, jurisdictional arbitrage, and AI-driven scenario planning—where every asset is part of a larger strategy, not just a line item.
Q: Are family offices still relevant, or have they been replaced by digital platforms?
Family offices haven’t disappeared—they’ve evolved. The old model (a team managing a single family’s wealth) is being replaced by hybrid structures: some families use AI-driven platforms for day-to-day management while keeping a human-led team for high-stakes decisions like succession or crisis response.
Q: How do HNWIs protect their wealth from cyber threats in 2025?
Through multi-layered security: quantum-resistant encryption for digital assets, air-gapped systems for sensitive data, and dedicated cybersecurity teams within family offices. The most advanced HNWIs also use decentralized identity solutions, where access to wealth isn’t tied to a single login but requires biometric + behavioral authentication.
Q: What’s the role of AI in wealth management for ultra-HNWIs today?
AI isn’t just for portfolio optimization anymore. In 2025, it handles family governance (predicting conflicts), tax strategy (simulating regulatory changes), and even legacy planning (automating trust distributions). The most sophisticated systems can simulate geopolitical shocks in real time, suggesting asset shifts before markets react.
Q: How do HNWIs navigate the new regulatory landscape (e.g., FATF, CRS, ESG reporting)?
By treating compliance as a competitive advantage. The best wealth managers in 2025 use dynamic compliance systems—AI that monitors regulatory changes globally and adjusts structures in real time. Some families operate parallel legal entities in different jurisdictions, ensuring that no single regulator can freeze or seize their wealth.
Q: What’s the biggest misconception about wealth management for HNWIs in 2025?
That it’s still about returns. The ultra-wealthy in 2025 care more about control, privacy, and liquidity than benchmark-beating portfolios. A family might sacrifice 1% in returns if it means instant access to capital or impenetrable privacy. The game isn’t about growing wealth—it’s about preserving autonomy.
