The Short Answers
- The average upper middle class retirement income in Canada ranges from $80,000 to $150,000 annually, depending on province and lifestyle.
- Ontario and BC retirees face higher tax burdens due to healthcare premiums and property taxes, while Alberta and Saskatchewan offer lower costs but less robust social services.
- Maximizing CPP at 70 and deferring OAS can boost monthly income by up to 42% for CPP and 36% for OAS—critical for those with substantial savings.
- Withdrawing from TFSAs first (before RRIFs) can defer taxable income, but RRIF rules require mandatory withdrawals starting at age 71.
- Geographic arbitrage—retiring in a lower-tax province or near family for care support—is a key lever for this demographic.
Deep Dive: The Full Picture
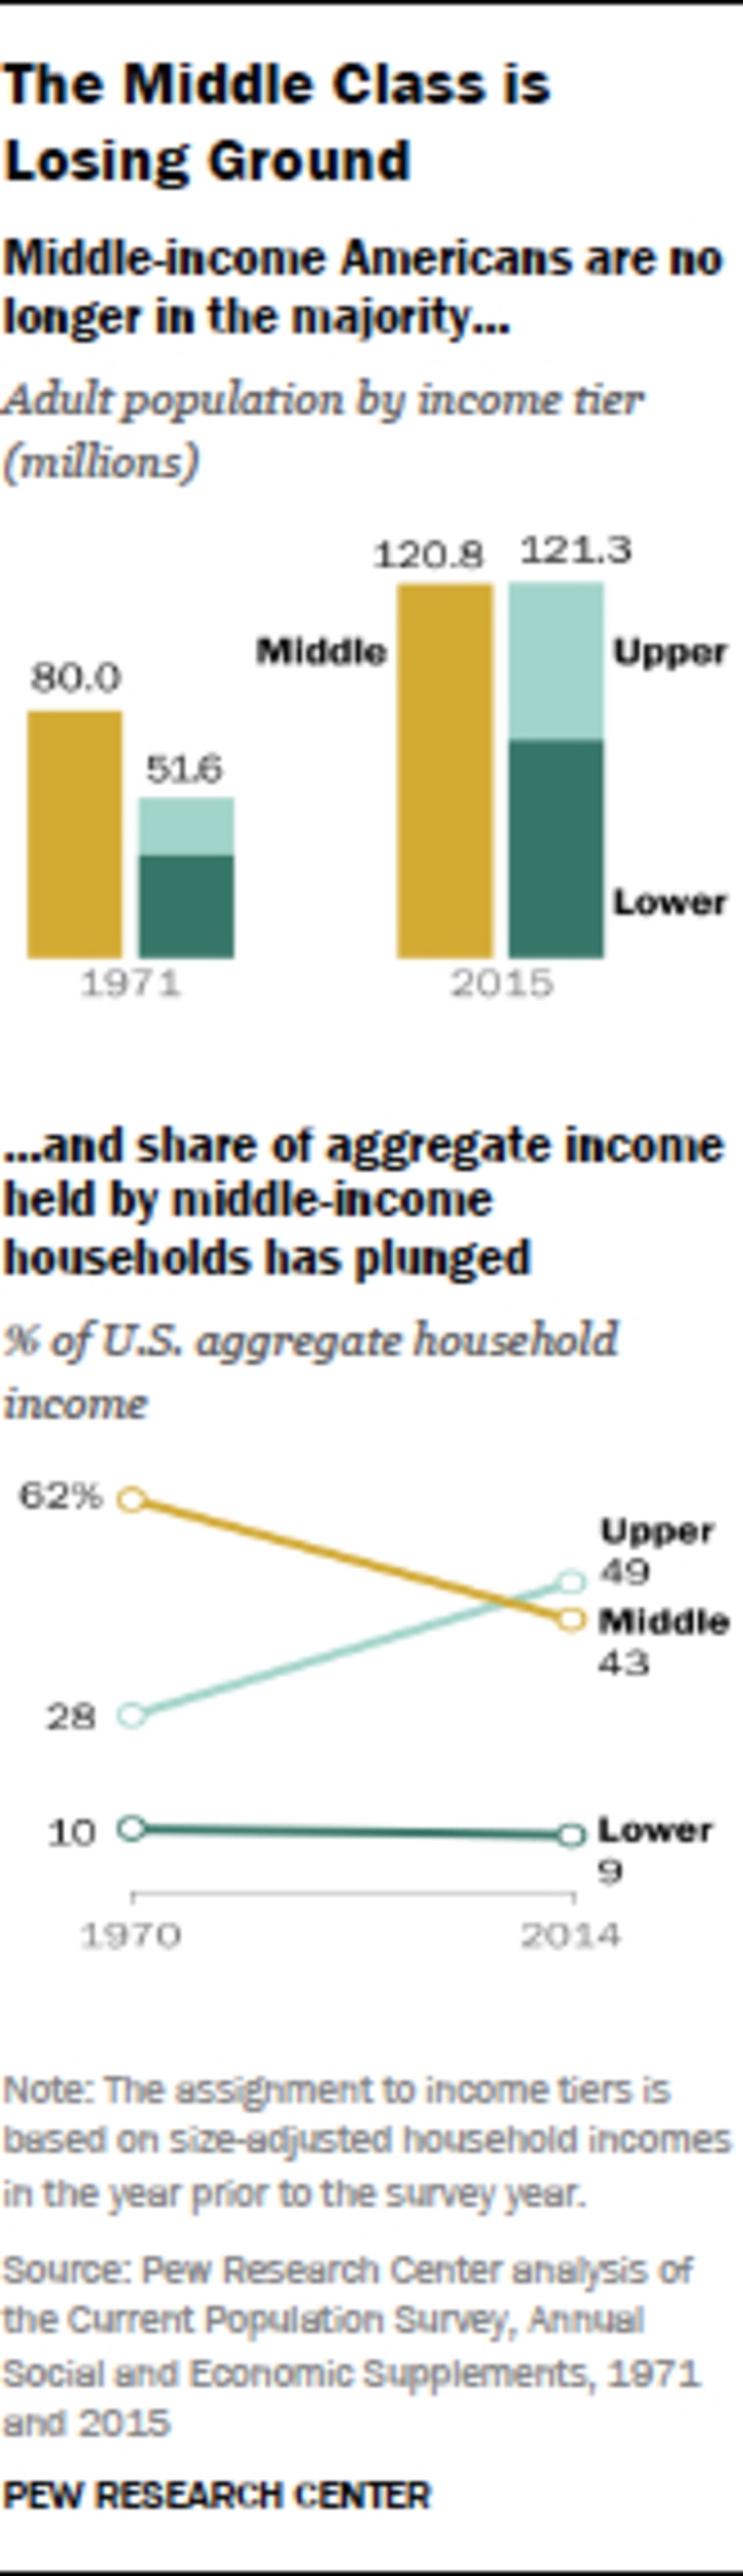
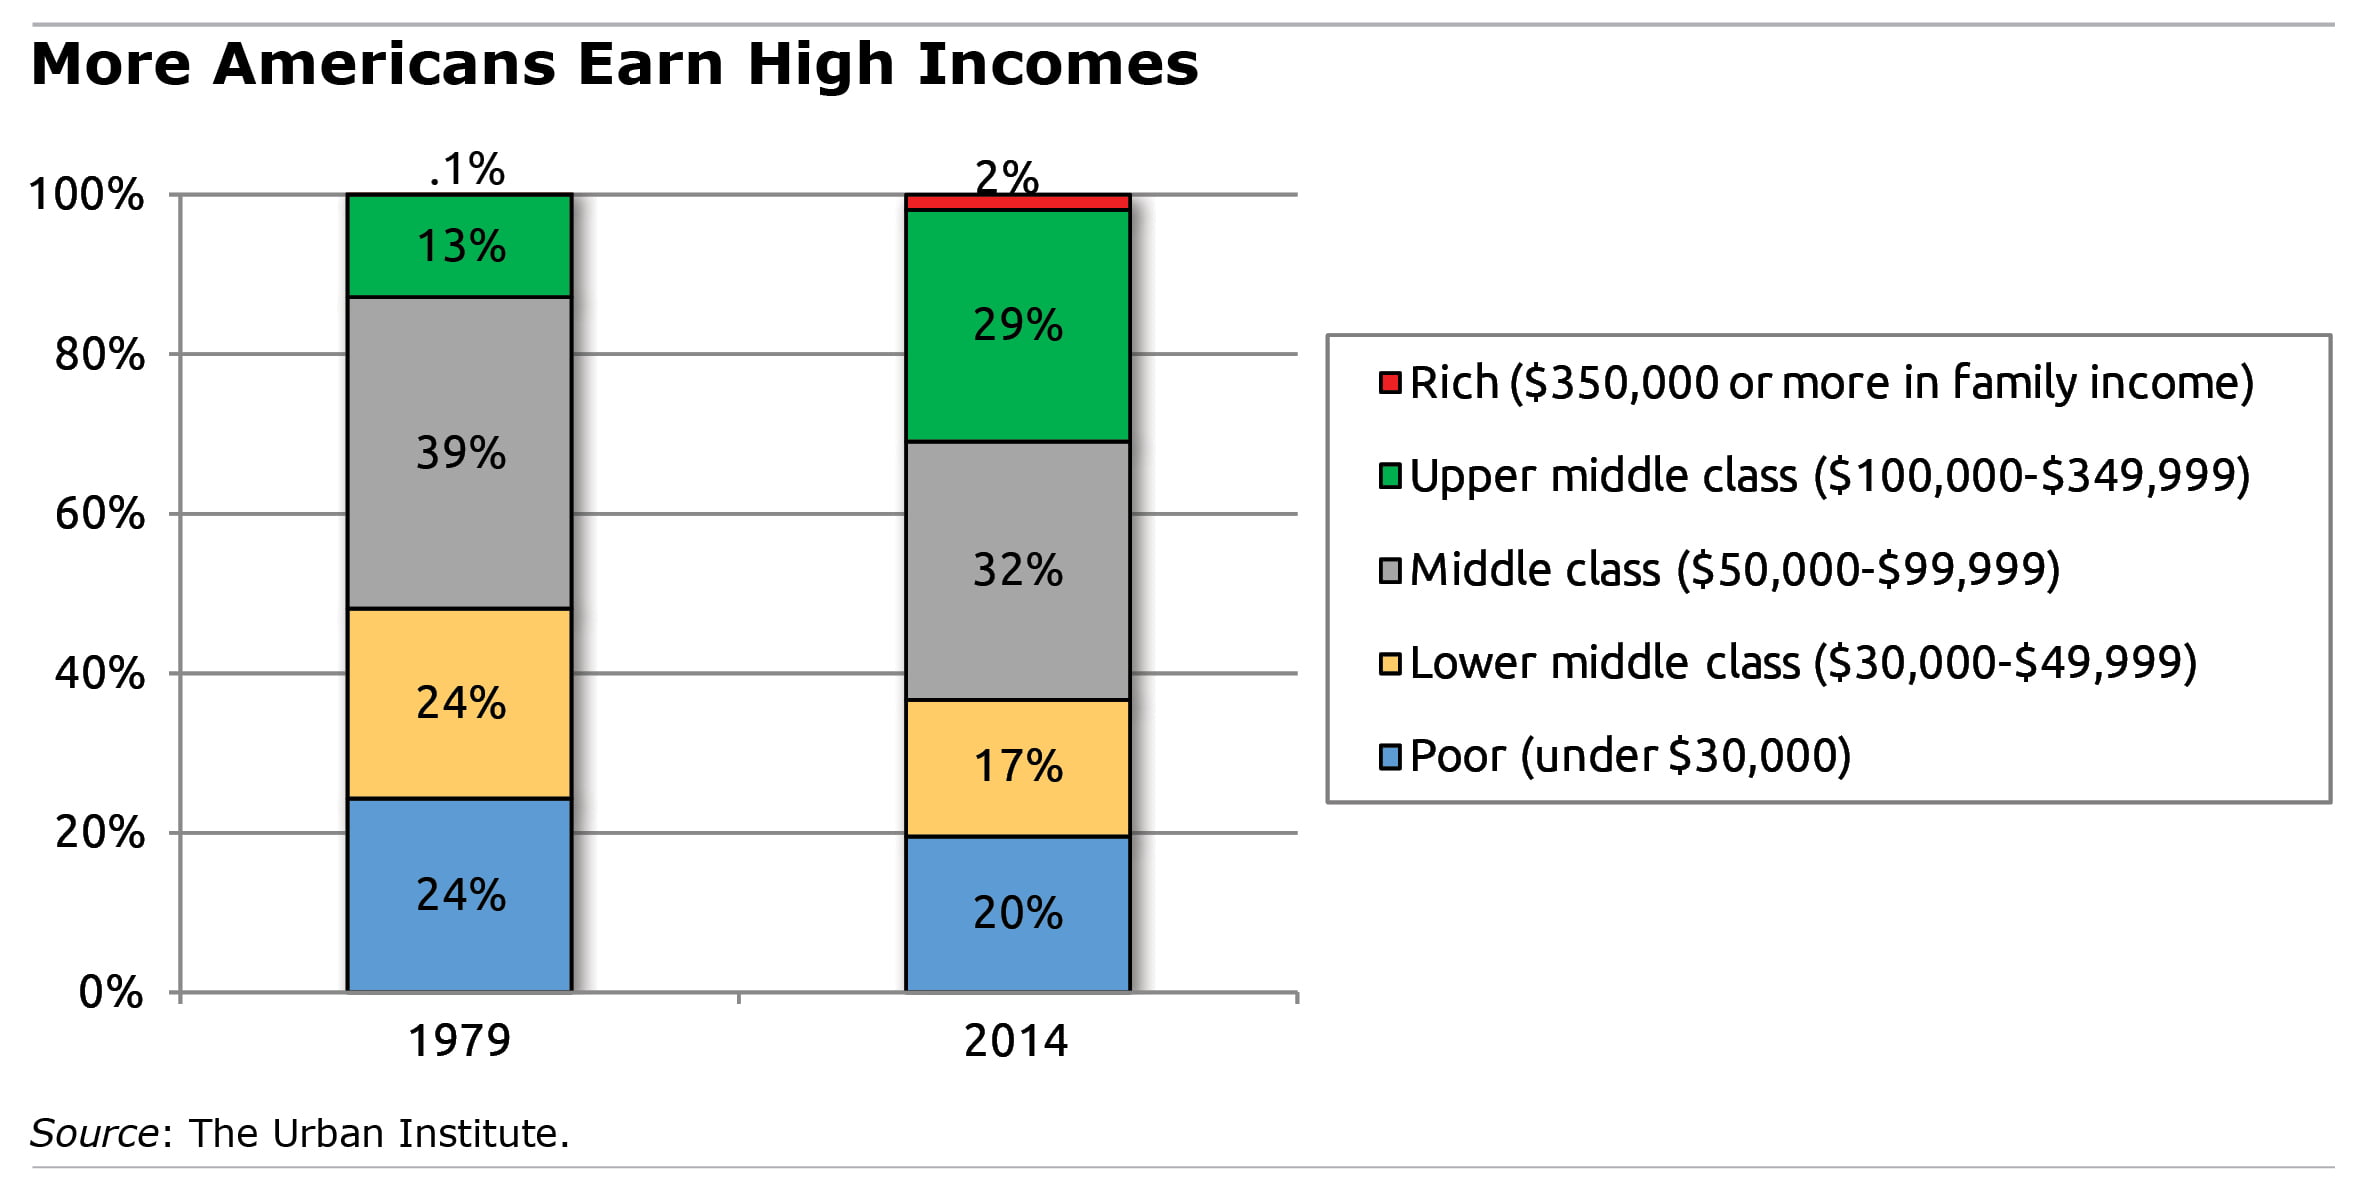
The upper middle class in Canada operates in a retirement landscape where government benefits are insufficient as a sole income source, yet personal savings carry tax and withdrawal complexities. Unlike the U.S., where Social Security replaces about 40% of pre-retirement income, Canada’s CPP and OAS combined typically cover only 20–30% of needs for this cohort. The gap must be filled by registered accounts (RRSPs, TFSAs), non-registered investments, and—for some—private pensions or business income. The challenge isn’t saving enough; it’s structuring withdrawals to minimize tax drag and maximize longevity. Provincial differences amplify this complexity. A retiree in Quebec benefits from lower healthcare premiums but faces higher income taxes, while Alberta’s lack of a provincial sales tax offsets higher property costs in cities like Calgary. Even within a province, municipal taxes can swing a budget. For example, a couple in Vancouver might allocate 25% of their income to housing-related costs, compared to 15% in Winnipeg. The upper middle class must treat retirement planning as a provincial math problem, not a one-size-fits-all calculation.The Context You Need
The upper middle class in Canada is a study in asymmetric risk. They’ve saved diligently—often with help from employer-matched RRSPs or professional financial advice—but their retirement income is vulnerable to three silent threats: 1. Tax bracket creep: Withdrawing too much from RRIFs or non-registered accounts can push them into higher marginal tax rates, especially in Ontario or BC. 2. Healthcare inflation: While OAS and CPP are indexed, private healthcare premiums (e.g., for dental or vision) are not, adding $3,000–$8,000 annually for couples over 65. 3. Interest rate sensitivity: Fixed-income portfolios (a staple for retirees) shrink in value when bond yields rise, as seen in 2022–2023. The solution requires dynamic asset location. For instance, holding equities in TFSAs (where capital gains are tax-free) and bonds in RRSPs (to defer tax) can smooth out volatility. Yet, this strategy demands regular rebalancing—something many retirees delegate to advisors, often at a cost. The upper middle class must weigh active management vs. passive index funds, recognizing that even a 1% fee difference over 30 years of retirement can mean $100,000+ in lost growth.The Mechanics
The mechanics of upper middle class retirement income in Canada hinge on three pillars: tax-efficient withdrawals, benefit optimization, and asset protection. Let’s break them down: 1. The Withdrawal Hierarchy: - TFSA first: Contributions are made after-tax, but withdrawals are tax-free. Ideal for short-term needs (e.g., travel, healthcare). - Non-registered accounts next: Capital gains and dividends are taxed at withdrawal, but holding periods can reduce the hit. - RRIF last: Mandatory withdrawals start at age 71, with tax paid on the full amount. Delaying RRIF conversions (if possible) can defer taxable income. 2. Benefit Timing: - CPP at 70: The maximum monthly payout is 42% higher than at 65. For a couple, this can add $1,200–$1,800/month to their income. - OAS at 67: Deferring until 70 increases the benefit by 36%, but only if income stays below the OAS clawback threshold ($90,750 for 2024). - Guaranteed Income Supplement (GIS): Means-tested but often overlooked; even upper middle-class retirees with modest savings may qualify. 3. Asset Protection: - Home equity: Reverse mortgages or selling down can inject capital, but trigger capital gains taxes (exempt for primary residences only after age 65 under certain conditions). - Annuities: Convert a portion of savings into a lifetime income stream to hedge against longevity risk, though fees can erode returns by 1–3% annually.Details That Change the Picture
The devil lies in the details—and for the upper middle class, those details often revolve around provincial tax quirks and unexpected costs. For example, Ontario’s Health Premiums (phased out in 2019 but replaced by higher income taxes) still create a $2,000–$4,000 annual tax hit for couples earning $100,000+. In contrast, Nova Scotia’s lower property taxes can save retirees $1,500–$3,000/year compared to Toronto. These variations mean a retiree’s effective tax rate can differ by 5–10 percentage points depending on location. Another often-overlooked factor is caregiving costs. While the upper middle class may not rely on government-subsidized care, hiring private help for aging parents or spouses can drain savings. A 2023 study by Statistics Canada found that 20% of retirees spend $5,000–$15,000 annually on unpaid caregiving support, money that could otherwise fund travel or healthcare. The solution? Long-term care insurance (if affordable) or family support networks, though the latter introduces emotional and financial risks."The upper middle class retiree’s biggest mistake isn’t saving too little—it’s assuming their wealth will compound forever. Inflation, taxes, and healthcare will eat away at it if they don’t plan for it." — David A. McKay, former CEO of the Ontario Teachers’ Pension Plan
| Province | Key Retirement Income Lever |
|---|---|
| Ontario | Maximize TFSA contributions (no provincial tax on withdrawals) and defer RRIF withdrawals until age 75 to stay in lower tax brackets. |
| British Columbia | Use the BC Senior’s Home Warrant Program to defer property taxes; consider moving to a lower-tax municipality (e.g., Kelowna vs. Vancouver). |
| Alberta | Leverage Alberta’s lower healthcare premiums and invest in non-registered accounts to benefit from the province’s 0% capital gains tax on farm/ranch assets (if applicable). |
| Quebec | Utilize the Quebec Pension Plan (QPP) enhancement (if applicable) and contribute to the REER (Quebec’s RRSP equivalent) for additional tax deferral. |
| Atlantic Canada | Take advantage of lower cost of living to stretch savings; some provinces offer senior property tax exemptions (e.g., Nova Scotia’s $10,000 exemption). |
Conclusion
The upper middle class in Canada enjoys the privilege of choice in retirement—choice of where to live, how to structure income, and when to access savings. But choice without strategy leads to unnecessary tax drag, missed benefit enhancements, and lifestyle erosion. The most successful retirees in this cohort treat their finances like a multi-asset portfolio, balancing liquidity, growth, and tax efficiency. They don’t just save; they engineer their income streams to adapt to an economy where inflation and healthcare costs are the only certainties. The key takeaway? Retirement isn’t a static endpoint—it’s a dynamic phase requiring annual reviews, provincial tax planning, and flexibility. A retiree who locked in their strategy at 65 without revisiting it at 70 or 75 might find themselves in a higher tax bracket or facing unexpected care costs. The upper middle class can afford to plan meticulously—and those who do will not only preserve their wealth but enjoy the financial freedom they’ve worked decades to achieve.Comprehensive FAQs
Q: How much should an upper middle-class couple aim to save by retirement?
Industry estimates suggest $1.5–$2.5 million in liquid assets (including RRSPs, TFSAs, and non-registered investments) for a couple retiring in Ontario or BC to maintain their lifestyle. However, this varies widely by province, healthcare needs, and desired lifestyle. A financial advisor can run a Monte Carlo simulation to stress-test your specific savings goal against inflation and market volatility.
Q: Is it better to withdraw from a TFSA or RRIF first in retirement?
Withdraw from TFSAs first, as contributions were made after-tax and withdrawals are tax-free. RRIFs should be a last resort due to mandatory withdrawals and tax implications. However, if you’ve maxed out TFSAs and have significant non-registered investments, those may be a middle ground—capital gains are taxed at withdrawal, but holding periods can reduce the tax hit.
Q: How do provincial taxes affect retirement income?
Provincial taxes can reduce your effective income by 10–20% depending on where you retire. For example, Ontario’s combined federal/provincial tax rate on RRIF withdrawals can reach 49.53% for high earners, while Alberta’s tops out at 48.97%. Quebec adds a health services tax (up to 1.5%) on top of income tax. Retirees in low-tax provinces like Saskatchewan or New Brunswick can keep more of their CPP and OAS benefits.
Q: Should I defer CPP and OAS to 70?
Yes, if your income stays below the OAS clawback threshold ($90,750 for 2024). Deferring CPP to 70 increases your monthly payout by 7.2% per year, while deferring OAS adds 0.6% per month. For a couple, this can mean an extra $2,000–$3,000/month in retirement income. However, if you have health issues or expect to need the income earlier, claiming at 65 or 67 may be prudent.
Q: Can I still work part-time in retirement and affect my benefits?
Yes, but the rules vary. CPP contributions can be made up to age 70, and working can increase your CPP payout if you earn above the yearly maximum ($66,600 in 2024). However, OAS is clawed back if your net worldwide income exceeds $90,750 (for 2024). Part-time work can also reduce GIS eligibility, which is means-tested. Consult a tax professional to model the impact on your specific situation.
Q: How do I account for healthcare costs in retirement planning?
Healthcare costs can add $5,000–$15,000 annually for a couple, depending on province and needs. Ontario’s drug plans (for seniors 65+) cover basic prescriptions, but private plans (e.g., for dental, vision, or travel insurance) can cost $3,000–$8,000/year. Long-term care insurance is critical—without it, a one-year stay in a private nursing home can cost $60,000–$100,000. Build a healthcare contingency fund of $100,000–$200,000 into your retirement plan.
Q: What’s the best way to leave an inheritance while minimizing tax?
The most tax-efficient strategies include: - TFSA withdrawals: Tax-free to heirs. - Capital gains exemptions: Up to $1 million in capital gains is tax-free when transferring a qualified small business corporation (QSBC) shares to a child. - Life insurance policies: Proceeds are tax-free to beneficiaries. - Donations: Charitable gifts reduce taxable estate value. However, RRIF and RRSP assets are fully taxable to heirs upon your death unless transferred to a spouse (who can then withdraw tax-free if using their own RRIF).
Q: How often should I review my retirement income plan?
Annually, especially after major life events (e.g., moving provinces, health changes, or market downturns). A quarterly check-in is ideal if you’re drawing down significant savings. Reassess: - Withdrawal rates (aim for 3–4% annually to avoid outliving your money). - Tax bracket risks (e.g., RRIF withdrawals pushing you into a higher tax rate). - Inflation adjustments (ensure your budget accounts for 2–3% annual cost increases). A financial advisor can help stress-test your plan against worst-case scenarios (e.g., a 2008-style market crash in your first five years of retirement).
