
The Complete Overview of the SEC’s 2024 Accredited Investor Income and Net Worth Requirements
The SEC’s accredited investor framework serves as a financial litmus test, separating sophisticated participants from the general public in private capital markets. At its core, the definition hinges on two pillars: income-based qualification and net worth-based qualification, each with specific thresholds that have remained stable since 2011 despite periodic reviews. For 2024, the income requirement stands at $200,000 individually or $300,000 jointly over the prior two years, while the net worth benchmark is $1 million, excluding the value of a primary residence. These figures, though seemingly static, are interpreted differently across jurisdictions and asset classes, creating gray areas for investors with complex portfolios. What often goes unnoticed is how these thresholds interact with broader economic shifts. Inflation, for instance, has gradually diluted the purchasing power of the $1 million net worth marker, yet the SEC has resisted adjustments, citing consistency in regulatory expectations. Meanwhile, the rise of alternative investments—from crypto to private credit—has pushed some high-net-worth individuals to test the boundaries of what constitutes "investable" assets under the net worth rule. The SEC’s stance remains firm: illiquid assets, like art or collectibles, are excluded from the net worth calculation unless they can be readily converted to cash. This distinction becomes critical for investors with significant holdings in non-traditional assets.Historical Background and Evolution
The accredited investor concept traces back to the Securities Act of 1933, where the SEC introduced the idea of exempting certain transactions from registration requirements if offered only to "sophisticated" investors. The formal definition emerged in Regulation D (1982), codifying the income and net worth tests as a proxy for financial sophistication. Over time, the thresholds were adjusted—most notably in 2011—to reflect inflation and market conditions, but the core structure endured. This stability has created a paradox: while the dollar figures have remained unchanged, the economic reality they represent has shifted. The 2023 SEC rule changes marked the first major expansion of the definition in decades, adding criteria like professional certifications (e.g., Series 7, Series 65 licenses) and knowledgeable employees of private funds. Yet the income and net worth requirements—the SEC definition accredited investor income net worth requirements 2024’s bedrock—remained untouched. This suggests that while the SEC is willing to broaden access through alternative pathways, it retains a cautious approach to altering the financial thresholds that have defined accredited status for nearly four decades.Core Mechanisms: How It Works
The qualification process begins with self-certification. Issuers of private securities rely on investors to attest to their status, a system that assumes honesty and basic financial literacy. For income-based qualification, the SEC looks at pre-tax earnings over the prior two years, meaning a high earner in year one but a downturn in year two could still qualify if the average meets the threshold. Net worth, meanwhile, is a snapshot: the $1 million figure must be held at the time of investment, excluding the primary residence—a provision that often sparks disputes over property valuations. Where complications arise is in the treatment of joint filers. A married couple with $250,000 in combined income over two years would not qualify under the individual threshold but would meet the $300,000 joint requirement. Similarly, a family office managing assets across multiple entities must carefully aggregate net worth, ensuring that excluded assets (like a vacation home) don’t inflate the total beyond the $1 million limit. The SEC’s guidance on these matters is sparse, leaving room for interpretation—and potential enforcement risks for issuers who misapply the rules.Key Benefits and Crucial Impact
The accredited investor designation isn’t merely a checkbox; it’s a passport to a tier of financial opportunities unavailable to the general public. Private equity funds, venture capital deals, and pre-IPO investments often require accredited status, offering potential for high returns but also higher risk. For issuers, the designation streamlines compliance with SEC registration requirements under Regulation D, reducing administrative burdens. Yet the system also creates an asymmetric access problem: those who already have wealth gain further advantage, while retail investors are locked out of deals that could offer outsized upside. The impact extends beyond individual investors. Startups and private funds rely on accredited investors to fuel growth, but the concentration of capital among a small pool of participants can distort market dynamics. Critics argue that the high thresholds perpetuate wealth inequality, while proponents contend that the rules protect investors from complex, illiquid assets they may not fully understand. The debate underscores a fundamental tension: should private markets be open to all, or reserved for those deemed capable of bearing risk?"Accredited investor rules were never about protecting the rich—they were about protecting the unsophisticated from deals they don’t understand. But over time, the definition has become a wealth gatekeeper, not a risk filter." — SEC Commissioner Hester Peirce, 2022
Major Advantages
- Access to exclusive deals: Accredited investors can participate in private placements, angel investments, and hedge funds that are off-limits to retail investors.
- Reduced regulatory scrutiny: Issuers benefit from exemptions under Regulation D, avoiding the costly and time-consuming SEC registration process.
- Networking opportunities: High-net-worth investor circles often provide deal flow, mentorship, and industry connections unavailable to non-accredited participants.
- Tax and estate planning benefits: Certain private investments offer deferral or exclusion benefits under tax codes that retail investors cannot access.
- Liquidity flexibility: Some private investments, like real estate syndications, allow for structured exits that public markets cannot match.
- Global investment reach: Accredited status often aligns with international investor classifications, enabling participation in offshore funds and sovereign wealth vehicles.
Comparative Analysis
| Criteria | SEC Definition (2024) |
|---|---|
| Individual Income Threshold | $200,000 (pre-tax) over the prior two years |
| Joint Income Threshold | $300,000 (pre-tax) over the prior two years |
| Net Worth Threshold | $1 million (excluding primary residence) |
| Alternative Pathways (2023+) | Professional certifications (Series 7, Series 65), knowledgeable employees, or certain institutional investors |
Future Trends and Innovations
The SEC’s reluctance to adjust the income and net worth thresholds may soon face pressure from economic realities. With inflation persistently eroding purchasing power, some advocates argue for periodic reviews—though political and regulatory inertia could delay changes. Meanwhile, the rise of digital assets and decentralized finance (DeFi) is forcing a reckoning: should crypto holdings count toward net worth? The SEC has been silent on this, but industry players are already pushing for clarity, fearing misclassification could lead to enforcement actions. Another trend is the blurring of lines between accredited and non-accredited investors. Platforms like Republic and Wefunder are testing "regulated crowdfunding" models that allow non-accredited investors to participate in startups, albeit with lower investment caps. If successful, these models could pressure the SEC to reconsider the rigidity of its thresholds. For now, however, the SEC definition accredited investor income net worth requirements 2024 remain the gold standard—though their longevity may depend on how well they adapt to a changing financial landscape.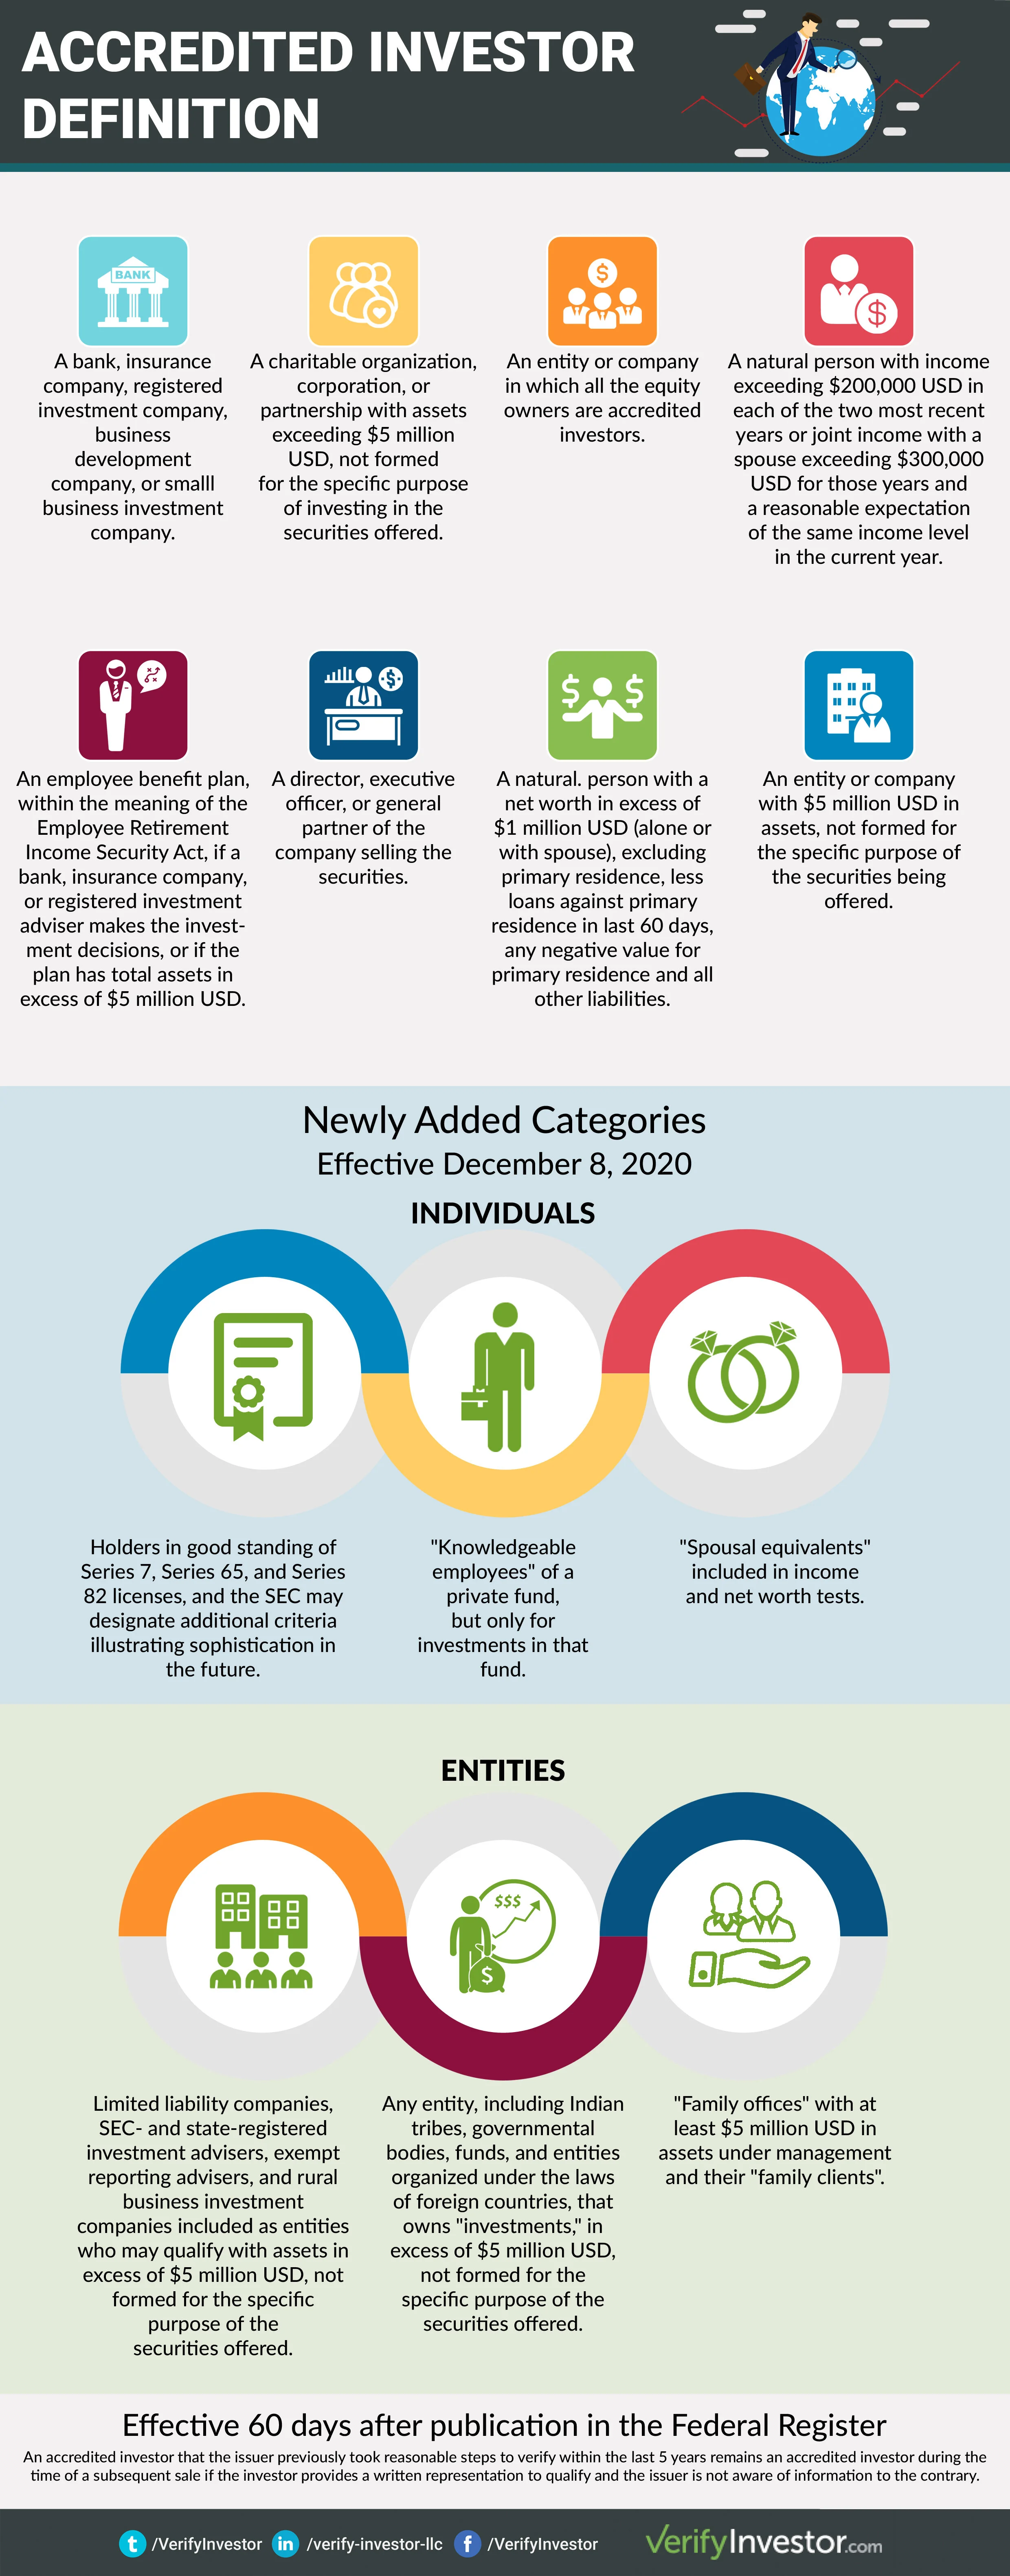
Conclusion
The SEC’s accredited investor criteria, centered on income and net worth, are more than just numerical thresholds—they’re a reflection of how private capital is allocated in the U.S. For issuers, they simplify compliance; for investors, they open doors to high-risk, high-reward opportunities. Yet the system is not without flaws: it favors those who already have wealth, and its static thresholds risk becoming outdated in an era of economic volatility. As alternative investments grow and regulatory scrutiny intensifies, the debate over whether to reform these rules will only sharpen. One thing is certain: understanding the SEC’s 2024 accredited investor income and net worth requirements is non-negotiable for anyone navigating private markets. Whether you’re an entrepreneur seeking funding, a fund manager structuring an offering, or an individual investor eyeing alternative assets, these thresholds will determine your eligibility—and your access to a world of capital that remains largely off-limits to others.Comprehensive FAQs
Q: Can I qualify as an accredited investor if my income fluctuates significantly?
The SEC evaluates income over the prior two years, so fluctuations are averaged. For example, if you earned $180,000 in Year 1 and $220,000 in Year 2, your average ($200,000) meets the threshold. However, issuers may conduct additional due diligence to verify consistency.
Q: Does my primary residence count toward the $1 million net worth requirement?
No. The SEC explicitly excludes the value of a primary residence from the net worth calculation. Secondary homes, rental properties, and other real estate are included.
Q: What if my spouse and I file taxes separately but meet the joint income threshold?
You can still qualify under the $300,000 joint income rule, even if you file separately. The key is that your combined income over two years meets the threshold.
Q: Are there any exceptions for non-U.S. investors?
The SEC’s accredited investor definition applies to U.S. persons (citizens, residents, and entities). Non-U.S. investors must meet their home country’s equivalent thresholds or qualify under alternative exemptions, such as the Regulation S offshore offering framework.
Q: How does the SEC verify accredited investor status?
Issuers rely on self-certification, meaning investors attest to their status. However, issuers can (and should) conduct reasonable inquiries, such as requesting tax returns or bank statements, to prevent fraud. Misrepresentation can lead to SEC enforcement actions against both the investor and the issuer.
Q: Can I lose accredited investor status if my net worth drops below $1 million?
Yes. The $1 million net worth requirement must be met at the time of investment. If your portfolio declines below the threshold afterward, it doesn’t retroactively disqualify you—but future investments would require re-verification.
Q: Are there any upcoming changes to the 2024 thresholds?
As of 2024, the SEC has no announced plans to adjust the income or net worth thresholds. However, proposals for inflation indexing or expanded alternative pathways (e.g., crypto holdings) could emerge in future rulemaking cycles.
