The Complete Overview of the Accredited Investor 1m Net Worth Credit Report
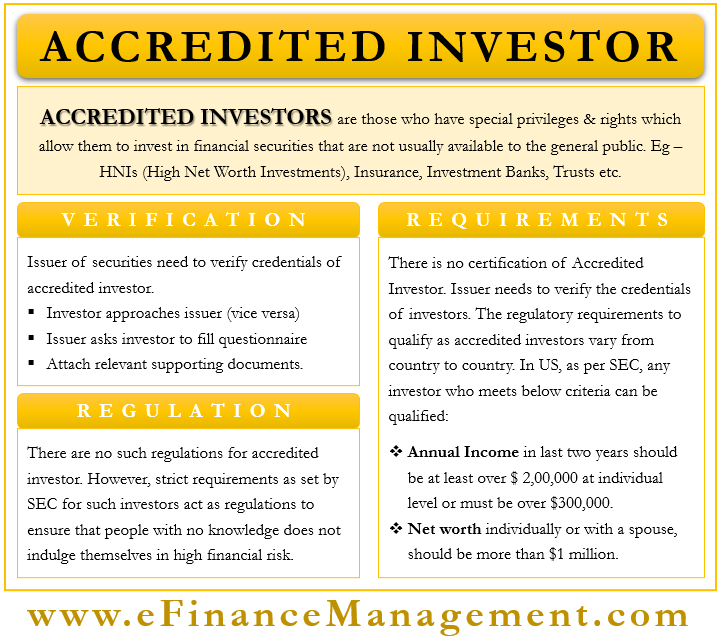
The accredited investor 1m net worth credit report isn’t just a credit score—it’s a financial fingerprint. For issuers and platforms, it serves as both a risk assessment tool and a compliance safeguard under SEC Rule 501. When an individual’s net worth exceeds $1 million (excluding their primary residence), their credit report takes on added weight. Lenders and investment firms cross-reference it with bank statements, brokerage activity, and even past legal filings to ensure the $1m figure isn’t inflated. The report’s role evolves from a snapshot of debt history to a verification tool for asset liquidity, tax compliance, and potential liens that could undermine net worth claims. The complexity arises from how credit bureaus handle high-net-worth data. Traditional credit reports focus on consumer debt and payment history, but for those with accredited investor 1m net worth, the report must also reflect: - Illiquid assets (e.g., art collections, private business stakes) that aren’t captured in standard credit models. - Offshore exposures requiring additional documentation under FATCA or CRS regulations. - Tax liens or judgments that might not appear in consumer credit files but could erode net worth. This disconnect often forces high-net-worth individuals to supplement their credit report with third-party verification—such as a CPA-prepared net worth statement or a sworn affidavit—when applying for accredited investor 1m net worth-eligible opportunities.Historical Background and Evolution
The concept of net worth as a proxy for investment sophistication traces back to the 1933 Securities Act, but the modern framework for accredited investor 1m net worth standards was solidified in the 1980s. The SEC’s Rule 501, introduced to streamline access to private capital, initially set the bar at $1 million in net worth or $200,000 in annual income. Over time, as alternative investments proliferated, the $1m threshold became a de facto gatekeeper for high-risk, high-reward opportunities—from venture capital to unregistered securities. The rise of crowdfunding platforms in the 2010s further cemented the need for rigorous 1m net worth credit report vetting, as issuers sought to limit liability under Regulation D. What changed the game was the 2016 SEC amendment expanding the definition to include "natural persons who individually or jointly with a spouse, manage investments in excess of $1 million." This shift forced credit reporting agencies to adapt. Equifax, Experian, and TransUnion began offering premium services tailored to high-net-worth individuals, integrating data from wealth managers and private banks. Yet, the system remains fragmented: a 1m net worth credit report pulled for a private equity fund raise might include data points a mortgage lender would never see—such as restricted stock units or carried interest—demonstrating how the report’s utility evolves with the investor’s profile.Core Mechanisms: How It Works
The process begins with the investor’s self-certification. When filing Form D (for private offerings) or applying to a platform like AngelList or SeedInvest, they must attest to meeting the accredited investor 1m net worth criteria. But issuers don’t take this at face value. They request a 1m net worth credit report from a bureau that specializes in affluent consumers—often one that partners with institutions like UBS or Goldman Sachs. These reports differ from consumer versions in three key ways: 1. Asset granularity: They may include appraisals of real estate, valuations of private business holdings, or even digital assets (e.g., crypto portfolios). 2. Liability transparency: Judgments, tax liens, or pending lawsuits that wouldn’t appear in a standard credit report are flagged. 3. Third-party validation: Some issuers require a letter from a CPA or financial advisor confirming the net worth figure, which is then cross-referenced with the credit report. The catch? Not all credit bureaus offer these enhanced reports. Investors often need to proactively request a "premium" or "investor-grade" credit report, which can cost between $50 and $300—far above the $15–$40 charged for consumer versions. This additional layer of cost and complexity is why many high-net-worth individuals preemptively clean up their financial records before seeking accredited investor 1m net worth-eligible opportunities.Key Benefits and Crucial Impact
For issuers, the accredited investor 1m net worth credit report is a risk mitigation tool. Private fund managers, for instance, use these reports to assess whether an investor’s liquidity aligns with the offering’s lock-up periods. A report showing high credit utilization or pending foreclosures might trigger a red flag, even if the investor’s net worth technically meets the threshold. The report’s impact extends beyond compliance: it influences pricing. Issuers may offer better terms (lower fees, higher allocations) to investors whose 1m net worth credit report demonstrates stability and deep pockets. The psychological dimension is equally significant. High-net-worth individuals often operate under the assumption that their wealth is self-evident—but the accredited investor 1m net worth process forces them to confront gaps. A credit report revealing an overlooked judgment or an underreported liability can prompt corrective action, from settling debts to restructuring assets. For those navigating estate planning or succession, the report serves as a reality check, exposing vulnerabilities that might not surface in annual tax filings."Net worth is a snapshot, but credit reports for accredited investors are a moving target. What looks solid in January might unravel by April if markets shift or a lawsuit emerges. The best investors don’t just hit the $1m mark—they anticipate how their credit profile will hold up under scrutiny." — Wealth Strategist at a Top 10 Private Bank
Major Advantages
- Access to exclusive opportunities: The accredited investor 1m net worth designation unlocks private equity, hedge funds, and pre-IPO investments that retail investors can’t touch.
- Reduced regulatory friction: Issuers rely on the 1m net worth credit report to fast-track approvals, cutting weeks off the vetting process.
- Enhanced negotiation leverage: A clean credit report signals financial stability, allowing investors to secure better terms or priority allocations.
- Early warnings on financial health: The report’s depth often reveals issues (e.g., hidden liabilities) before they become public or impact tax filings.
- Global mobility: In jurisdictions like the UK or Singapore, a verified accredited investor 1m net worth credit report simplifies residency or visa applications tied to investment thresholds.
Comparative Analysis
| Standard Credit Report | Accredited Investor 1m Net Worth Credit Report |
|---|---|
| Focuses on consumer debt (credit cards, mortgages, auto loans). | Includes illiquid assets (real estate, private equity, art) and offshore exposures. |
| Generated by Equifax/Experian/TransUnion for ~$15–$40. | Requires premium services (e.g., Equifax Affluent Consumer Report) at $50–$300. |
| Used for mortgages, loans, or rental applications. | Critical for private placements, hedge fund admissions, and high-net-worth lending. |
| 7-year reporting window for most negative items. | May include indefinite liabilities (e.g., tax judgments) that don’t appear in consumer reports. |
| No asset verification required. | Often demands third-party appraisals or CPA letters to validate net worth claims. |
Future Trends and Innovations
The next frontier for accredited investor 1m net worth credit reports lies in blockchain and AI-driven verification. Startups like Wealthsimple and Bloom are experimenting with real-time net worth tracking via bank feeds and investment portfolios, reducing reliance on static credit reports. Meanwhile, decentralized identity projects (e.g., PolySign) aim to let investors share verified financial data without exposing raw credit histories—a game-changer for cross-border accredited investor 1m net worth compliance. Regulatory shifts are also on the horizon. The SEC’s proposed changes to the accredited investor definition (expanding it to include certain professionals and knowledge-based investors) could dilute the net worth requirement’s prominence—but the 1m net worth credit report will likely persist as a proxy for financial resilience. As alternative assets (crypto, NFTs, private credit) grow in value, credit bureaus may need to integrate new data sources, turning the report into a dynamic tool rather than a static document.
Conclusion
The accredited investor 1m net worth credit report is more than a compliance checkbox—it’s a reflection of an investor’s financial discipline. For those who cross the $1 million threshold, the report becomes a mirror, revealing not just wealth but its fragility. Issuers, platforms, and regulators use it to separate the truly sophisticated from those who merely meet the numerical threshold. The key takeaway? Wealth verification isn’t passive. It demands proactive management: from disputing inaccuracies to strategically structuring assets to pass muster under scrutiny. As the financial landscape evolves, the report’s role will only expand. Whether through AI-driven insights or blockchain-backed verification, the accredited investor 1m net worth process will continue to shape who gets access—and on what terms. For high-net-worth individuals, the message is clear: the credit report isn’t just a document. It’s the first line of defense in a world where opportunity is gated by more than just numbers.Comprehensive FAQs
Q: Can a credit report alone prove I meet the accredited investor 1m net worth standard?
A: No. While a 1m net worth credit report is often requested, issuers typically require additional documentation—such as bank statements, tax returns, or a CPA-prepared net worth statement—to confirm liquidity and asset values. A credit report alone won’t suffice for compliance under SEC Rule 501.
Q: How often should I update my credit report if I’m pursuing accredited investor opportunities?
A: At least annually, or whenever major financial changes occur (e.g., selling a business, taking on debt, or acquiring significant assets). Since the accredited investor 1m net worth credit report is scrutinized for accuracy, outdated information can lead to disqualification. Some investors opt for quarterly checks if they’re actively seeking high-net-worth opportunities.
Q: Do offshore accounts affect my accredited investor 1m net worth credit report?
A: Yes. Offshore holdings must be disclosed and may require additional verification under FATCA or CRS regulations. A 1m net worth credit report pulled for international investors often includes flags for foreign bank accounts, and discrepancies can trigger deeper reviews by issuers or platforms.
Q: What’s the most common reason an accredited investor’s credit report gets rejected?
A: The top issues are: 1. Underreported liabilities (e.g., forgotten tax debts or judgments). 2. Illiquid assets not reflected in standard credit models (e.g., private company stakes). 3. Discrepancies between reported net worth and credit bureau data. Issuers prioritize consistency—if your credit report shows high credit utilization but your net worth statement claims liquidity, red flags arise.
Q: Can I dispute errors in my accredited investor 1m net worth credit report?
A: Absolutely. The process mirrors standard credit report disputes, but for high-net-worth individuals, the stakes are higher. Submit documentation (e.g., canceled checks, appraisals) to the credit bureau and the issuer reviewing your file. Some errors—like outdated liens—may require legal intervention to resolve.
Q: Are there alternatives to the traditional accredited investor 1m net worth path?
A: Yes. The SEC’s 2020 amendments expanded eligibility to include: - Knowledgeable employees of private funds. - Certain professionals (e.g., attorneys, engineers) with specific financial experience. - Non-U.S. investors meeting equivalent wealth thresholds in their home countries. However, the accredited investor 1m net worth credit report remains relevant for those relying on net worth as their primary qualification.
