The Short Answers
- Reg CF net worth proofs vary by offering tier—Tier 1 (under $1.07M) requires basic documentation, while Tier 2 (up to $5M) may demand W-2s, tax returns, or bank statements.
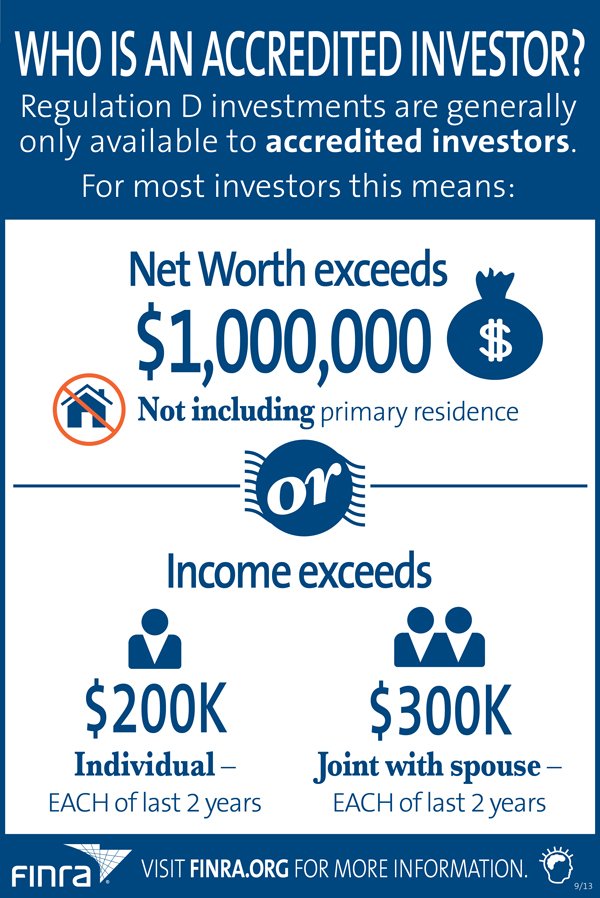
- Accredited investors (net worth ≥$1M or income ≥$200K/year) often bypass Reg CF entirely, but some platforms still ask for verification to align with SEC rules.
- Bank statements alone aren’t always sufficient—some platforms cross-reference with credit reports or require signed affidavits for liquid net worth.
- Digital verification tools (like Plaid or Stripe Identity) are growing in use, but paper trails still dominate for high-value claims.
- Discrepancies between reported and verifiable net worth can trigger red flags—platforms may reject submissions or escalate to the SEC.
Deep Dive: The Full Picture
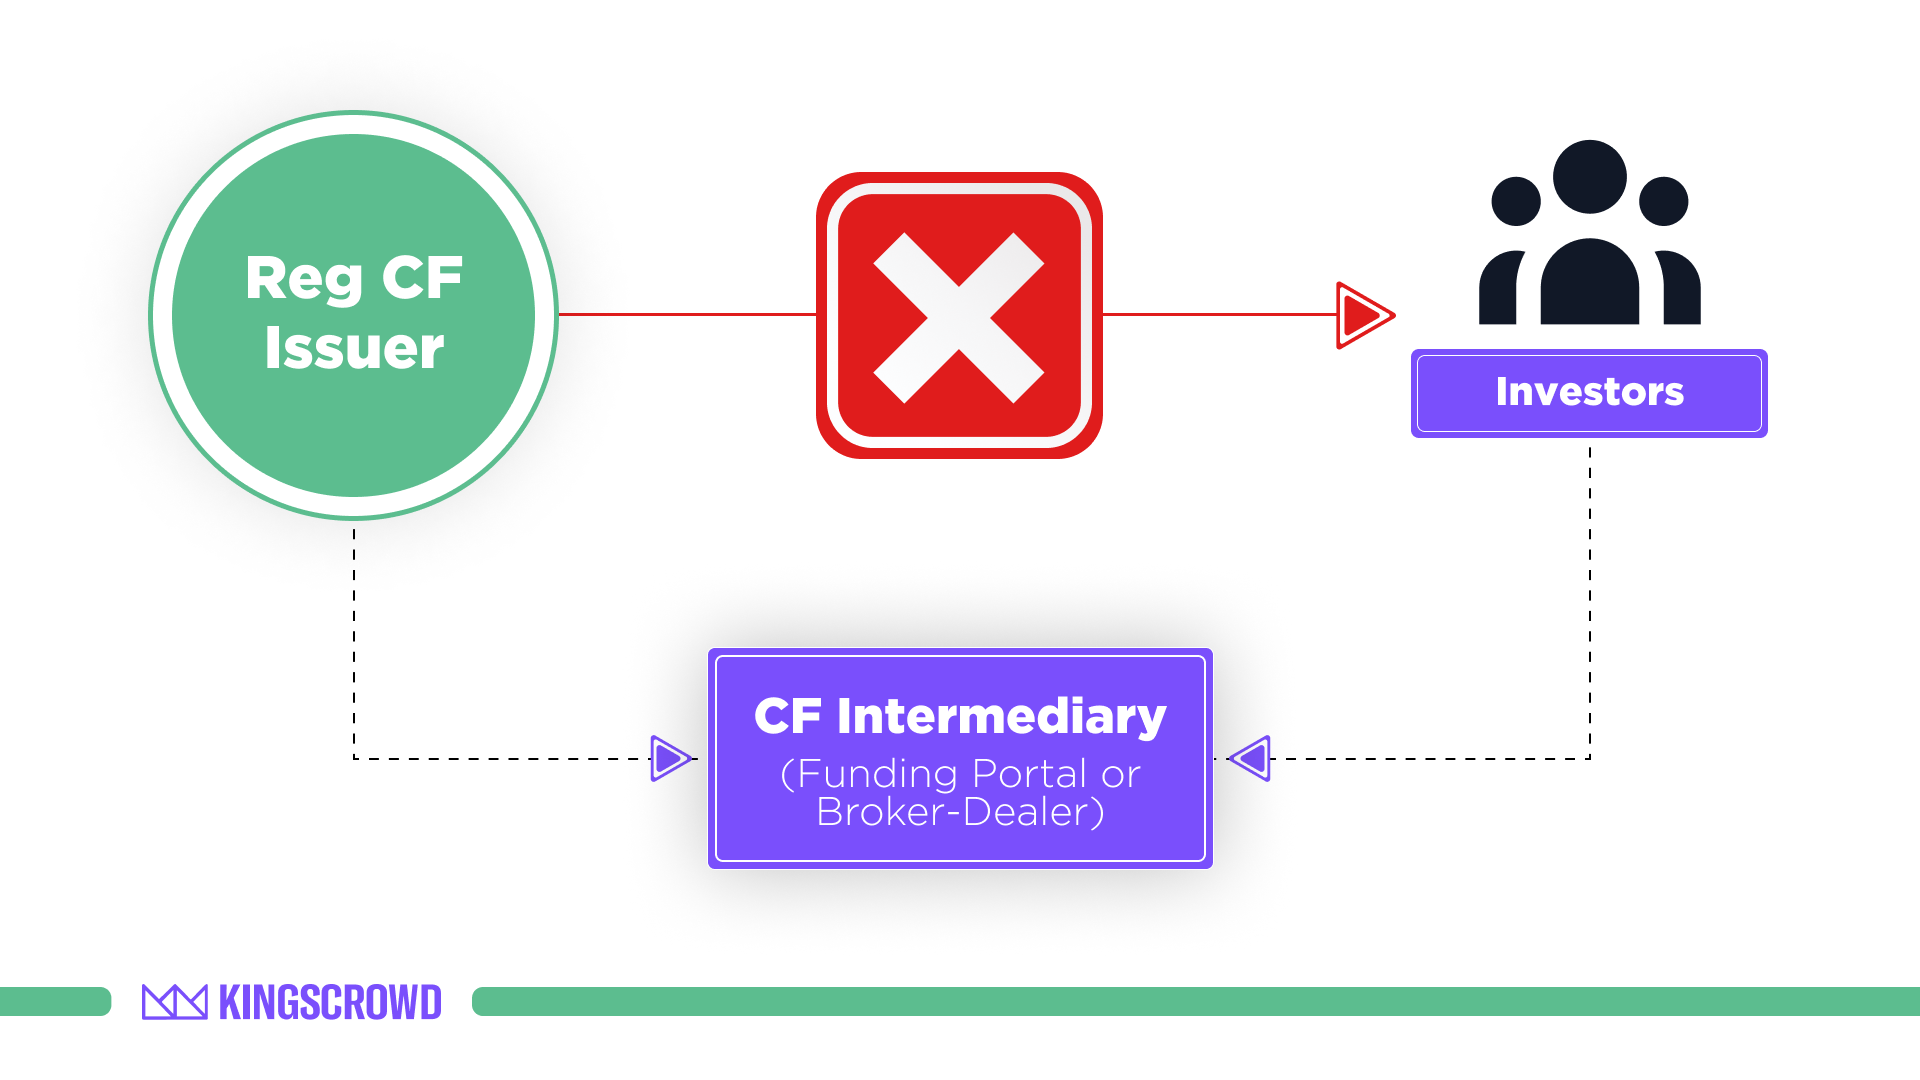
Regulation Crowdfunding was designed to democratize early-stage investing, but its net worth requirements create a paradox: the very people it aims to protect are often the ones who struggle most to document their finances. The SEC’s rules treat net worth as a proxy for risk tolerance, but in practice, proving it hinges on how neatly your assets align with what platforms accept. A self-employed freelancer with fluctuating income might face more scrutiny than a salaried professional with a clear paper trail—even if their net worth is identical. The confusion stems from two overlapping systems: the SEC’s formal definitions and the informal policies of crowdfunding platforms. While the SEC outlines broad standards, platforms like Wefunder, Republic, or StartEngine impose their own thresholds and documentation requests. Some require only a government-issued ID and a bank statement, while others demand tax returns spanning three years. The result? Investors who assume they qualify often find themselves locked out—or worse, unknowingly violating rules that could lead to enforcement actions.The Context You Need
Reg CF divides offerings into two tiers, each with distinct net worth triggers. Tier 1 (up to $1.07 million in a 12-month period) is the most accessible, but even here, platforms may enforce minimum net worth floors to filter out speculative investors. Tier 2 (up to $5 million) introduces stricter verification, often requiring proof of liquidity or consistent income streams. The SEC’s definition of "net worth" includes primary residences only if they’re encumbered by debt—but platforms rarely accept mortgaged properties as collateral for eligibility. Where things get messy is in the gray area between "net worth" and "investable capital." An investor with a $1.2 million home and a $300,000 mortgage might technically qualify, but if their liquid assets (cash, investments, retirement accounts) fall below $200,000, platforms may reject them. This disconnect forces investors to ask: Is the platform interpreting the rules correctly? The answer often depends on whether they’ve built their own compliance layer—or rely on third-party verification tools that may not account for all edge cases.The Mechanics
The proof process typically starts with a pre-screening questionnaire, where platforms ask for broad strokes: employment status, annual income, and asset ranges. But the real work begins when you’re asked to upload documentation. For Tier 1 offerings, this might be as simple as: - A government-issued ID (passport, driver’s license) - Recent bank statements (3–6 months of activity) - A signed affidavit (if claiming liquid net worth) Tier 2 offerings, however, often demand: - Tax returns (federal and state, typically the past two years) - Pay stubs or W-2s (for salaried employees; 1099s for contractors) - Brokerage or retirement account statements (to verify investable assets) - Proof of business income (if self-employed, including profit/loss statements) The catch? Platforms don’t always explain why they’re asking for specific documents. A request for three years of tax returns might stem from a past audit finding or an internal policy to mitigate fraud—not the SEC’s letter of the law. This opacity leaves investors guessing whether they’re over-documenting or under-documenting.Details That Change the Picture
Not all assets are created equal in the eyes of Reg CF verification. Primary residences are the most contentious: while the SEC allows them in net worth calculations, platforms often exclude them unless the investor provides a home appraisal and mortgage details. Retirement accounts (401(k)s, IRAs) are usually accepted, but some platforms cap their value at a percentage of total net worth—say, 50%—to account for early withdrawal penalties. Cryptocurrency holdings are the wild card; while they’re liquid, their volatility means platforms may require screenshots of wallet balances or exchange statements dated within 72 hours of submission. Then there’s the issue of joint accounts. If you’re married or in a domestic partnership, your spouse’s assets do count toward your net worth—but only if they’re legally yours. Platforms may ask for a marriage certificate or cohabitation agreement to avoid disputes. Self-employed individuals face additional hurdles: Schedule C filings must align with bank deposits, and platforms may reject claims if cash flow doesn’t match reported income. The message is clear: the more complex your financial picture, the more documentation you’ll need."We see rejection rates spike for investors who assume ‘net worth’ is just what’s in their checking account. A $500K home with a $200K mortgage might qualify them, but if they only submit bank statements, they’ll get flagged. It’s not about being rich—it’s about being verifiable." —Compliance officer at a mid-tier Reg CF platform
| Document Type | When It’s Required |
|---|---|
| Bank statements (3–6 months) | Tier 1 offerings; Tier 2 if liquidity is in question |
| Tax returns (federal + state) | Tier 2 offerings; self-employed or high-income earners |
| Brokerage/retirement statements | If investments exceed 30% of total net worth claim |
| Home appraisal + mortgage docs | If primary residence is relied upon for net worth |
| Signed affidavit of net worth | For investors with no traditional paper trail (e.g., gig workers) |
Conclusion
The biggest misconception about proving net worth in Reg CF is that it’s a binary process: either you qualify or you don’t. In reality, it’s a negotiation between your financial reality and a platform’s risk appetite. The SEC provides the framework, but platforms fill in the gaps—and those gaps are where most rejections happen. The solution isn’t to hoard every receipt you’ve ever had, but to anticipate what a platform might ask for based on your financial profile. Start by treating your net worth proof like a legal submission: organized, dated, and cross-referenced. If you’re self-employed, pull your tax filings and bank statements before you apply. If your primary residence is your largest asset, have an appraisal ready. And if a platform asks for something unusual—like a letter from your accountant—don’t assume it’s a mistake. It might be their way of covering their own compliance risks. The goal isn’t just to meet the letter of the law, but to demonstrate that you’ve thought through how your finances will be perceived.Comprehensive FAQs
Q: Can I use a letter from my accountant instead of tax returns to prove net worth?
A: Some platforms accept accountant-prepared financial statements (especially for complex cases), but this isn’t universal. If you choose this route, ensure the letter includes specific asset values, liabilities, and a clear net worth calculation. Platforms may still request supporting documents like bank statements or investment account summaries to verify the accountant’s claims. Always confirm in advance whether the platform allows this substitution.
Q: What if my net worth fluctuates—like if I’m in a high-commission sales role?
A: Reg CF platforms typically evaluate net worth as of the date of investment, not over a trailing period. If your income varies, you’ll need to provide recent pay stubs or a signed statement explaining your earning pattern. Some platforms may also ask for a letter from your employer confirming your role and average compensation. For self-employed individuals, year-to-date profit/loss statements (not just annual returns) can help demonstrate consistency.
Q: Do platforms verify the documents I submit, or do they just accept them at face value?
A: Verification varies by platform. Lower-tier platforms may perform basic checks (e.g., ensuring a bank statement matches the name on the ID), while higher-tier or institutional-backed platforms often use third-party verification tools (like Plaid or Stripe Identity) to cross-reference data. Some may spot-check a percentage of submissions by contacting banks or brokers directly. Never submit fraudulent documents—even if a platform doesn’t catch it, the SEC can hold you liable for misrepresentation in a Reg CF offering.
Q: What happens if I’m rejected after submitting documentation?
A: Rejections usually come with one of three explanations: 1. Insufficient proof (e.g., missing a critical document like a tax return). 2. Discrepancies (e.g., bank statements showing lower balances than claimed net worth). 3. Platform-specific policies (e.g., a minimum liquid asset threshold not mentioned in the SEC rules). Most platforms allow resubmissions if you can clarify or supplement your materials. If rejected repeatedly, consider whether the platform’s requirements align with your financial situation—or if another platform with less stringent rules might be a better fit.
Q: Can I prove net worth with cryptocurrency holdings?
A: Yes, but with significant caveats. Since crypto values can swing dramatically, platforms may: - Require screenshots of wallet balances (with timestamps) to show current holdings. - Cap crypto at a percentage of total net worth (e.g., no more than 20%). - Ask for exchange transaction histories to prove liquidity. If your crypto is held in a hardware wallet, you may need to provide proof of ownership (e.g., a seed phrase backup or exchange transfer logs). Never submit private keys or unencrypted wallets—platforms will reject these outright for security reasons.
Q: What’s the fastest way to get approved for a Reg CF investment?
A: Speed depends on how prepared you are and which platform you use. For the quickest turnaround: 1. Use a platform with automated verification (e.g., those integrated with Plaid or Stripe). 2. Have all documents ready before applying (ID, bank statements, tax returns if needed). 3. Apply during off-peak hours (weekday mornings see less backlog). 4. Avoid complex financial situations (e.g., holding assets in trusts or offshore accounts adds review time). 5. Check for platform-specific expedited review options—some offer "priority processing" for a fee.
Q: Are there any red flags that might get my net worth claim rejected?
A: Yes. Common triggers include: - Large cash deposits without clear sourcing (e.g., a sudden $50K deposit with no explanation). - Discrepancies between W-2 income and bank deposits (e.g., reported $150K salary but only $100K in direct deposits). - Using assets you don’t fully control (e.g., claiming a spouse’s 401(k) without joint ownership proof). - Submitting outdated documents (e.g., a 2022 tax return when 2023 is required). - Overstating liquidity (e.g., counting a locked-up investment as available capital). Always err on the side of understating—platforms would rather approve a conservative claim than risk a compliance violation.
