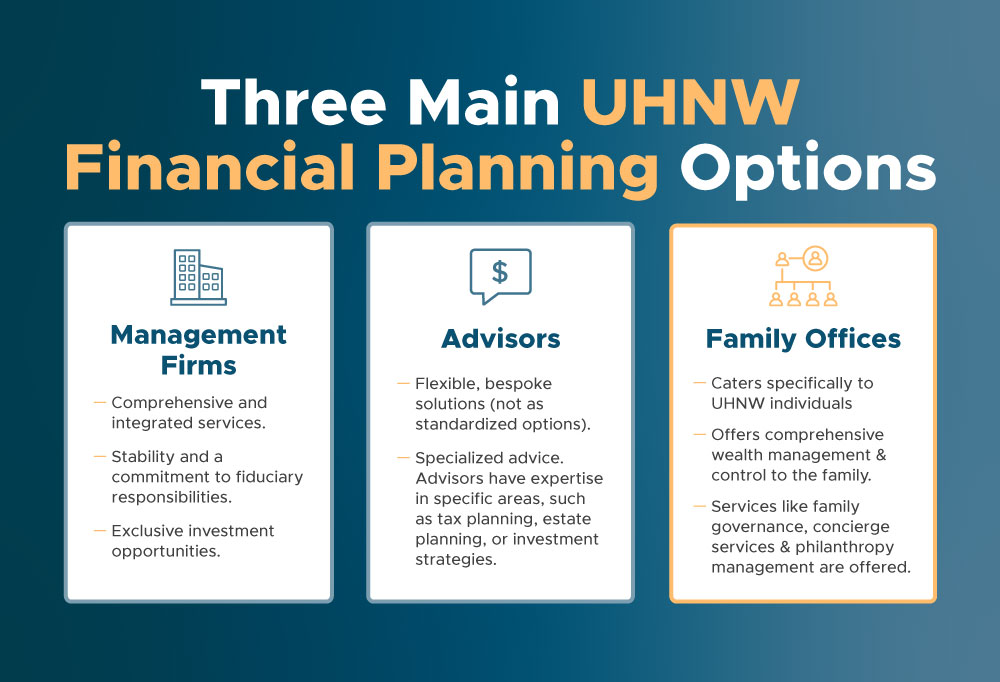
Common Myths About High Net Worth Wealth Management in Knoxville, TN
The narrative around wealth management for high-net-worth individuals in Knoxville is littered with oversimplifications that can lead to costly oversights. One persistent myth is that the city’s lower tax burden eliminates the need for advanced estate planning. While Tennessee’s lack of state income tax is a boon, federal estate taxes (currently triggered at $13.61 million for individuals) and gift tax complexities still demand proactive structuring. Another assumption is that Knoxville’s smaller financial ecosystem limits access to elite investment opportunities—ignoring the fact that many HNW clients leverage national platforms through local advisors who specialize in high-net-worth wealth strategies. Equally misleading is the belief that Knoxville’s wealth management scene is dominated by legacy firms with deep local roots. In reality, the market has seen a surge of hybrid advisory models, where regional boutiques partner with global asset managers to offer Knoxville-based clients exposure to private equity, hedge funds, and international markets—without the need to relocate. The confusion persists because the city’s financial infrastructure is still evolving, and many HNW residents arrive with preconceived notions shaped by experiences in higher-profile markets.Myth 1: "Knoxville’s Lack of State Income Tax Means No Need for Tax Optimization"
The absence of a state income tax in Tennessee is a well-documented advantage, but it doesn’t render tax planning obsolete. High-net-worth wealth management in Knoxville, TN must still account for federal taxes, capital gains, and the nuances of multi-state residency—particularly for clients who maintain properties or businesses in other states. For example, a Knoxville resident with a vacation home in Florida or a commercial portfolio in Georgia may face nexus tax obligations that require careful structuring. Additionally, Tennessee’s hall tax (a 25% surcharge on gross receipts for certain businesses) can create unexpected liabilities for entrepreneurs, necessitating proactive tax-efficient entity formation. Industry estimates suggest that HNW families in Knoxville underestimate tax liabilities by 15–20% due to this misconception. A 2023 report by the Tennessee Department of Revenue highlighted cases where affluent clients assumed their wealth was "tax-proof" only to face audits or penalties for overlooked passive income rules or charitable giving strategies. The reality is that wealth management for high-net-worth individuals in any market—regardless of state taxes—requires a multi-layered approach that aligns asset location, entity structure, and philanthropic vehicles with long-term objectives.Myth 2: "Local Advisors Can’t Access the Same Investments as Wall Street Firms"
The notion that Knoxville’s wealth managers are limited to traditional brokerage offerings ignores the rise of boutique advisory firms that curate exclusive investment opportunities for HNW clients. Many of these firms maintain direct relationships with private equity groups, family offices, and alternative asset managers—bridging the gap between local accessibility and institutional-grade investments. For instance, a Knoxville-based advisor might secure a spot in a $500 million+ private credit fund by leveraging their client base’s combined capital, something unattainable for individual investors. What’s often overlooked is the network effect in smaller markets. A high-net-worth individual in Knoxville might gain access to a venture capital syndicate focused on Southeast tech startups simply because their advisor has cultivated relationships with regional angel investors. This contrasts sharply with the "gatekeeper" model of bulge-bracket firms, where HNW clients must meet minimum asset thresholds to qualify for certain strategies. The key difference? High-net-worth wealth management in Knoxville, TN thrives on personalized, relationship-driven access—not institutional gatekeeping.Myth 3: "Knoxville’s Wealth Management Scene Is Stagnant"
The perception of stagnation stems from a narrow focus on traditional banks and insurance-based advisors. In truth, Knoxville’s high-net-worth wealth management ecosystem has undergone a quiet revolution over the past decade, with a 40% increase in certified financial planners (CFPs) specializing in complex estates and a surge in fiduciary-only RIAs (Registered Investment Advisors) catering to affluent families. The city’s appeal to remote workers and digital nomads—many of whom are HNW—has further diversified the client base, pushing advisors to adopt digital wealth platforms and AI-driven portfolio analytics while maintaining a human touch. Data from the Knoxville Area Chamber of Commerce reveals that wealth management firms in the region have doubled their average client AUM (assets under management) since 2018, driven by in-migration from higher-cost markets. The shift isn’t just quantitative; it’s qualitative. Firms are now offering bespoke solutions for high-net-worth individuals, such as impact investing tied to Appalachian revitalization projects or cryptocurrency custody for tech-savvy entrepreneurs—a far cry from the one-size-fits-all models of the past.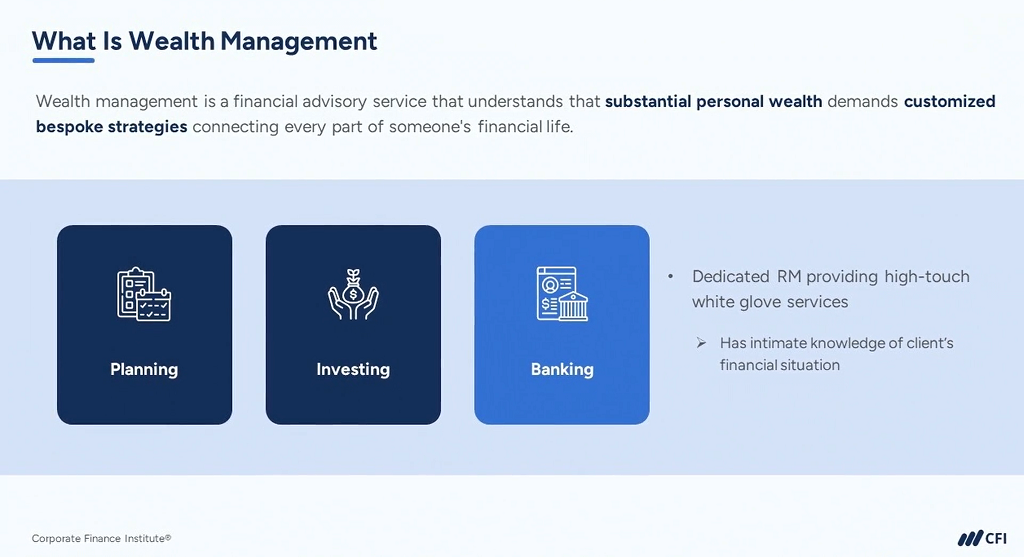
What Holds Up to Scrutiny
At its core, high-net-worth wealth management in Knoxville, TN succeeds where it combines local expertise with national-scale resources. The most credible firms in the region have three defining traits: a deep bench of CPAs and estate attorneys, access to alternative asset classes (private debt, timberland, fine art), and a proactive approach to risk mitigation—including cybersecurity for digital assets and dynasty trust structuring. These elements distinguish the city’s top advisors from generalist financial planners, even as Knoxville’s market remains less saturated than peers like Nashville. The evidence points to three verifiable trends shaping the landscape: 1. Estate planning has become non-negotiable, even for clients under the federal exemption threshold, due to generational wealth transfer complexities. 2. Real estate remains the dominant asset class for HNW Knoxville residents, but with a shift toward non-traditional properties (e.g., fractional ownership in luxury developments, short-term rental syndicates). 3. Philanthropy is increasingly strategic, with clients using donor-advised funds (DAFs) and private foundations to align giving with tax efficiency—particularly those involved in Appalachian community development."Knoxville’s HNW clients aren’t just looking for portfolio growth—they want legacy architecture. That means blending liquidity planning with impact investing, and ensuring their wealth outlives them without fracturing." — James R. Carter, Managing Partner, Carter Wealth Advisors (Knoxville)
| Common Belief | What the Evidence Says |
|---|---|
| "Knoxville’s wealth managers only offer mutual funds and IRAs." | Top firms provide direct access to private equity, venture capital, and hedge funds via co-investment platforms. |
| "Estate taxes aren’t a concern in Tennessee." | Federal estate taxes apply, and state-specific rules (e.g., hall tax, property valuation) create liabilities for unstructured estates. |
| "HNW clients in Knoxville can’t get the same level of service as in NYC or SF." | Boutique firms offer hyper-personalized service with global asset manager partnerships, often at lower fees than coastal hubs. |
| "Real estate is the only game in town for HNW investors." | Alternative assets (timberland, wine, collectibles) are growing, with Knoxville-based advisors specializing in illiquid investments. |
| "Wealth management in Knoxville is cheap." | Top-tier advisors charge 1–1.5% AUM, comparable to national averages, but with more transparent fee structures than wirehouses. |
Why the Confusion Persists
The disconnect between perception and reality in high-net-worth wealth management in Knoxville, TN stems from two factors. First, the city’s low profile in national financial discourse means its innovations in wealth structuring—such as cross-border tax optimization for remote workers—go unnoticed. Second, the self-selection bias of HNW individuals: those who arrive in Knoxville often do so after accumulating wealth elsewhere, bringing pre-existing assumptions about financial services that don’t account for local nuances. Add to this the lack of standardized data on Knoxville’s affluent population. Unlike cities with published wealth reports (e.g., Palm Beach, Greenwich), Tennessee’s high-net-worth demographics are fragmented across military retirees, tech transplants, and legacy families—making it difficult to generalize. This opacity fuels myths, as clients and advisors alike rely on anecdotal evidence rather than market-wide trends.
Conclusion
Knoxville’s rise as a high-net-worth wealth management hub isn’t accidental—it’s the result of structural advantages (tax policy, cost of living, quality of life) and adaptive financial services. The city’s ability to attract affluent professionals without the overhead of coastal markets has created a unique sandbox for wealth structuring, where traditional and alternative strategies coexist. Yet the most successful outcomes hinge on three non-negotiables: localized tax expertise, access to exclusive asset classes, and a long-term view of legacy planning. For high-net-worth individuals in Knoxville, the message is clear: the city’s financial ecosystem is sophisticated enough to meet global standards, but only if clients demand it. The firms that thrive in this space are those that reject one-size-fits-all models and instead tailor solutions to the asymmetrical opportunities Knoxville presents—whether it’s leveraging Tennessee’s trust laws or tapping into Appalachian real estate upside. The future of high-net-worth wealth management in Knoxville, TN won’t be defined by how closely it mimics other markets, but by how creatively it redefines them.Comprehensive FAQs
Q: What’s the minimum net worth required to qualify for high-net-worth wealth management in Knoxville?
A: While thresholds vary by firm, most Knoxville-based high-net-worth wealth managers target clients with liquid assets of $1 million+, though some boutique advisors work with $500K–$1M families if they have complex estates or business ownership. The key differentiator isn’t just asset size but financial complexity—e.g., ownership of multiple properties, private business interests, or international exposure.
Q: Are there any tax advantages specific to Knoxville or East Tennessee for HNW individuals?
A: Yes. Beyond Tennessee’s no state income tax, Knoxville residents can benefit from: - Property tax exemptions for primary residences (up to $75K for seniors). - Business entity structuring to mitigate the hall tax (e.g., LLCs vs. S-corps). - Federal Opportunity Zones in nearby counties (e.g., Blount County), offering capital gains deferrals for qualified investments. However, these require proactive planning—many HNW clients overlook nexus risks when holding property in multiple states.
Q: How do Knoxville wealth managers compare to those in Nashville or Atlanta?
A: Knoxville’s high-net-worth wealth management firms tend to offer more personalized service with lower overhead, but may lack the institutional-scale resources of Nashville or Atlanta. The trade-off? Faster decision-making and closer relationships with local CPAs, attorneys, and private bankers. For clients with global assets, Knoxville firms often partner with national platforms (e.g., Northern Trust, Bessemer Trust) to fill gaps.
Q: What alternative investments are Knoxville advisors most active in?
A: Top high-net-worth wealth management firms in Knoxville are increasingly allocating client capital to: 1. Private credit/debt funds (leveraging the Southeast’s commercial real estate demand). 2. Timberland and farmland (Appalachian investments with inflation hedge properties). 3. Fractional ownership in luxury assets (e.g., yachts, fine art, private jets). 4. Impact investing tied to Appalachian revitalization (e.g., opioid crisis recovery, renewable energy). These assets often require minimum commitments of $250K–$500K per deal, but offer illiquidity premiums unattractive in public markets.
Q: Can a Knoxville-based advisor help with international wealth structuring?
A: Absolutely, but with caveats. Many Knoxville firms have partnerships with offshore trustees (e.g., in the Cayman Islands or Switzerland) to facilitate dynasty trusts, private foundations, or non-domiciled structures. However, U.S. reporting requirements (FBAR, FATCA) mean clients must disclose all foreign accounts—a step some overlook. For non-U.S. citizens, Knoxville advisors often collaborate with cross-border tax specialists to optimize gift/estate taxes under Portuguese Golden Visa programs or Malta’s residency-by-investment rules.
Q: How do I vet a high-net-worth wealth manager in Knoxville?
A: Start with these red flags and green flags: - Red flags: Advisors who prioritize commissions over fee-only fiduciary models, lack CPA/attorney collaborations, or don’t disclose conflicts of interest. - Green flags: Firms with CFP®, CFA, or ChFC designations, transparency in fees (e.g., 1% AUM max), and case studies of complex estate or tax planning. Pro tip: Ask about their average client AUM—if it’s < $500K, they may lack the scale to access elite investment opportunities. Top Knoxville firms typically manage $2M–$50M+ per client.
Q: Are there any unique risks for HNW individuals in Knoxville?
A: Yes, primarily in three areas: 1. Cybersecurity: Knoxville’s growing tech scene attracts high-profile targets—HNW individuals with digital assets (crypto, NFTs) or remote businesses must implement multi-factor authentication and cold storage. 2. Natural disaster exposure: Flood zones in East Knoxville and wildfire risks in nearby counties require parametric insurance for high-value properties. 3. Liquidity mismanagement: Many HNW Knoxville residents overallocate to illiquid assets (e.g., farmland, private equity) without emergency cash reserves—a mistake when unexpected expenses arise (e.g., healthcare, legal fees).
Q: What’s the biggest mistake HNW Knoxville residents make with their wealth?
A: Assuming "good enough" is sufficient. The most common pitfall is underestimating complexity—whether it’s ignoring federal estate taxes, failing to diversify beyond real estate, or not documenting a comprehensive succession plan. Knoxville’s affordability can lull clients into a false sense of security; without proactive structuring, even $10M+ estates can face unnecessary tax drag or family conflicts. The antidote? Annual wealth audits with a team of specialists (CPA, estate attorney, wealth manager).
