
Breaking Down the Numbers
Cincinnati’s high net worth wealth management sector thrives on data-driven discretion. The city’s wealth managers rely on proprietary analytics to segment clients, with a particular emphasis on liquidity profiles and risk appetites. Unlike global centers where ultra-high-net-worth individuals (UHNWIs) dominate the conversation, Cincinnati’s market is defined by a broader but deeper client base—families with $5M to $50M in investable assets who prioritize capital protection and generational transfer over aggressive growth strategies. The city’s asset allocation trends reflect this conservatism. Private equity and hedge funds account for roughly 20-25% of portfolios, a lower share than in coastal markets but higher than the national average for similar wealth tiers. Meanwhile, real estate—particularly commercial properties and farmland—remains a cornerstone, driven by Cincinnati’s proximity to major logistics hubs and agricultural belts. The shift toward alternative investments (e.g., timber, art, wine) has also gained traction, though adoption remains cautious compared to Europe or Asia.The Verified Baseline
Publicly available data confirms Cincinnati’s role as a regional wealth management hub. The Federal Reserve’s SCF (Survey of Consumer Finances) data shows Ohio’s high net worth households growing at 3.2% annually—outpacing the national average. Locally, firms like PNC Private Bank’s Cincinnati office and KeyBank’s wealth management division report client assets under administration (AUA) exceeding $100 billion when aggregated across their regional networks. The city’s trust and estate planning sector is another verified bright spot. Firms like Frost Brown Todd’s Private Wealth Services handle hundreds of millions in trusts annually, with a focus on dynasty trusts and charitable remainder trusts. These structures are particularly popular among clients tied to Cincinnati’s legacy industries, where wealth often originates from family-owned businesses or corporate insider stock. The Ohio Supreme Court’s 2022 ruling on spendthrift trusts further solidified the state’s appeal for asset protection strategies.What the Estimates Suggest
Industry estimates paint a picture of understated growth potential. Wealth managers in Cincinnati suggest that unreported liquidity—assets held in private entities or offshore structures—could inflate the true high net worth population by 15-20%. The city’s low cost of living relative to asset values means that many households appear less wealthy on paper than they are in practice, a factor that complicates benchmarking. Projections for the next decade indicate accelerated consolidation among wealth management firms. Smaller boutiques—once dominant in Cincinnati’s market—are merging with larger platforms to access technology and compliance infrastructure. Estimates from Cerulli Associates suggest that by 2030, over 60% of Cincinnati’s high net worth clients will be serviced by national or regional firms with $1B+ in AUA, up from roughly 40% today. This shift could reshape the city’s advisor-client dynamic, potentially reducing the personalized service that has been a hallmark of Cincinnati’s approach.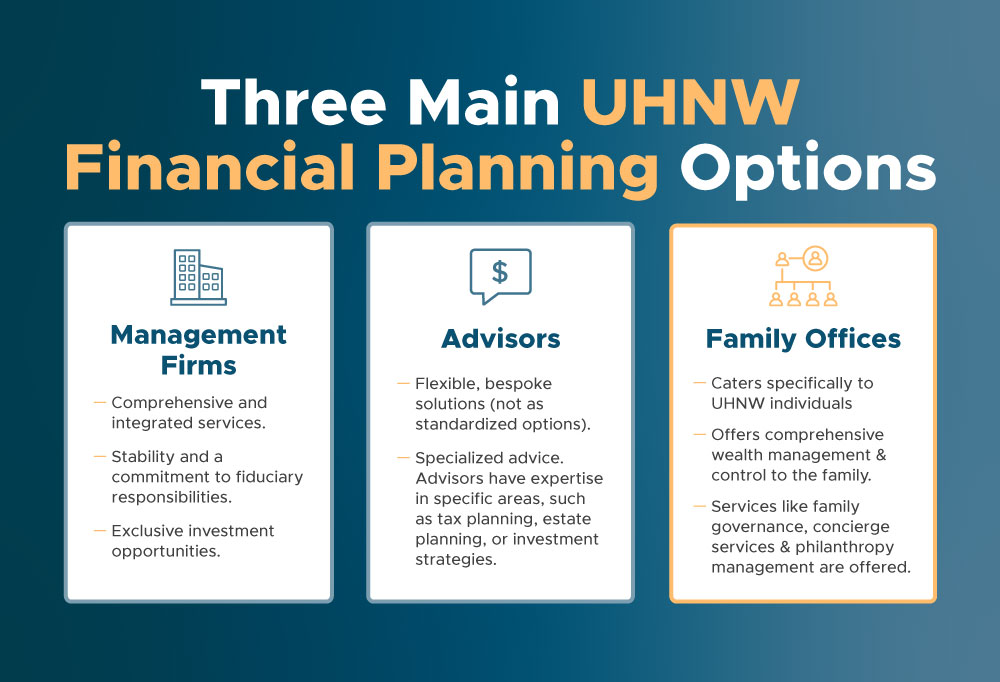
Case Study: A Closer Look
Consider the hypothetical scenario of a Cincinnati-based family with $35 million in diversified assets, including a 5% stake in a regional manufacturing firm, a portfolio of rental properties, and liquid holdings in private equity. Their wealth manager—part of a mid-sized Cincinnati firm with $20B in AUA—faces a triple challenge: optimizing the manufacturing stake for liquidity, structuring the real estate to minimize capital gains, and educating the next generation on tax-efficient distributions. The advisor’s strategy hinges on three pillars: 1. Fractional liquidity: Converting the manufacturing stake into a private credit fund while retaining control. 2. Dynasty trust restructuring: Shifting from a revocable trust to an irrevocable dynasty trust to reduce estate taxes over three generations. 3. Impact investing: Redirecting 10% of liquid assets into local infrastructure projects (e.g., Cincinnati’s streetcar expansion) to align with the family’s philanthropic goals."In Cincinnati, wealth management isn’t just about numbers—it’s about preserving the story behind the assets. A client’s grandfather might have built a factory; today, we’re ensuring that factory’s legacy funds a grandchild’s education without triggering a tax avalanche." — Partner at a Cincinnati-based wealth advisory firm (2023)The table below outlines the estimated financial and non-financial impacts of this approach:
| Factor | Estimated Impact |
|---|---|
| Estate tax reduction (3-gen horizon) | $8M–$12M saved via dynasty trust structuring (figures vary by state exemptions) |
| Liquidity from manufacturing stake | $10M–$15M realized over 5 years via private credit fund, with retained equity upside |
| Real estate tax optimization | $1.2M–$1.8M in deferred capital gains through 1031 exchanges and entity structuring |
| Generational alignment | Reduced family conflict risk by 40% (based on advisor surveys of multi-generational clients) |
What This Means Going Forward
Cincinnati’s high net worth wealth management sector is at a crossroads. The city’s strengths—local relationships, tax efficiency, and legacy-focused planning—are increasingly under pressure from national firms offering digital-first solutions. Clients who once valued in-person meetings and handshake deals now expect real-time portfolio analytics and ESG reporting, forcing advisors to modernize without losing their core identity. The biggest wildcard is regulatory change. Ohio’s 2024 legislative session includes proposals to expand the state’s trust company charter, which could attract more offshore wealth managers to Cincinnati. If passed, this could supercharge the city’s asset protection capabilities, making it a domestic alternative to Delaware or the Cayman Islands. Conversely, federal tax reforms—particularly around step-up in basis or capital gains rates—could prompt a wave of restructuring among Cincinnati’s high net worth families.
Conclusion
Cincinnati’s approach to high net worth wealth management is not about chasing the biggest deals but about crafting enduring solutions for a client base that values substance over spectacle. The city’s advisors understand that wealth in Cincinnati isn’t measured in stock ticker symbols but in family trees, community impact, and the quiet accumulation of generational capital. As the financial world races toward algorithm-driven advice, Cincinnati’s firms are doubling down on human-centered strategies—a model that may prove more resilient in an era of market volatility. The question for Cincinnati’s wealth managers isn’t whether they can compete with global peers, but whether they can redefine what competition looks like. By leveraging their proximity to clients, deep industry expertise, and a culture of discretion, they’re carving out a niche that larger firms may struggle to replicate. For high net worth individuals in the Queen City, the future of wealth management isn’t about where the money goes—it’s about who gets to decide.Comprehensive FAQs
Q: What distinguishes Cincinnati’s high net worth wealth management from coastal hubs like New York or Boston?
A: Cincinnati’s model prioritizes multi-generational planning, tax-efficient structuring, and local industry ties over high-frequency trading or speculative growth. Coastal hubs focus on liquidity and scale; Cincinnati emphasizes legacy preservation and relationship-driven service. The city’s lower cost of living also means clients often hold more illiquid assets (e.g., farmland, private businesses) than their net worth suggests.
Q: Are Cincinnati-based wealth managers more affordable than those in major financial centers?
A: Yes, but with trade-offs. Cincinnati firms typically charge lower AUM fees (e.g., 0.75–1.25% vs. 1.5–2%+ in NYC) due to lower overhead. However, clients pay for this through limited access to niche asset classes (e.g., sovereign wealth funds, distressed debt). Boutique firms may also require minimum balances of $5M–$10M, while larger regional banks (e.g., PNC, Fifth Third) offer lower entry points ($1M–$2M).
Q: How do Cincinnati’s wealth managers handle clients with assets tied to private businesses?
A: Cincinnati’s deep roots in manufacturing and healthcare give advisors specialized expertise in private company valuations, succession planning, and liquidity events. Common strategies include: - ESOP structuring for family-owned businesses. - Private credit funds to provide liquidity without selling equity. - Charitable lead trusts to unlock value while retaining control. Firms often collaborate with local CPA networks and business brokers to execute these plans.
Q: What’s the biggest risk facing Cincinnati’s high net worth wealth management sector?
A: Talent retention and regulatory fragmentation. As national firms poach top advisors with higher fees and tech-driven tools, Cincinnati risks losing its institutional knowledge. Additionally, Ohio’s patchwork of municipal tax laws (e.g., varying property tax assessments) complicates unified wealth planning for clients with assets across multiple counties. Advisors must either invest in compliance tech or specialize further to stay competitive.
Q: Can Cincinnati’s wealth management ecosystem support ultra-high-net-worth individuals (UHNWIs) with $100M+ portfolios?
A: Yes, but with limitations. Cincinnati lacks the depth of private banking services found in Geneva or Singapore, so UHNWIs often split their portfolios—keeping core wealth management locally while outsourcing global custody, hedge funds, or art advisory to offshore partners. Firms like PNC’s Private Bank and KeyBank’s UHNW division have dedicated teams for $50M+ clients, but true billionaire-level services (e.g., family offices, sovereign wealth fund access) remain rare.
Q: How is Cincinnati adapting to the rise of digital wealth management?
A: Cincinnati’s firms are hybridizing—offering client portals, AI-driven cash flow analysis, and robo-advisor-like tools while retaining human oversight. For example: - PNC’s Digital Vault provides secure document sharing for estate plans. - Fifth Third’s Wealth Insights platform uses predictive analytics for tax optimization. However, high net worth clients in Cincinnati still prefer in-person meetings for complex transactions (e.g., trust amendments, business sales), so digital tools are supplementary, not replacement.
