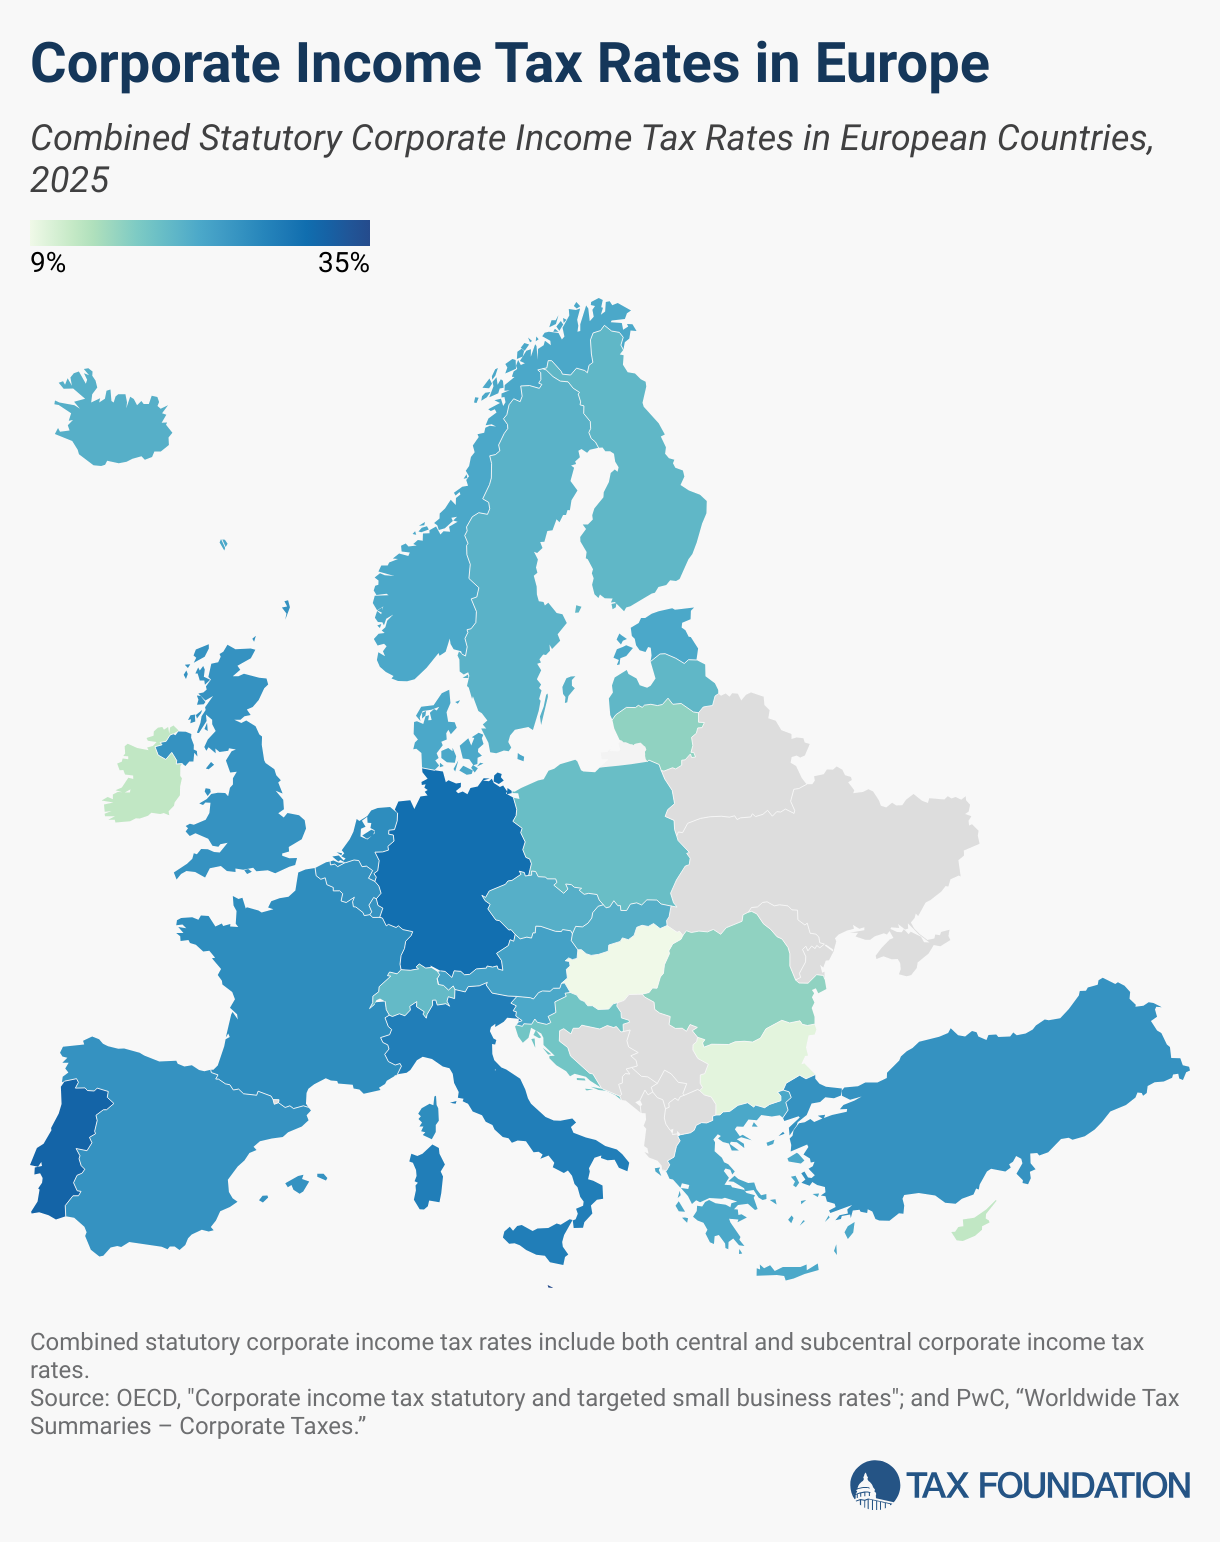
The Complete Overview of Countries by Tax Rates
The global tax landscape resembles a patchwork quilt, where each stitch represents a distinct fiscal philosophy. At one extreme lie the Nordic model—Sweden, Denmark, Norway—where marginal income tax rates hover around 50% to 60%, yet citizens enjoy near-universal healthcare and education. At the other end, tax-neutral jurisdictions like the Cayman Islands or Monaco impose no personal income tax, instead deriving revenue from tourism, licensing fees, or wealth management. The middle ground is where most nations reside: Germany’s progressive scale (up to 45%), Singapore’s territorial system (taxing only local-sourced income), or the UAE’s corporate tax of 9%—a fraction of what European firms pay. What drives these variations? Geography plays a role—landlocked countries often tax more aggressively to compensate for limited trade revenue. So do political priorities: left-leaning governments typically favor higher taxes on wealth and capital gains to fund redistributive policies, while right-leaning administrations prioritize lower rates to stimulate business investment. The digital revolution has further complicated matters, as tech giants exploit loopholes in countries by tax rates with lax enforcement (e.g., Ireland’s 12.5% corporate tax rate, which attracted Apple and Google before EU pressure). Meanwhile, the rise of cryptocurrency has forced nations to scramble—some, like Portugal, tax crypto profits as capital gains; others, like El Salvador, have embraced Bitcoin as legal tender, creating a new fiscal frontier.Historical Background and Evolution
The modern tax system traces back to the 18th century, when Britain’s William Pitt the Younger introduced income tax to fund wars against Napoleon. By the 20th century, progressive taxation became a tool of social engineering, with Keynes advocating higher rates on the wealthy to finance welfare states. Post-WWII, the Bretton Woods system cemented fiscal sovereignty, allowing nations to set their own rates—though with implicit pressure to avoid "unfair" competition. The 1980s Reagan-Thatcher revolution shifted the paradigm, slashing top marginal rates (from 70%+ to 28% in the U.S.) and sparking a global race to the bottom. This trend accelerated in the 1990s as globalization forced governments to compete. The EU’s Harmonisation Directive attempted to standardize VAT rates, but member states carved out exceptions—Luxembourg’s 17% corporate tax (below the EU average) became a magnet for fund managers. Meanwhile, offshore centers like the British Virgin Islands perfected secrecy, enabling tax evasion on a scale that prompted the OECD’s Base Erosion and Profit Shifting (BEPS) project. Today, countries by tax rates reflect not just economic need but geopolitical leverage: the U.S. uses its dollar dominance to pressure allies, while China’s 10% VAT on digital services targets American tech firms.Core Mechanisms: How It Works
Tax systems vary by three axes: progressive vs. flat, territorial vs. worldwide, and direct vs. indirect. Progressive systems (e.g., France, Japan) tax higher incomes at escalating rates, while flat taxes (e.g., Russia, Hong Kong) apply a single rate—often simpler but less redistributive. Territorial taxation (e.g., Singapore, UAE) ignores foreign-sourced income, whereas worldwide systems (e.g., U.S., Germany) demand taxes on global earnings, creating compliance burdens for expats. Indirect taxes—VAT, sales taxes—shift the burden to consumers, while direct taxes (income, property) target earners directly. The mechanics extend beyond rates. Tax treaties prevent double taxation for cross-border workers (e.g., the U.S.-UK treaty limits withholding on dividends). Capital gains taxes vary wildly: New Zealand taxes them at 17% (included in income tax), while the U.S. applies rates up to 20% plus state levies. Wealth taxes (e.g., Spain’s 0.2%–3.75% on fortunes over €700K) are rare but resurface during crises. Meanwhile, tax havens exploit loopholes—Dubai’s "golden visa" offers residency in exchange for property investments, effectively bypassing local taxes. The interplay of these mechanisms determines whether a jurisdiction becomes a magnet for capital or a fiscal drain.Key Benefits and Crucial Impact
Low-tax jurisdictions aren’t just about saving money; they’re about redefining lifestyle possibilities. A family in Belgium, where income tax peaks at 50%, might relocate to Malta, where the same earnings face a 15% flat rate—freeing up funds for private schooling or early retirement. For businesses, the math is equally stark: a U.S. tech firm paying 21% federal corporate tax could shift operations to Estonia (20%) or Poland (9%) and reinvest savings into R&D. The ripple effects are profound. Countries with aggressive tax policies—like Switzerland’s cantonal variations—attract high-net-worth individuals, boosting local real estate and luxury markets. Yet the benefits aren’t unilateral. High-tax nations argue that their systems fund public goods—Denmark’s 55% top rate is offset by free university and healthcare, reducing out-of-pocket costs for citizens. The trade-off is stark: in countries by tax rates, the choice often boils down to liberty vs. security. A Swiss resident might pay dearly for safety and infrastructure, while a Panamanian expat enjoys tropical living with minimal fiscal overhead—but forfeits social safety nets. > "Taxation is the price of civilization." — Oliver Wendell Holmes Jr. > The quote captures the duality: taxes fund the roads, schools, and hospitals that underpin modern life, but they also determine who can afford to participate. The tension between fiscal freedom and collective welfare defines the modern debate over countries by tax rates.Major Advantages
- Capital mobility: Low-tax jurisdictions (e.g., UAE, Singapore) attract foreign investment by offering repatriation of profits without withholding taxes.
- Expat appeal: Digital nomad visas (e.g., Portugal’s D7, Costa Rica’s Rentista) target remote workers with tax incentives tied to residency.
- Corporate competitiveness: Ireland’s 12.5% corporate rate (pre-BEPS adjustments) made it a hub for European HQs, despite EU pressure.
- Wealth preservation: Offshore trusts in jurisdictions like the Bahamas or Liechtenstein shield assets from local taxation and legal claims.
- Innovation incentives: R&D tax credits (e.g., Israel’s 50% rebate, U.S. R&D credit) encourage tech startups to cluster in high-tax nations.

Comparative Analysis
| High-Tax Jurisdictions | Low-Tax/No-Tax Jurisdictions |
|---|---|
|
|
Future Trends and Innovations
The next decade will likely see automated tax enforcement—AI-driven systems like the EU’s DAC7 (mandating digital platform reporting) will shrink loopholes. Meanwhile, crypto taxation is fragmenting: while Malta taxes crypto gains at 18%, the U.S. treats Bitcoin as property (capital gains up to 20%). Carbon taxes (e.g., Sweden’s 120€/ton CO₂ fee) will reshape industrial strategies, pushing manufacturers to low-tax green energy hubs like Iceland or Norway. Geopolitical shifts will also matter. The U.S. Global Minimum Tax (15%) aims to curb profit-shifting, but compliance will be uneven—emerging markets may resist. Meanwhile, tax competition among cities is intensifying: Berlin’s 42% top rate contrasts with Hamburg’s 45%, while U.S. states like Texas (0% income tax) lure firms from California (up to 13.3%). The result? A two-tiered world: high-tax nations with strong social contracts, and low-tax zones where mobility is the primary currency.
Conclusion
The debate over countries by tax rates is no longer about absolutes but about trade-offs. A software developer in Berlin might sacrifice disposable income for world-class public transit, while a trader in Dubai prioritizes tax-free earnings over healthcare access. Governments, too, must balance revenue needs with global competitiveness—Finland’s recent corporate tax hike (20% to 24%) risks pushing firms to Estonia. The lesson? Fiscal policy is a moving target, shaped by technology, migration, and geopolitics. For individuals, the takeaway is clarity: tax rates are not static. Portugal’s NHR regime expires in 2024; the UAE’s corporate tax debuts in 2023. Staying ahead requires monitoring jurisdictional shifts, leveraging tax treaties, and understanding that no system is permanent. The future belongs to those who navigate the system—not those who ignore it.Comprehensive FAQs
Q: Which country has the highest income tax rate?
A: Denmark holds the record with a top marginal rate of 55.87%, including local taxes. Sweden follows at 52.4%, while Belgium’s peak reaches 50%. These rates are offset by extensive public services, but expats often seek lower alternatives.
Q: Are tax havens illegal?
A: No, but they’re heavily regulated. Jurisdictions like the Cayman Islands or Luxembourg are legally compliant but face scrutiny under OECD blacklists for secrecy or aggressive tax avoidance. The U.S. and EU crack down on "harmful tax competition," though enforcement varies.
Q: Can I avoid taxes by moving to a low-tax country?
A: Legally, yes—but with caveats. Tax treaties prevent double taxation, and residency rules (e.g., 183 days/year) define liability. The U.S. taxes citizens worldwide, while the UK’s statutory residence test can trap expats. Always consult a cross-border tax advisor.
Q: How do corporate tax rates affect job creation?
A: Lower rates (e.g., Ireland’s 12.5%) attract investment but may reduce revenue for public services. High rates (e.g., France’s 25%) fund welfare but can deter businesses. The Laffer Curve suggests a tipping point—beyond which cuts spur growth, but below which revenue collapses.
Q: What’s the best tax regime for digital nomads?
A: Portugal’s NHR (10-year tax holiday on foreign income) and Costa Rica’s Rentista (€2,500/month passive income visa) are top picks. The UAE’s remote work visa offers 0% tax but lacks social benefits. Research residency requirements—some visas mandate local bank accounts or language tests.
Q: How do wealth taxes work?
A: Wealth taxes (e.g., Spain’s 0.2%–3.75% on assets over €700K) target net worth, not income. France abolished its wealth tax in 2018 but replaced it with a real estate tax on high-value properties. Critics argue they discourage investment; proponents say they fund inequality reduction.
Q: Can I structure my finances to pay less tax?
A: Yes, through legal optimization: offshore trusts (e.g., in the British Virgin Islands), holding companies in low-tax zones, or pension contributions (e.g., Portugal’s Golden Visa ties residency to €250K+ investments). Aggressive schemes (e.g., CFC rules targeting controlled foreign corporations) risk penalties.
Q: What’s the future of global tax policy?
A: Automation (AI audits, blockchain tracking) will reduce evasion. The OECD’s Pillar Two (15% global minimum) aims to curb profit-shifting, but compliance will be uneven. Carbon taxes and digital service levies (e.g., EU’s 3% tax on Big Tech) will reshape corporate strategies—pushing firms to adapt or relocate.
