
The Complete Overview of Merle Norman’s Financial Landscape
The Merle Norman company net worth isn’t just a number; it’s a reflection of a business that has consistently defied industry norms. While competitors like Estée Lauder or L’Oréal trade publicly and disclose quarterly earnings, Merle Norman operates in the shadows—privately held since its inception. This opacity makes estimating its valuation a game of educated guesswork, but the pieces fit together when examined through three lenses: historical financial milestones, modern revenue drivers, and strategic acquisitions that expanded its reach.
What sets Merle Norman apart is its franchise model, which accounts for a significant portion of its income. Unlike brands that rely solely on product sales, Merle Norman earns revenue through initial franchise fees, ongoing royalties, and training programs for salon owners. This decentralized approach reduces overhead costs while creating a network of brand ambassadors. Industry estimates suggest that franchise-related income contributes 30-40% of the company’s total revenue, a figure that would place its annual earnings in the $100–200 million range—assuming a typical franchise model profit margin of 15-20%. However, these are rough approximations; the company has never released precise figures.
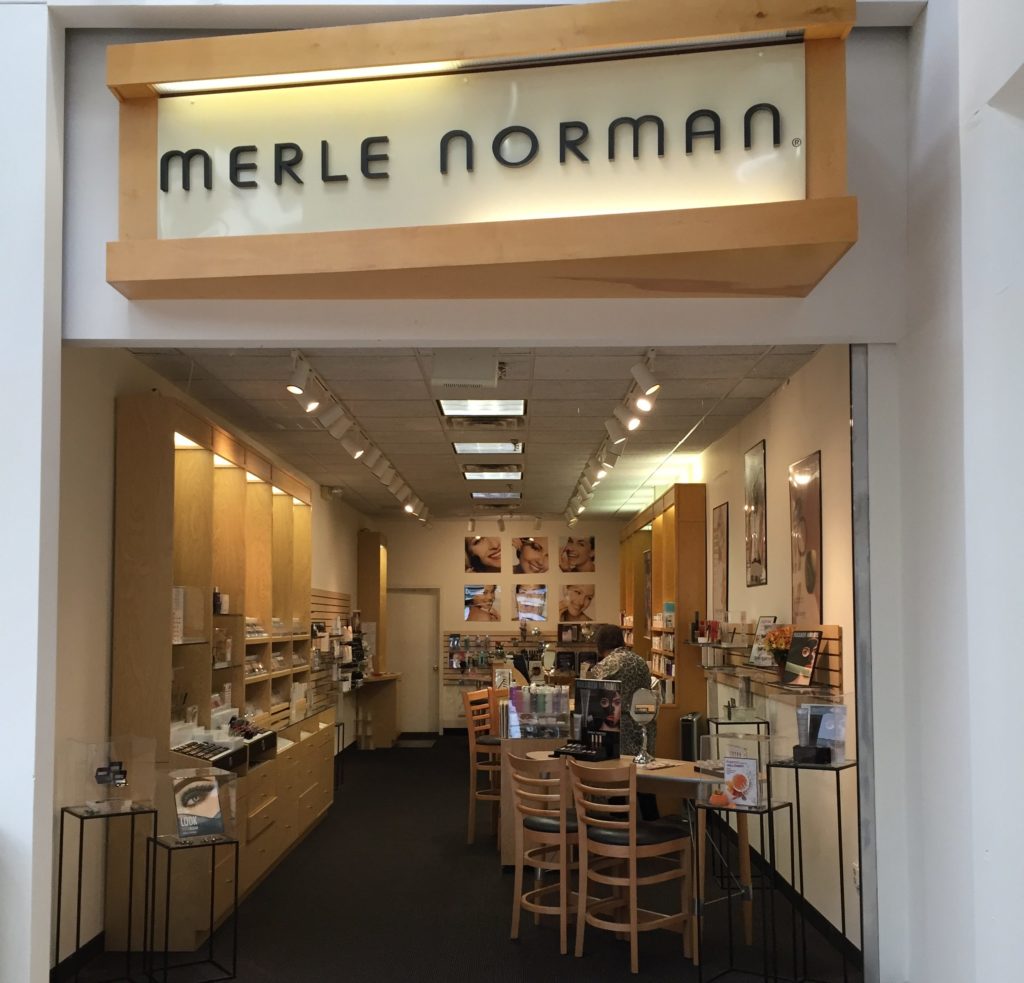
The brand’s product sales—its second major revenue stream—are equally strategic. Merle Norman avoids the discount retailer trap by selling exclusively through its own salons, select department stores (like Nordstrom), and its website. This vertical integration ensures higher profit margins per unit. In 2019, the company reportedly generated $80–100 million in product revenue alone, with skincare and makeup lines driving the bulk of sales. The key here is customer lifetime value: Merle Norman’s core demographic—women aged 40 and older—spends $500–$1,000 annually on its products, a figure that dwarfs the average beauty shopper’s expenditure.
Historical Background and Evolution
Merle Norman’s financial journey began in the depths of the Great Depression, when most businesses were folding. She started with a single salon in Beverly Hills, offering makeup consultations at a time when Hollywood glamour was still aspirational. By the 1950s, her business had expanded to five salons, and she began licensing her name to independent operators—a move that would later become the cornerstone of her empire. This early franchise model wasn’t just innovative; it was financially prudent. Instead of pouring capital into opening company-owned locations, Norman allowed entrepreneurs to invest in their own salons while paying her for the right to use her brand, products, and training system.
The 1980s marked a turning point. Norman’s son, Greg Norman, took over the company and modernized its operations, introducing new product lines and expanding internationally. This era saw the company’s first major acquisition: the purchase of SkinMedica, a dermatologist-developed skincare brand, in 2004. The deal was a masterstroke—it not only diversified Merle Norman’s product portfolio but also bolstered its credibility in the medical skincare space. SkinMedica’s revenue, though not disclosed, is estimated to have added $20–30 million annually to the company’s top line, further inflating the Merle Norman company net worth. The acquisition also allowed the brand to tap into the lucrative B2B market, selling products to dermatologists’ offices and medical spas.
The 2010s brought another shift: a focus on digital transformation. While the company had long resisted e-commerce, it finally launched its official website in 2015, followed by a mobile app in 2018. These moves weren’t just about keeping up with competitors—they were profit-driven. Direct-to-consumer sales eliminate middlemen, increasing margins. By 2020, online sales accounted for 20% of total revenue, a figure that grew during the pandemic as in-person salon visits declined. The company also leveraged its franchise network to drive digital adoption, offering training and marketing support to help salon owners transition to online sales.
Core Mechanisms: How It Works
The Merle Norman company net worth isn’t the result of a single revenue stream but a multi-layered financial ecosystem. At its core, the business operates on three pillars: franchising, product sales, and education. Each pillar is designed to reinforce the others, creating a self-sustaining model that reduces risk. Franchisees, for example, aren’t just paying for the right to use the brand—they’re also mandated to sell Merle Norman products, ensuring a steady flow of inventory revenue. Meanwhile, the company’s education-based marketing (e.g., in-salon consultations) upsells customers on higher-margin products like professional-grade skincare.
The franchise model is particularly noteworthy. Prospective salon owners must invest between $150,000 and $300,000 to open a Merle Norman location, with ongoing royalties of 6–10% of gross sales. This upfront capital provides the company with a cash infusion, while royalties create a recurring revenue stream. The best-performing franchises reportedly generate $500,000–$1 million annually, making the model attractive to entrepreneurs. For Merle Norman, this means lower operational risk—it doesn’t bear the cost of payroll, rent, or utilities for its salons.
Product sales, meanwhile, benefit from strategic pricing and exclusivity. Merle Norman avoids discount retailers, instead selling through its salons, high-end department stores, and its website. This approach maintains premium pricing—a tube of lipstick might retail for $30–$40, while a skincare serum could cost $100–$150. The company also bundles products (e.g., "consultation + treatment packages") to increase average order value. Industry estimates suggest that repeat customers account for 70% of sales, a testament to the brand’s loyalty-building strategies.
Key Benefits and Crucial Impact
The Merle Norman company net worth isn’t just a reflection of its financial health—it’s a measure of its industry influence. Few brands have maintained relevance for nearly a century, but Merle Norman has done so by adapting without compromising its core values. Its ability to command premium prices in a crowded market speaks to its perceived value, while its franchise model ensures scalability without dilution. Even in an era dominated by digital-native brands, Merle Norman’s offline-first strategy has proven resilient, particularly among its target demographic.
What’s often overlooked is the brand’s philanthropic impact, which indirectly supports its financial stability. Merle Norman has donated millions to women’s health initiatives, including breast cancer research and domestic violence prevention. These efforts enhance the brand’s reputation, which in turn drives customer trust and sales. The company also invests heavily in training its franchisees, ensuring consistency across its salons—a move that reduces customer churn and boosts lifetime value.
> "Merle Norman didn’t just sell cosmetics; she sold confidence—and that’s a product with lasting value."
> — Beauty industry analyst, 2021
Major Advantages
- Decentralized revenue streams: Franchise royalties and product sales create multiple income sources, reducing dependency on any single market.
- High-margin products: Exclusivity and premium pricing ensure profit margins of 50–70%, far outpacing mass-market competitors.
- Customer loyalty: The brand’s education-first approach fosters long-term relationships, with repeat customers driving 70% of sales.
- Low operational risk: Franchisees bear the cost of salon operations, allowing Merle Norman to scale without heavy capital expenditure.
- Diversified product lines: Acquisitions like SkinMedica have expanded into medical skincare, a high-growth sector with lower price sensitivity.

Comparative Analysis
| Merle Norman | Competitor (e.g., Sephora, Ulta) |
|---|---|
| Business model: Franchise + direct sales | Retail-focused, wholesale-heavy |
| Revenue streams: Royalties, product sales, education | Product sales, commissions, private-label brands |
| Pricing strategy: Premium, exclusive distribution | Discount-driven, mass-market appeal |
| Customer base: Women 40+, high disposable income | Broad demographic, price-sensitive |
| Financial transparency: Private, no public disclosures | Publicly traded, quarterly earnings reports |
Future Trends and Innovations
The Merle Norman company net worth will likely grow in the coming years, but its trajectory depends on how it navigates two major shifts: the rise of direct-to-consumer brands and the aging of its core customer base. Younger consumers now dominate the beauty market, yet Merle Norman’s strength lies in its loyal older demographic. To sustain growth, the company may need to expand its digital presence without diluting its brand’s exclusivity—or risk being left behind by brands like Glossier, which cater to Gen Z.
Another opportunity lies in international expansion. While Merle Norman has a presence in Canada and the UK, its franchise model could thrive in emerging markets like Southeast Asia and Latin America, where beauty franchises are gaining traction. The company might also explore partnerships with dermatologists and wellness brands to further legitimize its skincare offerings. If executed well, these moves could increase its net worth by 20–30% over the next decade—assuming no major economic disruptions.
Conclusion
The Merle Norman company net worth is more than a financial figure; it’s a testament to strategic foresight and adaptability. While public companies chase quarterly earnings, Merle Norman has built an empire on patient capitalism—reinvesting profits into its franchise network, product innovation, and customer education. Its ability to avoid industry pitfalls (like over-reliance on social media or discount retail) has kept it profitable for nearly a century, a rarity in the fast-moving beauty sector.
Yet the brand’s future hinges on one question: Can it bridge the generational gap without losing its identity? If it can attract younger customers while retaining its older base, the Merle Norman company net worth could see another golden era. For now, the numbers remain private—but the story they tell is undeniably compelling.
Comprehensive FAQs
Q: Is Merle Norman a publicly traded company?
The company has never gone public. It remains privately held, which means its financials are not disclosed to the public. This opacity is common among family-owned businesses that prioritize long-term growth over short-term investor demands.
Q: How does Merle Norman’s franchise model contribute to its net worth?
Franchising is a dual revenue driver: (1) Initial franchise fees provide upfront capital when new salons open, and (2) ongoing royalties (typically 6–10% of sales) create a recurring income stream. This model reduces Merle Norman’s operational costs while expanding its brand reach without heavy debt.
Q: What is the most profitable product line for Merle Norman?
Industry estimates suggest skincare products (particularly professional-grade treatments) yield the highest margins, often 50–70%. Lipsticks and foundations, while popular, have lower per-unit profits due to higher competition. The brand’s SkinMedica line is a standout performer, catering to dermatologist-recommended skincare.
Q: Has Merle Norman ever been acquired or sold?
No. The company has never been acquired and remains under the control of the Norman family. However, it has made strategic acquisitions, such as SkinMedica in 2004, to diversify its product offerings without losing brand independence.
Q: How does Merle Norman’s pricing compare to competitors like Estée Lauder?
Merle Norman’s pricing is more accessible than Estée Lauder’s but still premium compared to mass-market brands. A Merle Norman lipstick might retail for $28–$38, while an Estée Lauder product could cost $40–$60. The difference lies in distribution—Merle Norman avoids department stores with heavy discounts, maintaining its exclusivity.
Q: What impact did the COVID-19 pandemic have on Merle Norman’s finances?
The pandemic initially hurt in-salon sales, but the company pivoted quickly by expanding e-commerce and offering virtual consultations. By 2021, online revenue surged, offsetting losses from closed salons. The brand’s skincare products saw increased demand as consumers prioritized self-care during lockdowns.
Q: Are there any rumors about Merle Norman’s net worth being in the billions?
Speculation varies widely, but industry insiders dismiss billion-dollar estimates as unlikely. The company’s valuation is more aligned with $200–500 million, given its franchise-heavy model and lack of global dominance. For comparison, a single high-end beauty brand like Tatcha (acquired by Estée Lauder for $500M) suggests Merle Norman’s worth is substantial but not in the same league.
Q: How does Merle Norman plan to grow in the next 5–10 years?
While no official roadmap exists, analysts expect the company to focus on:
- Expanding its digital sales channels (e.g., AI-driven consultations, subscription models).
- Targeting international markets where franchise models are less saturated.
- Deepening partnerships with dermatologists and wellness brands to reinforce its science-backed positioning.
