
The Short Answers
- The median wealth united states (2023) is $188,200 for white households vs. $24,100 for Black households.
- Homeownership drives 68% of wealth for white families but only 4% for Black families due to redlining history.
- Student debt erases $35,000+ in median wealth for borrowers compared to non-borrowers.
- The top 1% own 35% of all U.S. wealth, while the bottom 50% own 3.3%.
- Wealth gaps widen after age 50, as Boomers inherit assets while younger generations struggle with costs.
- Policy fixes—like child tax credits—can move the needle, but structural racism in housing and wages remains the core issue.
Deep Dive: The Full Picture
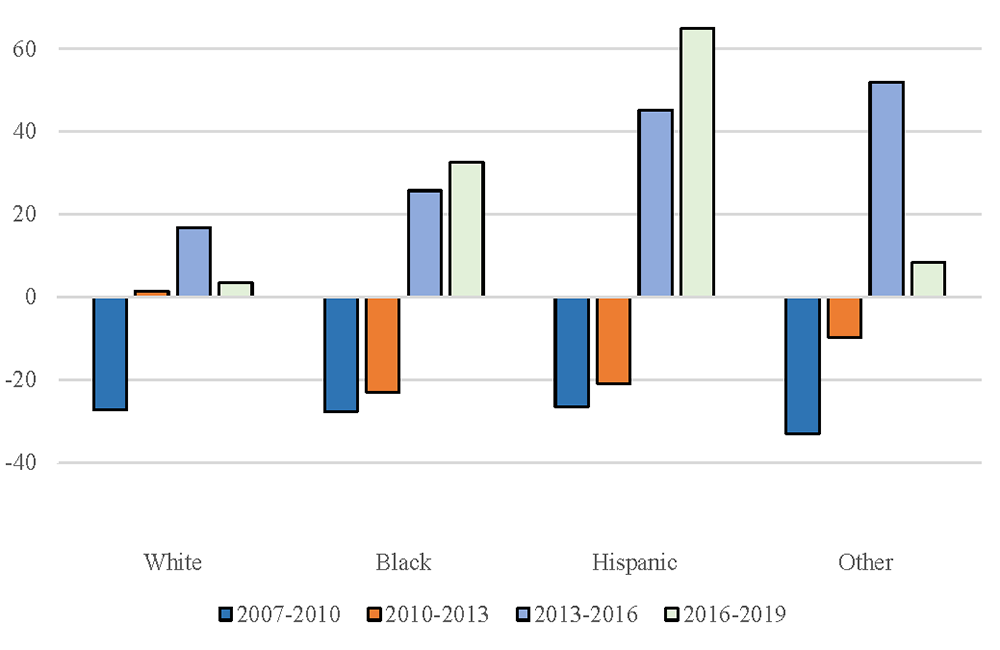
The median wealth united states is a moving target, shaped by crises and policy shifts. The Great Recession of 2008 wiped out $16 trillion in household wealth, and recovery was uneven: white families regained losses within six years, while Black and Latino families remained 20% below pre-crisis levels a decade later. The 2020 COVID-19 crash repeated this pattern. Stock market gains during lockdowns enriched those with 401(k)s and brokerage accounts, while gig workers and service employees saw savings evaporate. The median wealth united states in 2021 surged 28% year-over-year—primarily because the top 10% saw their portfolios swell by $11 trillion, while the bottom 90% gained just $1.1 trillion. Wealth isn’t just about money in the bank. It’s about intergenerational transfer: inheritances, family homes, and social networks that open doors. A 2022 Brookings study found that 60% of wealth for white families comes from inherited assets or gifts, compared to 10% for Black families. This isn’t charity—it’s the accumulated advantage of centuries of policy. The Homestead Act of 1862, for example, granted 160 acres to white settlers while excluding Black Americans until 1946. Even today, FHA loans—a key wealth-building tool—were denied to Black borrowers until the 1960s, leaving a $156,000 gap in home values between white and Black neighborhoods today.The Context You Need
The median wealth united states is often discussed in isolation, but its true story lies in the wealth-to-income ratio. In 1989, wealth was 6.5 times income; by 2020, it had ballooned to 8.5 times. This divergence explains why wage growth feels stagnant: most Americans aren’t earning more—they’re losing ground to asset inflation. The median wealth united states also obscures liquidity traps. A family with a $200,000 home might have $188,200 in net worth, but if they’re upside-down on their mortgage or lack emergency savings, that wealth is illusory. Geography compounds these issues. The median wealth united states in San Francisco is $3.1 million, while in Mississippi it’s $72,000. Rural areas suffer from capital flight: banks, hospitals, and manufacturing jobs disappear, leaving families with no path to build wealth. Even within cities, school district zoning determines future earnings. A child in a top-tier NYC public school district is three times more likely to attend college than one in a struggling district—directly impacting their ability to accumulate wealth.The Mechanics
The median wealth united states is propped up by three pillars: homeownership, retirement accounts, and inheritance. Homeownership is the single biggest wealth driver—white families with college degrees have a net worth 12 times higher than those without, largely due to home equity. Retirement accounts (401(k)s, IRAs) benefit those with employer matches and high incomes; 60% of workers lack access to a retirement plan, and among low-wage earners, only 30% participate. Inheritance is the wild card: $84 billion is passed down annually, but 90% of that goes to the top 10% of earners. Tax policy distorts these mechanics further. Capital gains taxes favor long-term investors, while payroll taxes hit wage earners. The median wealth united states is also inflated by student debt: borrowers have $35,000 less in median wealth than non-borrowers, even when controlling for income. The wealth gap isn’t just about money—it’s about risk tolerance. A white family can take a $500,000 mortgage with confidence; a Black family with the same income may be denied or priced into a predatory subprime loan, locking them into a cycle of debt.Details That Change the Picture
The median wealth united states hides asset poverty: households with zero or negative net worth. In 2022, 25% of Americans had no liquid assets—meaning a single emergency (car repair, medical bill) could push them into debt. This isn’t just a personal failure; it’s a policy failure. The U.S. has no universal childcare, no paid family leave, and no wealth floor—unlike countries where even low-income families hold $10,000+ in assets due to social safety nets. The racial wealth gap is the most glaring outlier. A Black family would need 228 years to close the gap at current rates of wealth accumulation. The median wealth united states for Native American households is $15,000—lower than any other group. These numbers aren’t anomalies; they’re the result of explicit policies. The 1935 Social Security Act excluded farm and domestic workers—90% of whom were Black—leaving them without retirement security. Even today, Alaska Native corporations hold $1.3 trillion in assets, while tribal nations struggle with $10 billion in unmet infrastructure needs."Wealth inequality isn’t a bug in the system—it’s the system. The rules are written to protect asset holders, not asset builders." — Darrick Hamilton, economist & author of Zer0 to One in Wealth
| Metric | Impact on Median Wealth |
|---|---|
| Homeownership Rate (White vs. Black) | 74% vs. 44% → $250K wealth gap |
| Student Debt Burden | Borrowers: $35K less in median wealth |
| Inheritance Probability (Top 10% vs. Bottom 50%) | 60% vs. 5% → $200K+ lifetime advantage |
Conclusion
The median wealth united states is a fractured mirror. It reflects prosperity for some, precarity for others, and a system designed to preserve that divide. The data isn’t neutral—it’s a ledger of historical exclusion and modern policy choices. Closing the gap requires more than tinkering at the edges. It demands wealth redistribution (like the Baby Bonds proposal), housing reform (ending exclusionary zoning), and taxation that punishes hoarding rather than incentivizing it. Yet the conversation often stalls at moral outrage without structural solutions. The median wealth united states won’t change until wealth itself is treated as a public good—not a private trophy. Until then, the numbers will keep telling the same story: opportunity is not equally distributed, and neither is wealth.Comprehensive FAQs
Q: How does the median wealth united states compare to other developed nations?
The U.S. has higher wealth inequality than most peer countries. In Canada, the top 10% hold 40% of wealth; in Germany, it’s 30%. The median wealth united states is also lower than in Nordic nations when adjusted for cost of living—despite higher GDP per capita—due to weaker social safety nets.
Q: Can the racial wealth gap ever be closed?
Historically, no—but targeted policies can accelerate progress. The 1960s Fair Housing Act reduced segregation, and HBCU endowments have grown to $1.2 billion, helping Black families build wealth. Proposals like Baby Bonds (giving every child at birth a $1,000+ account) could cut the gap by 30% in 50 years if paired with housing and tax reforms.
Q: Why does homeownership matter so much for wealth?
Homes are forced savings accounts. Renters lose $10,000/year to landlords; owners build equity. White families benefit from appreciation (homes now worth 3x their 1970 value) and low-interest mortgages. Black families, excluded from FHA loans until the 1960s, missed $156,000 in cumulative home value—a gap that persists today.
Q: Does the median wealth united states include debt?
Yes. Net worth = assets (home, stocks, cash) minus debts (mortgage, student loans, credit cards). A family with a $300K home and $250K mortgage has $50K in net worth—far below the median. Student debt is the biggest wealth killer: borrowers have $35K less in median wealth than non-borrowers, even at similar incomes.
Q: How do inheritance and trusts affect wealth inequality?
90% of intergenerational wealth transfers go to the top 20%. The median wealth united states for heirs is $2.1 million vs. $12K for non-heirs. Dynasty trusts let families shield assets from taxes for generations, while estate taxes (which kick in at $13.6 million) ensure only the ultra-wealthy pay. This perpetuates inequality—a child born to parents with $100K in savings starts at $0 unless they inherit.
Q: What’s the biggest myth about the median wealth united states?
The myth that "hard work alone will fix it." Wealth is 80% inherited, not earned. CEO pay has grown 1,300% since 1980, while worker wages are up 12%. The median wealth united states is not a meritocracy—it’s a rigged game where the deck is stacked at birth.
