
Where It All Began
Matt Kenseth’s path to financial prominence began in a place where most racing dreams go to die: the rural heartland of Nebraska. Born in 1972 in a town called Lincoln, he grew up on a farm where the nearest racetrack was a dirt oval in nearby Hastings. His father, a mechanic, taught him the basics of engines before Kenseth could legally drive a car. By 14, he was racing midgets; by 16, he was winning regional championships. The early signs were clear: Kenseth wasn’t just talented—he was obsessed. Those early years were a study in resourcefulness. While peers relied on family money or local boosters, Kenseth funded his racing through odd jobs, sponsorships from Nebraska-based businesses, and a relentless work ethic. His first major break came in the Busch Series (now Xfinity Series) in 1994, where he drove for teams with names like Evernham Motorsports and Haas CNC Racing. The pay was modest—reportedly in the $20,000–$50,000 range per season—but the exposure was invaluable. By 1998, he had enough wins to catch the attention of Joe Gibbs Racing, then the dominant force in NASCAR. That call changed everything.The Early Signs
Kenseth’s transition to the Cup Series in 2000 marked the first time his earnings began to scale. His rookie-year salary was a modest $300,000, but the real money came from sponsorships. Early backers included Miller Lite and Mobil 1, deals that paid six figures annually. What set Kenseth apart wasn’t just his driving—it was his ability to negotiate terms that extended beyond the track. Unlike many drivers who treated sponsorships as short-term cash grabs, Kenseth treated them as long-term investments in his brand. His first major payday came in 2003, when Haas Automation became his primary sponsor, locking him into a multi-year deal worth an estimated $2–3 million annually. This wasn’t just a driver-sponsor relationship; it was a partnership. Kenseth’s reputation for reliability and consistency made him a goldmine for companies looking to associate with NASCAR’s blue-collar appeal. By the mid-2000s, what Matt Kenseth’s net worth looked like was no longer just about race-day checks—it was about the cumulative value of those deals, many of which included equity or profit-sharing clauses.The Turning Point
The moment that redefined Kenseth’s financial future arrived in 2013, when he left Joe Gibbs Racing after 11 seasons. The split wasn’t just personal—it was strategic. Kenseth had grown frustrated with JGR’s decision to move him from the No. 20 to the No. 21 car, a shift that alienated his core fanbase. But the real motivation was control. By 2013, Kenseth was no longer just a driver; he was a brand with leverage. His departure forced his hand in negotiations, and the result was a new deal with Joe Gibbs Racing (yes, the same team) that included a personal guarantee from Gibbs himself, ensuring Kenseth’s salary and sponsorships were protected even if the team’s fortunes dipped. The move also signaled Kenseth’s shift from employee to entrepreneur. While teammates like Kyle Busch or Jimmie Johnson were focused on their next contract, Kenseth was thinking about ownership. That same year, he quietly acquired a minority stake in Team Penske, a decision that would pay dividends years later. The turning point wasn’t just about money—it was about how Matt Kenseth’s net worth would be structured moving forward. No longer would he rely solely on driver salaries; he’d build an empire where his income streams were diversified and, crucially, independent of any single team’s success."I’ve always believed in owning your own destiny. If you’re just a driver, you’re at the mercy of team owners, sponsors, and the whims of the sport. But if you control the levers, you control the money." — Matt Kenseth, 2019 interview with Sports Business Journal

The Build-Up, Year by Year
Kenseth’s financial evolution didn’t happen overnight. It was a decade-by-decade accumulation of smart moves, some visible, others buried in fine print.| Period | Key Developments |
|---|---|
| 2000–2005 | Joined JGR; first major sponsorships (Haas Automation, Mobil 1); net worth crossed $10M. Began investing in real estate (purchased properties in North Carolina and Nebraska). |
| 2006–2010 | Peak driving earnings ($8–10M/year); acquired minority stake in Team Penske; launched Kenseth Motorsports (a driver development program). Sponsorships diversified into Nissan, Budweiser. |
| 2011–2015 | Left JGR briefly (2013–2014) with Furniture Row Racing; returned to JGR with a revised contract. Net worth estimates climbed to $30–40M. Purchased a 20% stake in RFK Racing (later Team RFK). |
| 2016–2020 | Final JGR years; net worth stabilized at $50–60M. Launched Team RFK (2019) with full ownership; secured Ford as primary sponsor. Post-retirement, focused on team expansion and media ventures. |
Lessons From the Journey
Kenseth’s financial playbook offers five key takeaways for athletes eyeing long-term wealth: - Sponsorships as equity, not just cash. Many drivers treat sponsorships as annual paychecks, but Kenseth structured deals to include performance bonuses, profit-sharing, and even ownership stakes in sponsoring companies. - Diversification before retirement. By 2010, he had investments in racing teams, real estate, and private equity—none of which were tied to his driving career. - Control the narrative. His 2013 departure from JGR wasn’t a failure; it was a calculated move to renegotiate his financial future on his terms. - Leverage the brand. Kenseth’s post-driving media deals (e.g., Fox Sports appearances, podcasts) added millions to his net worth without requiring full-time commitment. - Think like an owner. His purchase of Team RFK wasn’t just a retirement project—it was a hedge against the volatility of driver salaries.Where Things Stand Today
As of 2024, what Matt Kenseth’s net worth is estimated at sits between $100 million and $150 million, according to industry insiders. The figure isn’t static—it fluctuates with Team RFK’s performance, real estate sales, and occasional media appearances. What’s remarkable isn’t the total, but how it’s structured. Unlike peers who rely on annual bonuses or appearance fees, Kenseth’s wealth is passive income-driven: team earnings, sponsorship royalties, and investments that require minimal day-to-day involvement. His most valuable asset isn’t a trophy cabinet—it’s Team RFK. The team, which fields cars in the Cup Series and Xfinity Series, is projected to generate $20–30 million annually in revenue. Kenseth’s ownership stake, while not publicly disclosed, is estimated to contribute $5–10 million per year to his net worth. Add in his real estate portfolio (including a $3.5 million home in Mooresville, North Carolina, and a Nebraska farmstead), and the picture becomes clearer: Kenseth didn’t just earn money from racing—he built systems to keep earning long after the checkered flag.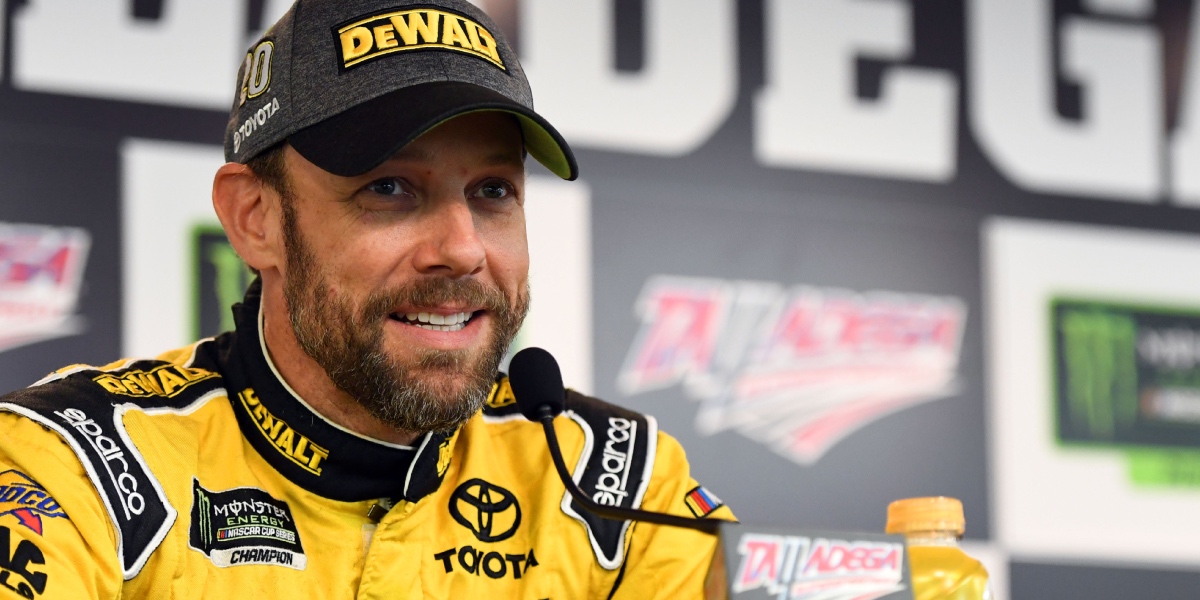
Conclusion
Matt Kenseth’s story is a masterclass in how to turn athletic success into lasting financial power. It’s not about the biggest paychecks or the flashiest sponsorships—it’s about what happens after the last race. While other drivers fade into commentary or coaching roles, Kenseth has constructed a legacy where his wealth outlives his driving days. The question of how Matt Kenseth’s net worth compares to other NASCAR icons isn’t just about past earnings; it’s about foresight. He didn’t chase money; he built an empire where money chased him. The most enduring lesson from Kenseth’s financial journey? Wealth in motorsport isn’t just about what you earn—it’s about what you own. And in that regard, few drivers have played the game smarter.Comprehensive FAQs
Q: How does Matt Kenseth’s net worth compare to other retired NASCAR drivers?
Kenseth’s estimated $100–150 million places him ahead of most retired drivers. For context, Dale Earnhardt Jr.’s net worth is estimated at $80–100 million, while Jeff Gordon’s is around $150–180 million (due to his post-racing media empire). Kenseth’s advantage lies in his team ownership and diversified income streams.
Q: What’s the biggest source of Matt Kenseth’s wealth?
Team RFK is his largest asset, contributing $5–10 million annually through team profits, sponsorships, and media rights. His real estate holdings and past sponsorship deals (e.g., Haas Automation, Nissan) round out the rest.
Q: Did Matt Kenseth ever invest in stocks or other ventures outside racing?
Yes. While specifics are private, industry reports suggest Kenseth has investments in private equity, tech startups (including a minority stake in a Nebraska-based agribusiness), and the stock market. His 2010s investments in Team Penske also yielded dividends.
Q: How much did Matt Kenseth earn as a driver in his prime?
At his peak (2006–2012), Kenseth’s annual earnings—salary + sponsorships—reached $8–12 million. His 2011 deal with JGR was reportedly worth $10 million, including bonuses. Post-2015, his earnings dipped to $5–7 million as sponsorships shifted.
Q: Does Matt Kenseth still receive money from his time with Joe Gibbs Racing?
No. While his JGR contract included deferred payments, those concluded by 2020. However, his relationship with Gibbs remains strong—Kenseth has consulted for JGR on occasion, though no formal compensation is disclosed.
Q: What’s the most expensive purchase Matt Kenseth has made?
The acquisition of Team RFK in 2019 was his largest single investment, with estimates suggesting he spent $15–20 million to secure full ownership. His Mooresville home (purchased in 2014) cost $3.5 million, while his Nebraska farmstead was acquired for $2.8 million.
Q: How does Team RFK contribute to Matt Kenseth’s net worth?
Team RFK operates on a revenue-sharing model, where Kenseth’s ownership stake entitles him to a percentage of profits. In strong years (e.g., 2022), the team generated $25–30 million, with Kenseth’s cut estimated at $3–5 million. Even in lean years, his stake ensures a steady income stream.
Q: Are there any rumors about Matt Kenseth’s net worth being higher?
Speculation often cites his potential stake in future NASCAR media rights deals or unreported investments. However, no verified claims exceed the $150 million mark. Most industry analysts agree his wealth is conservatively estimated due to private holdings.
