The Complete Overview of Mark Morse and The Villages’ Financial Empire
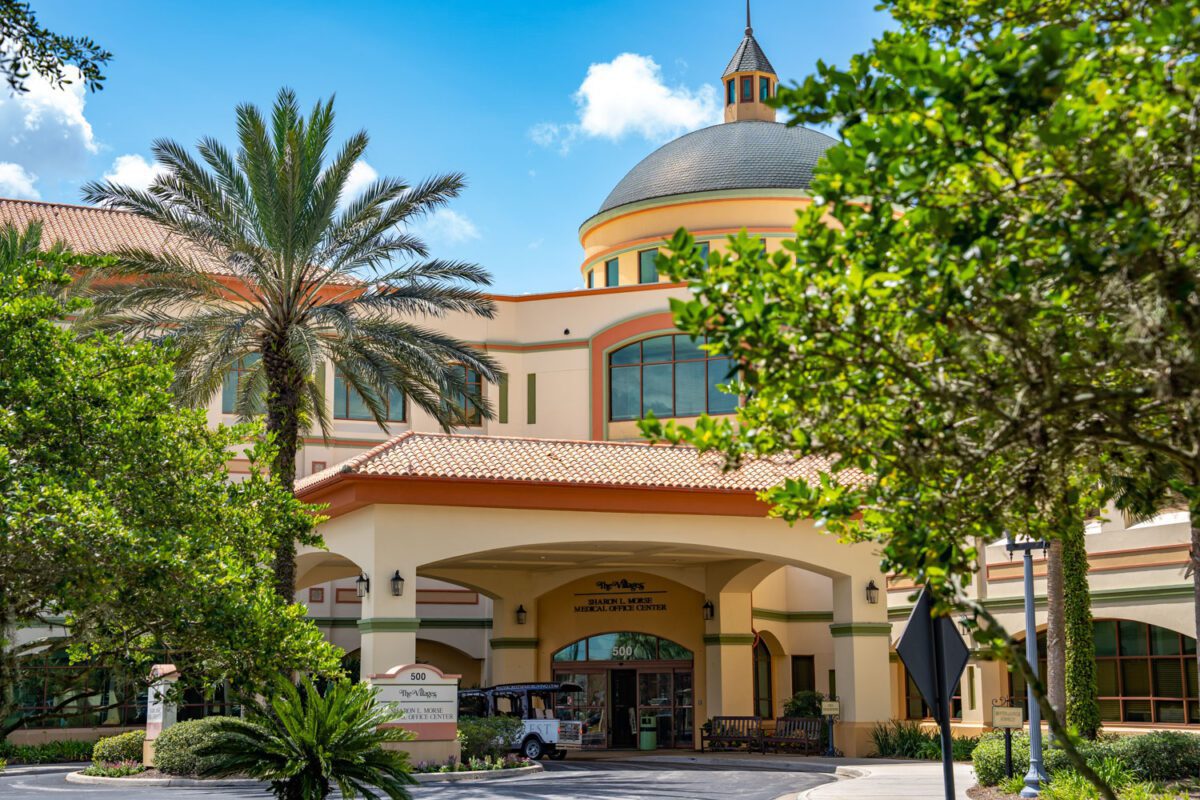
The Villages began as an afterthought in the 1970s, when Morse and Bohl purchased a 1,500-acre orange grove in Sumter County with the intention of developing a modest retirement community. What followed was a slow-burn revolution. By the 1990s, the project had expanded into a master-planned city, complete with its own police force, fire department, and even a private airport. The financial mechanics were simple: sell land, build infrastructure, and create a self-sustaining ecosystem where residents would never need to leave. The result? A model that generated billions in revenue and positioned Morse as a key player in Florida’s real estate renaissance. Today, The Villages is a $30 billion+ enterprise—a figure that includes land values, home sales, and ancillary businesses like golf courses, health clinics, and retail outlets. Morse’s personal stake in this empire is less about direct ownership and more about equity, leadership bonuses, and the residual value of his early investments. Unlike developers who cash out quickly, Morse stayed involved, ensuring The Villages’ growth aligned with his vision of an aging-friendly utopia. His financial success, therefore, isn’t just tied to one project but to a decades-long strategy that turned Florida’s retirement market into a goldmine.Historical Background and Evolution
The Villages’ origins trace back to 1975, when Morse, then a vice president at an insurance company, and Bohl, a developer, pooled resources to buy the grove. Their initial plan was modest: a few hundred homes for retirees who wanted a quieter life. But as the baby boomer generation approached retirement, the pair recognized an opportunity. By the 1980s, they had expanded into active adult communities, a term Morse himself popularized to appeal to a generation that rejected the stereotype of passive aging. The shift was critical—it positioned The Villages not as a nursing home alternative but as a lifestyle destination, complete with social clubs, fitness centers, and even a 24-hour emergency response system. The financial turning point came in the 1990s, when The Villages began offering homeowner associations (HOAs) with mandatory fees that funded shared amenities. This model ensured steady cash flow while creating a sense of community. By 2000, the development had grown to 10,000 residents, and Morse’s influence was undeniable. His ability to anticipate boomer needs—from golf to healthcare—meant The Villages wasn’t just selling property; it was selling security and vitality. The result? A compound annual growth rate that outpaced Florida’s real estate market by nearly threefold in the 2000s.Core Mechanisms: How It Works
The Villages’ financial engine runs on three pillars: land appreciation, recurring revenue, and ecosystem lock-in. First, Morse and his team acquired vast tracts of land at low prices in the 1970s and 1980s, long before Florida’s real estate boom. As The Villages expanded, the value of unsold land appreciated exponentially, creating untapped equity that could be reinvested or monetized. Second, the HOA model ensures a steady stream of income from residents, funding everything from road maintenance to social programs. Third, the community’s self-contained nature—with its own utilities, security, and healthcare—makes leaving economically and socially costly, ensuring long-term occupancy. Morse’s genius lay in recognizing that retirees weren’t just buyers; they were lifetime customers. By offering services like transportation, dining, and even pet care, The Villages eliminated the need for residents to interact with the outside world. This closed-loop economy not only maximized revenue but also reduced churn, making the community’s financial projections more predictable. The result? A business model that could weather recessions—something most real estate ventures couldn’t claim.Key Benefits and Crucial Impact
The Villages’ success didn’t just line pockets; it redefined aging in America. Before Morse’s vision, retirement communities were often seen as sad, institutional spaces. The Villages flipped that narrative by proving that senior living could be dynamic, profitable, and scalable. The financial impact is equally staggering: the community has generated over $10 billion in sales since its inception, with annual revenues now exceeding $1 billion. For Morse, the payoff was twofold—personal wealth and a legacy that influenced how millions of Americans approach their golden years. The model’s influence extends beyond Florida. Competitors like Del Webb’s Sun City and 55+ communities across the U.S. adopted similar strategies, but none achieved the same scale. The Villages’ $30 billion valuation makes it a rare unicorn in the real estate sector—a privately held company with the financial might of a Fortune 500 firm.“Mark Morse didn’t just build a retirement community; he built a movement. The Villages proved that aging could be a business opportunity, not just a demographic challenge.” — Florida Real Estate Review, 2019
Major Advantages
- Land Monopoly: Early acquisition of thousands of acres at low prices created a land bank that appreciated exponentially.
- Recurring Revenue: Mandatory HOA fees ensure consistent cash flow, reducing reliance on new sales.
- Ecosystem Lock-In: Residents’ dependence on community services minimizes turnover, boosting long-term profitability.
- Brand Loyalty: The Villages’ reputation as a lifestyle choice (not just housing) attracts premium buyers.
- Tax Efficiency: Florida’s lack of state income tax and business-friendly laws maximized returns on investments.
- Scalability: The model can be replicated in other states, though none have matched its size or profitability.
Comparative Analysis
| Metric | The Villages (Morse’s Empire) | Competitor (e.g., Del Webb) |
|---|---|---|
| Total Value | $30B+ (land + assets) | $5B–$10B (varies by project) |
| Resident Base | 150,000+ (growing) | 5,000–50,000 per community |
| Revenue Model | HOA fees + land sales + ancillary services | Primarily home sales + limited amenities |
| Land Acquisition Strategy | Long-term holds, controlled expansion | Faster development, higher turnover |
| Market Influence | Redefined senior living; industry benchmark | Follows The Villages’ model but lacks scale |
Future Trends and Innovations
The Villages’ next phase focuses on technology and healthcare integration. Morse’s team is investing in AI-driven resident services, from virtual doctors to smart-home automation, to future-proof the community against rising healthcare costs. Additionally, expansions into Texas and Arizona signal a push beyond Florida, though replicating The Villages’ success will require identical land acquisition strategies—a challenge in pricier markets. Another trend is intergenerational living. As boomers age, The Villages is testing family-friendly zones to attract younger buyers who might one day care for aging parents on-site. This could double the community’s lifespan by appealing to multiple demographics. For Morse, the goal remains the same: extend the financial and social value of his empire well into the 21st century.
Conclusion
Mark Morse’s story is one of patient capitalism—a man who bet on an idea before it was mainstream and built an empire on the back of America’s aging population. His mark morse the villages net worth isn’t just a personal fortune; it’s a testament to how real estate, demographics, and lifestyle marketing can converge into a financial powerhouse. The Villages isn’t just a retirement community; it’s a case study in scalable aging, and Morse’s role in its creation ensures his legacy will outlast the golf courses and town squares he helped design. For investors, the lesson is clear: long-term vision in niche markets can yield outsized returns. For retirees, The Villages proved that aging could be lucrative, vibrant, and—above all—profitable. And for Morse? The real estate mogul who never wanted to be one, the ultimate reward may not be the money, but the thousands of lives he’s allowed to age on their own terms.Comprehensive FAQs
Q: How did Mark Morse accumulate his wealth?
A: Morse’s wealth stems from early land investments, equity stakes in The Villages, and decades of reinvested profits. Unlike traditional developers who flip properties, he focused on long-term appreciation and recurring revenue from HOA fees, ensuring sustained growth.
Q: Is The Villages publicly traded?
A: No. The Villages remains privately held, which means its exact financials—including Morse’s personal net worth—are not disclosed. Industry estimates suggest the company’s total value exceeds $30 billion, but specifics are guarded.
Q: What role does Mark Morse play in The Villages today?
A: Morse stepped back from daily operations in the 2010s but remains a majority stakeholder and strategic advisor. His influence is still felt in expansion plans and business decisions, though day-to-day management is handled by professional executives.
Q: Could The Villages’ model work in other states?
A: The model is replicable but not identical. Florida’s tax advantages, land availability, and boomer migration made it ideal. Expansions in Texas and Arizona are underway, but success depends on finding similar land deals and demographic demand.
Q: How does The Villages’ HOA model ensure profitability?
A: The HOA fees—mandatory for residents—fund shared services (security, transportation, etc.), creating a self-sustaining revenue stream. Unlike traditional HOAs, The Villages’ fees are structured to cover operating costs and generate surplus, ensuring long-term financial health.
Q: Are there any risks to The Villages’ financial model?
A: Yes. Demographic shifts (e.g., fewer boomers) and economic downturns could reduce demand. Additionally, rising construction costs and competition from other 55+ communities pose challenges. However, The Villages’ brand loyalty and ecosystem lock-in mitigate many risks.
