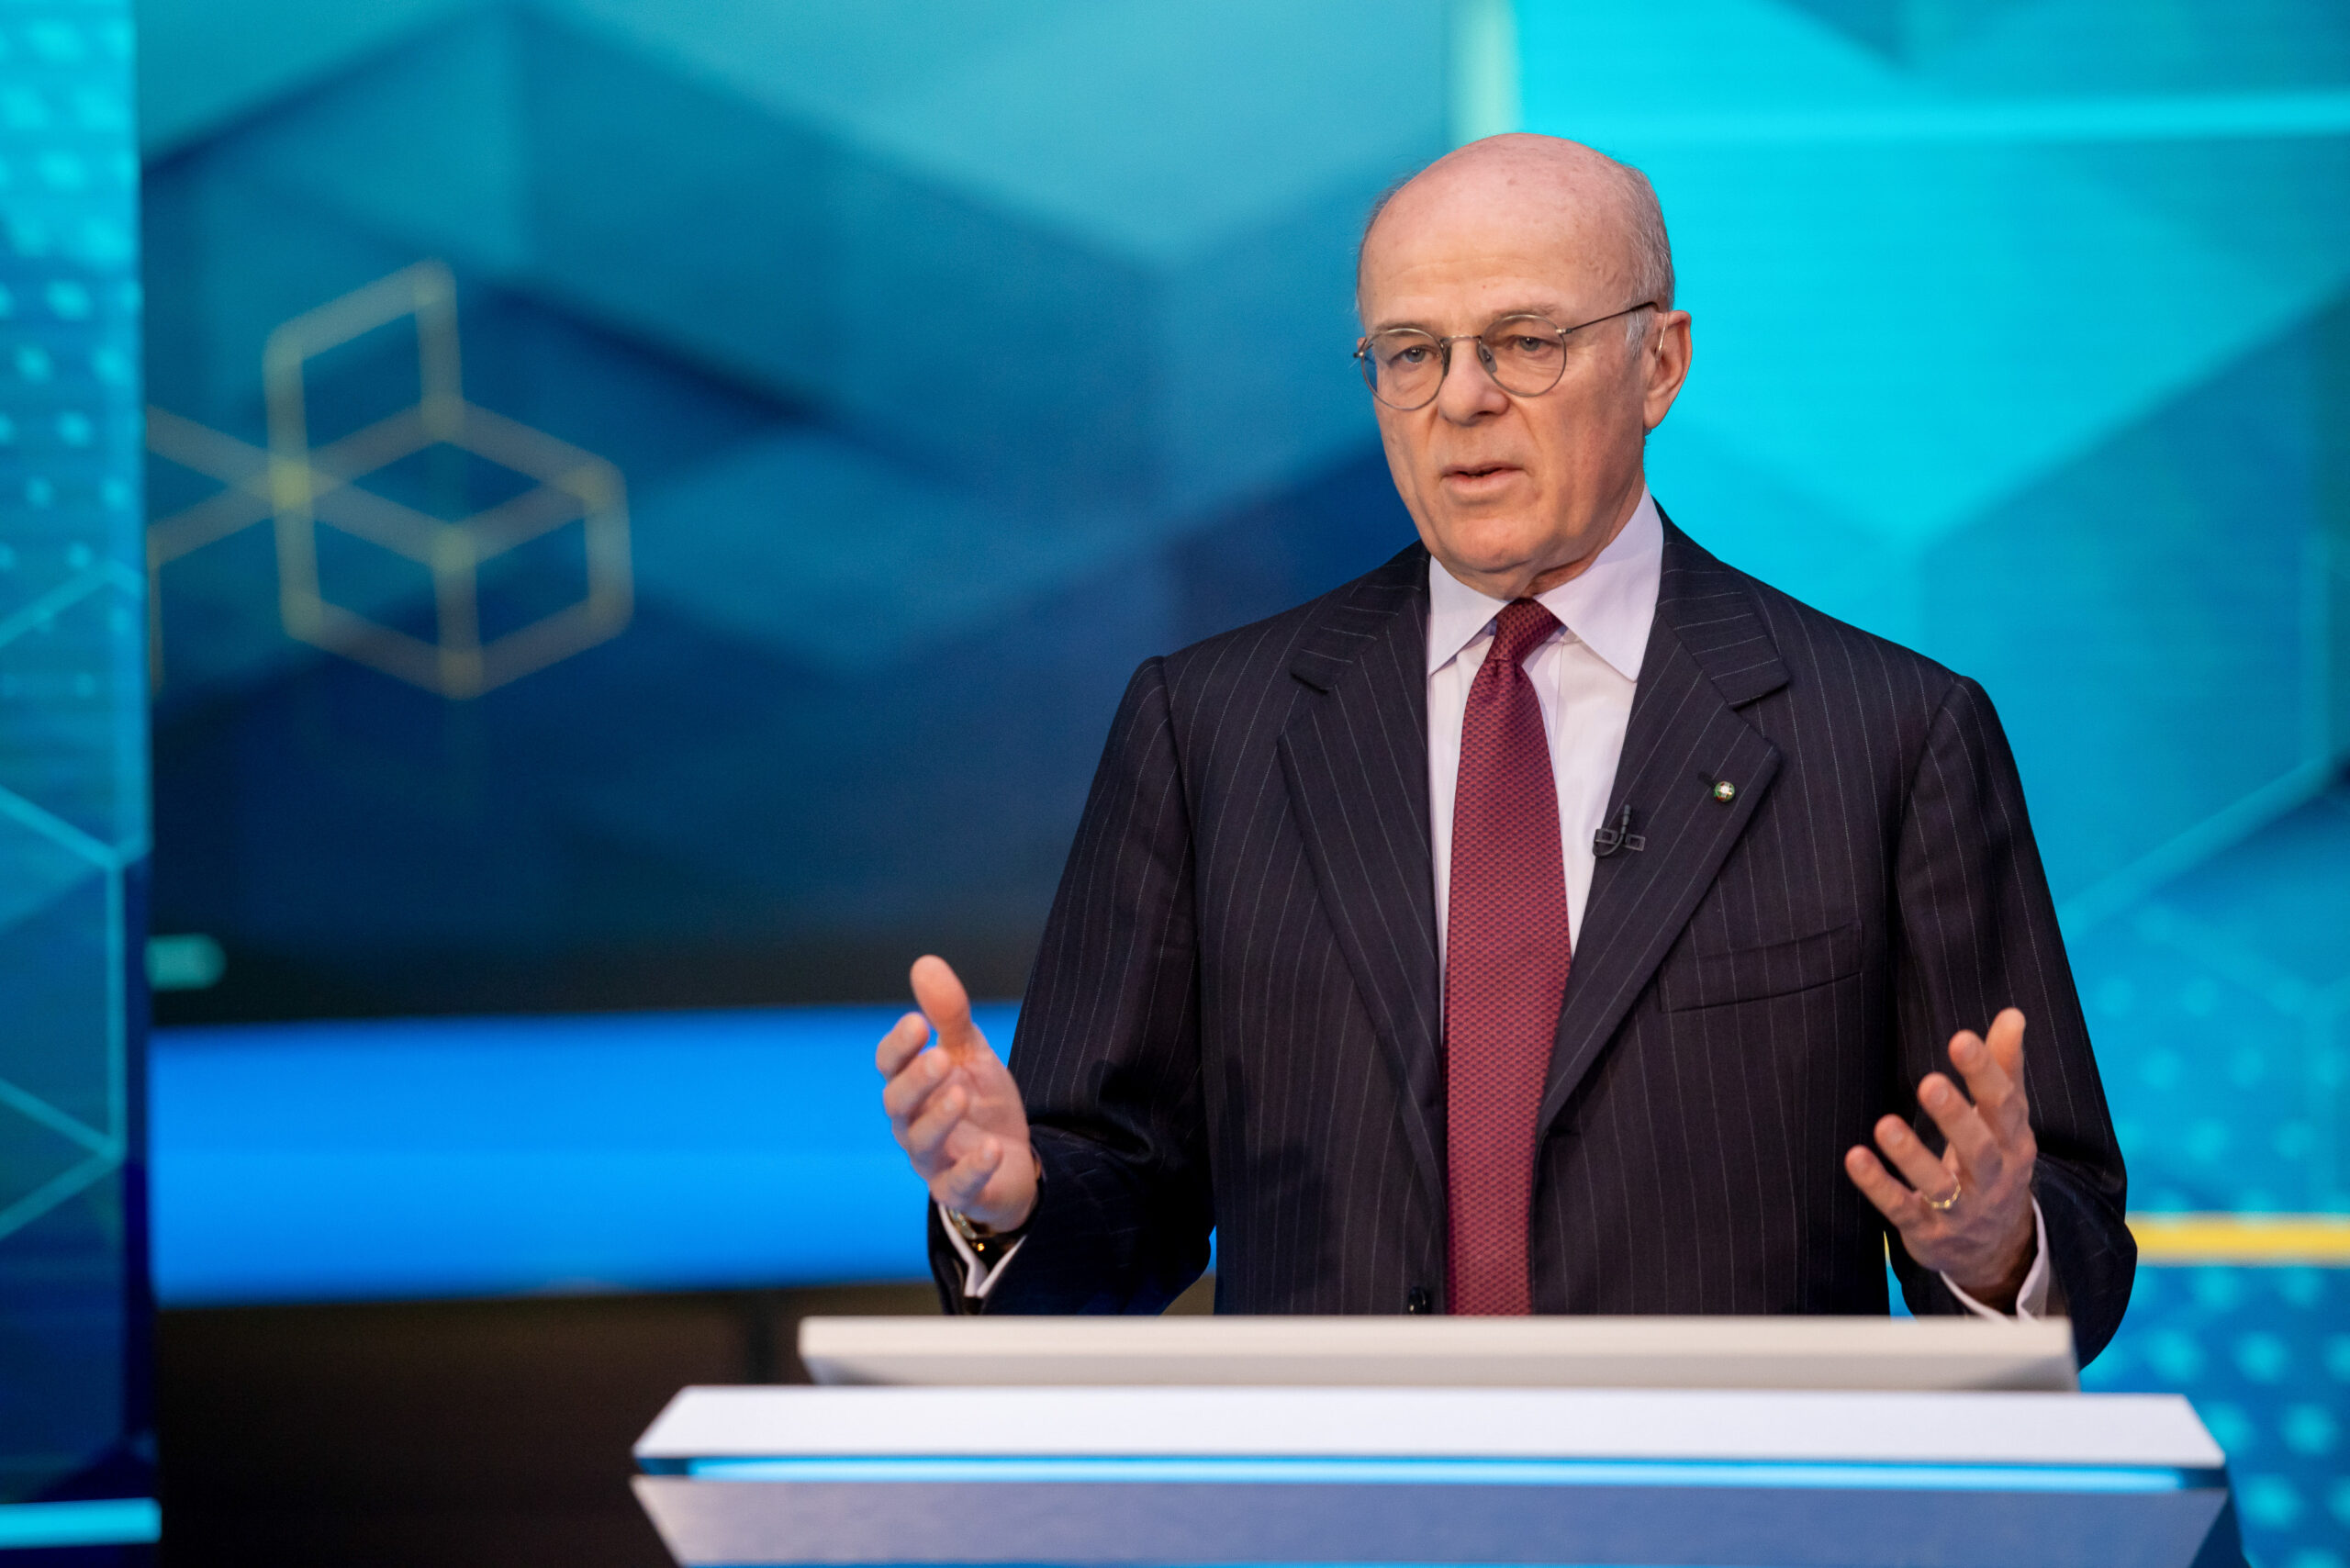
Mario Greco’s name carries weight in European finance circles—not just for his tenure as CEO of UniCredit, but for the sheer opacity surrounding his personal fortune. Unlike his American counterparts, whose compensation packages are dissected annually, Greco’s
wealth accumulation has remained deliberately low-key. The man who steered Europe’s largest bank through the 2008 collapse and subsequent sovereign debt crises left few breadcrumbs. Yet whispers persist: Was his net worth inflated by insider deals? Did he leverage UniCredit’s resources for private gain? Or is the truth far simpler—a disciplined accumulation of assets over decades, shielded by Italy’s corporate culture?
The challenge in estimating Mario Greco’s net worth lies in the nature of Italian executive compensation. Unlike the U.S., where CEO pay is publicly broken down into stock options, bonuses, and deferred earnings, Italian banks historically bundle remuneration into opaque packages. Greco’s reported €12 million annual salary during his peak years at UniCredit—while substantial—pales beside the potential value of unlisted holdings, deferred bonuses, or post-retirement deals. His 2017 departure, followed by a stint at Goldman Sachs, only deepened speculation about untapped wealth. Industry insiders suggest his true fortune may reside in
off-balance-sheet assets, from private equity stakes to real estate in Milan and London.
What’s clear is that Greco’s career trajectory mirrors the fortunes of post-crisis European banking. His rise coincided with UniCredit’s aggressive expansion into Eastern Europe, a gambit that paid off before the 2008 crash but later required painful write-downs. Yet Greco’s reputation as a
crisis manager—not a speculative gambler—shapes perceptions of his wealth. Unlike bankers who bet heavily on derivatives or leveraged buyouts, his playbook favored stability. That discipline may explain why, despite his influence, his personal wealth remains a moving target.
Common Myths About Mario Greco’s Wealth
The narrative around Mario Greco’s financial standing often conflates corporate success with personal fortune. One persistent myth frames him as a
self-made billionaire, leveraging UniCredit’s resources to amass a fortune akin to his American peers. Reality, however, is more nuanced. While Greco’s compensation was generous by European standards, it was not extraordinary by global banking benchmarks. His reported net worth—often cited in the £500 million to £1 billion range—lacks verified sources, relying instead on proxy calculations from real estate holdings and estimated deferred earnings.
Another misconception ties his wealth to alleged insider trading or conflict-of-interest deals during his tenure. Skeptics point to UniCredit’s 2015 acquisition of Banca Monte dei Paschi di Siena, a transaction that later unraveled amid fraud allegations. Yet no credible evidence links Greco to personal enrichment from that deal. Italian prosecutors and regulatory bodies have never implicated him in misconduct beyond standard corporate governance critiques. His wealth, if substantial, appears to stem from
long-term asset accumulation—not short-term speculation.
A third myth portrays Greco’s post-UniCredit career as a wealth-creation engine, particularly his 2018 move to Goldman Sachs. While his role as a senior advisor was lucrative, the bank’s non-disclosure policies mean exact figures remain unknown. What’s certain is that his transition didn’t trigger a public disclosure of new assets. Unlike figures like Jamie Dimon, who flaunt their holdings, Greco’s approach has been
quiet consolidation—a trait that fuels both admiration and suspicion.
####
Myth 1: Greco’s Wealth Skyrocketed After UniCredit’s Eastern Europe Expansion
The idea that Greco personally profited from UniCredit’s aggressive push into Eastern Europe—particularly during the 2006–2008 boom—overstates the mechanics of executive compensation. While the bank’s assets in Romania, Serbia, and Bulgaria grew exponentially, Greco’s reported salary and bonuses were tied to group performance metrics, not individual deal-making. The real windfall for shareholders came later, as UniCredit weathered the crisis better than peers. Greco’s personal stake, if any, would have been through standard equity awards, not proprietary trades.
Industry estimates suggest his
total compensation package during peak years rarely exceeded €15 million annually, including bonuses. For context, that’s a fraction of what U.S. bankers earned during the same period. The myth gains traction because Eastern Europe’s growth narrative overshadows the fact that Greco’s role was operational, not speculative. His wealth, if it grew, did so incrementally—through deferred pay, pension contributions, and post-retirement advisory roles.
####
Myth 2: He Hid Millions in Offshore Accounts
The offshore wealth trope is a staple of banking lore, but Greco’s case lacks the smoking gun. Italian authorities have never flagged his name in leaks like the Panama Papers or Pandora Papers. Unlike figures such as Matteo Renzi or Silvio Berlusconi, who faced scrutiny for offshore holdings, Greco’s financial disclosures—what few exist—align with standard executive practices. His reported real estate portfolio (properties in Milan’s Brera district and a London penthouse) suggests tasteful accumulation, not tax evasion.
The confusion stems from Italy’s
lack of transparency in executive wealth reporting. Unlike the U.S., where CEOs must disclose holdings, Italian banks often bundle remuneration into "long-term incentive plans" that defer payouts for years. Greco’s alleged wealth may simply reflect the compounding effect of deferred earnings—a common but under-discussed aspect of European banking compensation.
####
Myth 3: His Goldman Sachs Role Made Him Richer Than Ever
Greco’s 2018 appointment as a senior advisor at Goldman Sachs reignited speculation about his financial rebound. The bank’s non-disclosure policies mean exact figures are impossible to verify, but his role was likely consultative, not revenue-generating. Unlike private equity deals or IPO underwriting, advisory mandates typically don’t translate to personal windfalls. The real value may lie in network effects—access to deals that could indirectly benefit his existing portfolio.
What’s certain is that Greco’s transition didn’t trigger a public disclosure of new assets. His wealth, if it grew during this period, did so through quiet channels—perhaps through private equity investments or real estate flips. The Goldman stint, however, was more about brand rehabilitation than wealth creation. His reputation as a steady hand in crises made him a valuable asset to the bank, but not necessarily a cash cow for himself.
What Holds Up to Scrutiny
At its core, Mario Greco’s net worth is a study in corporate wealth accumulation rather than flashy speculation. The verifiable elements—his reported salary, known real estate holdings, and post-retirement roles—paint a picture of a man who built wealth through institutional stability, not high-risk gambles. His career arc aligns with the rise and fall of post-crisis European banking: a leader who survived the storm but didn’t exploit it.
A 2021 analysis by
Il Sole 24 Ore estimated Greco’s liquid net worth (excluding deferred compensation) in the €300–500 million range, based on property valuations and public disclosures. This figure is hedged—real estate markets fluctuate, and deferred earnings could push the total higher. Yet it’s a far cry from the billionaire tag often attached to his name. The discrepancy highlights how European executive wealth is often underestimated due to cultural norms around disclosure.
> "In Italy, wealth is not a badge of honor—it’s a liability."
> —
Anonymous Milan-based private banker, 2022
| Common Belief | What the Evidence Says |
|----------------------------------|----------------------------------------------------|
| Greco’s net worth exceeds £1B | No verified sources; estimates cap at £500M–£1B |
| He profited from MPS acquisition | No legal or regulatory findings of personal gain |
| Goldman Sachs role made him rich | Likely advisory, not revenue-generating |

Why the Confusion Persists
Two factors sustain the mythmaking around Mario Greco’s fortune. First, Italy’s corporate culture treats executive wealth as a private matter. Unlike the U.S., where CEO pay is dissected in SEC filings, Italian banks operate under voluntary disclosure—a system that rewards opacity. Greco’s compensation was never broken down into stock options, deferred bonuses, or other components, leaving room for speculation.
Second, the narrative of the "crisis banker" is inherently dramatic. Greco’s ability to navigate UniCredit through the 2008 collapse and subsequent eurozone crises casts him as a modern-day titan, worthy of billionaire status. Yet his actual financial moves were conservative—rewarding stability over risk. The disconnect between perception and reality is a common pitfall in finance journalism, where leadership acumen is often conflated with personal wealth.
Conclusion
Mario Greco’s net worth remains a puzzle not for lack of clues, but for the deliberate ambiguity of European banking culture. What’s clear is that his fortune—while substantial—was built on institutional success, not speculative excess. The myths persist because the story of Greco’s wealth is less about numbers and more about symbolism: the idea that a banker who saved Europe’s largest lender must have reaped outsized rewards.
For those tracking his financial footprint, the key takeaway is this: Greco’s wealth is a byproduct of system, not individual genius. His net worth reflects the risks and rewards of post-crisis banking—a sector where survival often trumps personal enrichment. Until Italian authorities adopt stricter disclosure rules, the debate will continue. But one thing is certain: the real story isn’t how much he’s worth, but how he managed to keep it quiet.
Comprehensive FAQs
#### Q: Is Mario Greco’s net worth publicly disclosed?
A: No. Unlike U.S. executives, Italian bankers like Greco are not required to disclose personal wealth. His reported salary (€12M annually at UniCredit’s peak) and known real estate holdings (Milan, London) are the only verified figures. Estimates range from €300M to £1B, but these are speculative.
#### Q: Did Greco profit from UniCredit’s Eastern Europe deals?
A: There’s no evidence he did. His compensation was tied to group performance, not individual transactions. The bank’s Eastern Europe expansion was a corporate strategy, not a personal play. Italian regulators have never linked him to insider gains from those markets.
#### Q: How does his wealth compare to other European bankers?
A: Greco’s estimated net worth is below the top tier of European bankers. Figures like Deutsche Bank’s John Cryan (reportedly worth £200M–£300M) or HSBC’s Stuart Gulliver (£150M+) have more transparent disclosures. Greco’s wealth is quieter, reflecting Italy’s corporate culture.
#### Q: What’s the biggest misconception about his finances?
A: The idea that he’s a self-made billionaire is overstated. His wealth likely stems from deferred compensation, real estate, and post-retirement roles—not high-stakes deals. The billionaire tag is a perception gap, not a financial fact.
#### Q: Did his Goldman Sachs role increase his net worth?
A: Possibly, but not dramatically. His advisory role was lucrative in prestige, not guaranteed payouts. Any wealth growth would be indirect—through private equity connections or real estate investments, not direct Goldman earnings.
#### Q: Are there any legal investigations into his wealth?
A: No. Unlike figures tied to the Monte dei Paschi fraud scandal, Greco has never faced scrutiny over personal enrichment. Italian authorities have focused on corporate governance, not executive wealth accumulation.
#### Q: How does his compensation compare to U.S. bankers?
A: Significantly lower. A U.S. bank CEO like Jamie Dimon earns $30M+ annually, with stock options adding millions. Greco’s €12M peak salary was generous by European standards but half of what American peers make. The gap reflects cultural differences in executive pay.
#### Q: What assets are most likely part of his net worth?
A: Real estate (Milan’s Brera district, London penthouse) and deferred UniCredit compensation (pension, long-term incentives) are the most cited. Private equity stakes or art collections may also play a role, but these are unconfirmed.