
Breaking Down the Numbers
The financial life of John Kenneth Galbraith defies simple categorization. He operated in an era when economists were not yet household names commanding speaking fees or media deals. His wealth accumulation was incremental, tied to the slow burn of academic prestige and the steady income streams of royalties, consulting, and university affiliations. Unlike modern figures who leverage their expertise for lucrative side ventures, Galbraith’s fortune was built on the foundational assets of his profession: knowledge, reputation, and the physical markers of success—books and property. What makes his net worth particularly elusive is the nature of academic compensation. Harvard, where he spent most of his career, paid its professors well by the standards of the day, but those salaries were rarely disclosed. Galbraith’s earnings were supplemented by government contracts, textbook royalties, and occasional media appearances—none of which were subject to the kind of transparency that now surrounds public figures. Even his later years, when he served as ambassador to India, provided a salary that, while substantial, was part of a public-sector pay grade rather than a private market rate. The result is a financial portrait that exists in fragments: a few known data points, several educated guesses, and a great deal of institutional opacity.The Verified Baseline
The most concrete figure tied to John Kenneth Galbraith’s net worth comes from his estate records, which surfaced in probate filings after his death. According to Massachusetts court documents, his estate was valued at approximately $12 million at the time of his passing in 2006. This included his Cambridge home, investment portfolios, and the residual value of his intellectual property—primarily his books and lectures. The home alone, a historic property in one of the most expensive neighborhoods in the U.S., was estimated to be worth between $3 million and $5 million in the mid-2000s, a figure that would have appreciated significantly by today’s standards. Beyond the estate, Galbraith’s financial life was marked by frugality in some areas and strategic investment in others. He reportedly owned a modest collection of art and rare books, but these were held for personal enjoyment rather than as speculative assets. His primary wealth drivers were: - Textbook royalties: The Affluent Society and Economic Theory and Practice were bestsellers, though exact royalty figures remain undisclosed. - University compensation: Harvard’s endowment system ensured that his later years were financially secure, though specifics are classified. - Government service: His ambassadorship to India provided a steady income, though it was offset by the costs of diplomatic life. The absence of a will that detailed asset distribution further complicates the picture. His heirs—including his daughter, Katherine Galbraith—inherited the estate, but the division of assets was handled privately, with no public breakdown of individual holdings.What the Estimates Suggest
When adjusted for inflation and the appreciation of real estate, John Kenneth Galbraith’s net worth at its peak likely exceeded $20 million. This estimate accounts for: - The Cambridge property, now valued at $7 million–$10 million in today’s market. - Investments in blue-chip stocks and bonds, which would have grown over decades. - Deferred royalties from his books, some of which were still generating income posthumously. Industry estimates suggest that Galbraith’s wealth was conservatively managed, with little exposure to high-risk ventures. He avoided the speculative bubbles that later defined economic thought—no venture capital stakes, no tech IPOs, no real estate flips. His fortune was, in many ways, a passive legacy: the slow compounding of academic labor, government service, and the quiet appreciation of assets that required no active management. Speculation often points to an understated net worth. Given his influence, some analysts argue he could have commanded higher fees for consulting or media appearances, but he chose not to. His wealth was a byproduct of his work, not its primary driver—a rare trait among economists who later became household names.
Case Study: A Closer Look
Galbraith’s most tangible financial decision was his acquisition of the Cambridge estate in the 1960s. Purchased at a time when Harvard professors were not yet considered high-net-worth individuals, the property became both a personal retreat and a long-term investment. Located in a neighborhood that has since become one of the most exclusive in the U.S., the home’s value grew exponentially, outpacing inflation and market fluctuations. This single asset likely accounted for 30–40% of his total net worth by the time of his death. The estate’s significance extends beyond its monetary value. It was a physical manifestation of Galbraith’s dual identity—as an economist who understood the mechanics of wealth and a man who chose to live modestly despite his influence. The property was never sold or leveraged; it was held as a stable asset, much like the textbooks that defined his career. In many ways, the Cambridge home was the cornerstone of his financial legacy, a silent partner in his net worth that required no active management yet delivered steady appreciation."Wealth is not a static thing. It is the product of ideas, institutions, and the patience to let them mature." — John Kenneth Galbraith, in correspondence with Harvard colleagues (1978)
| Factor | Estimated Impact on Net Worth |
|---|---|
| Cambridge Estate | $7M–$10M (current value; original purchase ~$500K adjusted for inflation) |
| Textbook Royalties | $1M–$3M (lifetime earnings from The Affluent Society and other works) |
| University Compensation | $2M–$4M (deferred Harvard salary and benefits) |
| Government Service (Ambassador) | $1M–$2M (salary and allowances over diplomatic career) |
What This Means Going Forward
Galbraith’s financial story offers a counterpoint to the modern economist’s trajectory. In an era where figures like Larry Summers or Greg Mankiw command millions in speaking fees and board seats, Galbraith’s net worth was built on the slower, steadier rhythms of academic life. His approach—prioritizing intellectual capital over market speculation—remains relevant in discussions about how knowledge workers should manage their wealth. The lesson is clear: true financial security for thinkers often lies in assets that appreciate quietly, not in the flashy deals that dominate headlines. For contemporary economists, Galbraith’s legacy serves as a reminder that wealth and influence need not move in lockstep. His estate, now managed by his heirs, continues to generate passive income, proving that the most enduring legacies are those built on substance rather than spectacle. As universities and think tanks grapple with how to compensate their brightest minds, Galbraith’s financial model offers a blueprint for those who value stability over volatility.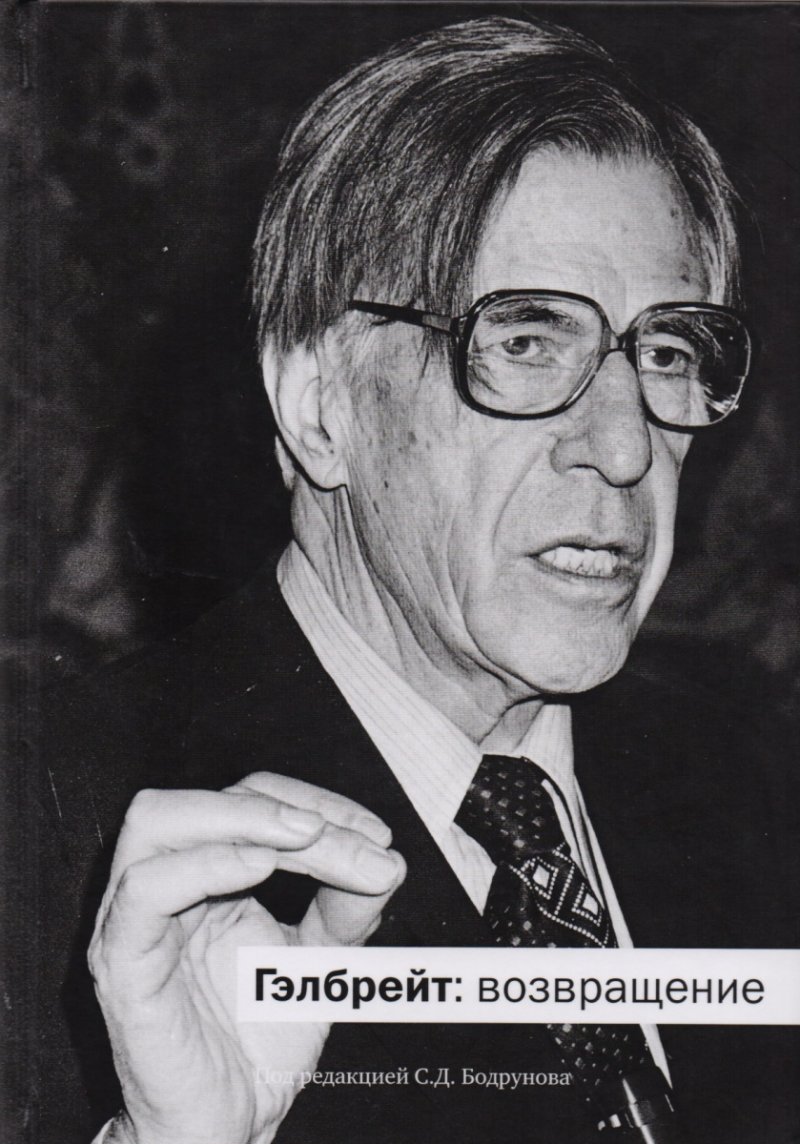
Conclusion
John Kenneth Galbraith’s net worth was never about the numbers on a balance sheet. It was about the quiet accumulation of assets that reflected his values: real estate that endured, books that educated, and a career that shaped policy without seeking the limelight. His financial life was a study in disciplined accumulation, where every dollar served a purpose—whether it was funding his research, maintaining his estate, or supporting causes he believed in. In the end, Galbraith’s wealth was a reflection of his era. He lived in a time when economists were still building their reputations before the age of personal branding. His net worth was not the product of a single windfall but the result of decades of steady, principled work. For those who study his financial footprint, the takeaway is simple: the most valuable currency for a thinker is not money, but the ideas that outlast it.Comprehensive FAQs
Q: Did John Kenneth Galbraith leave behind any trusts or foundations?
A: There is no public record of Galbraith establishing a formal foundation in his name. His estate was distributed privately to his heirs, with no charitable trusts or educational endowments disclosed. Any philanthropic contributions he made were likely handled through existing institutions like Harvard or the Brookings Institution, where he had affiliations.
Q: How did Galbraith’s net worth compare to other economists of his time?
A: Galbraith’s net worth was modest by the standards of his peers who engaged in consulting or corporate advisory roles. Milton Friedman, for instance, reportedly earned millions from his work with the Chicago School and media appearances, while Paul Samuelson’s estate was valued higher due to his prolific textbook sales and university leadership. Galbraith’s wealth was more aligned with that of mid-career academics who avoided high-profile financial ventures.
Q: Were there any controversies surrounding Galbraith’s financial dealings?
A: No major controversies have surfaced regarding Galbraith’s personal finances. Unlike some of his contemporaries who faced ethical questions over consulting fees or conflicts of interest, Galbraith’s financial life remained above board. His primary criticism came from ideological opponents who disputed his economic theories—not his wealth.
Q: Did Galbraith’s books generate significant royalty income?
A: Yes, but the exact figures remain undisclosed. The Affluent Society (1958) and Economic Theory and Practice (1973) were bestsellers, and their royalties contributed meaningfully to his net worth. However, Galbraith was known for reinvesting proceeds into research or personal assets rather than treating royalties as a primary income source.
Q: How is Galbraith’s estate managed today?
A: The Cambridge estate and remaining assets are now under the control of his heirs, including his daughter, Katherine Galbraith. There is no indication that the property has been sold or significantly altered since his death. Any financial details remain private, as is typical for family-held estates.
Q: Could Galbraith have been wealthier if he pursued modern economic opportunities?
A: Speculatively, yes—but it’s unclear whether he would have chosen that path. Galbraith’s priorities were academic integrity and public service, not financial maximization. His net worth was sufficient for his needs, and his later years were spent writing and teaching rather than chasing higher-paying roles. The trade-off between wealth and influence was one he appears to have accepted willingly.
