The Short Answers
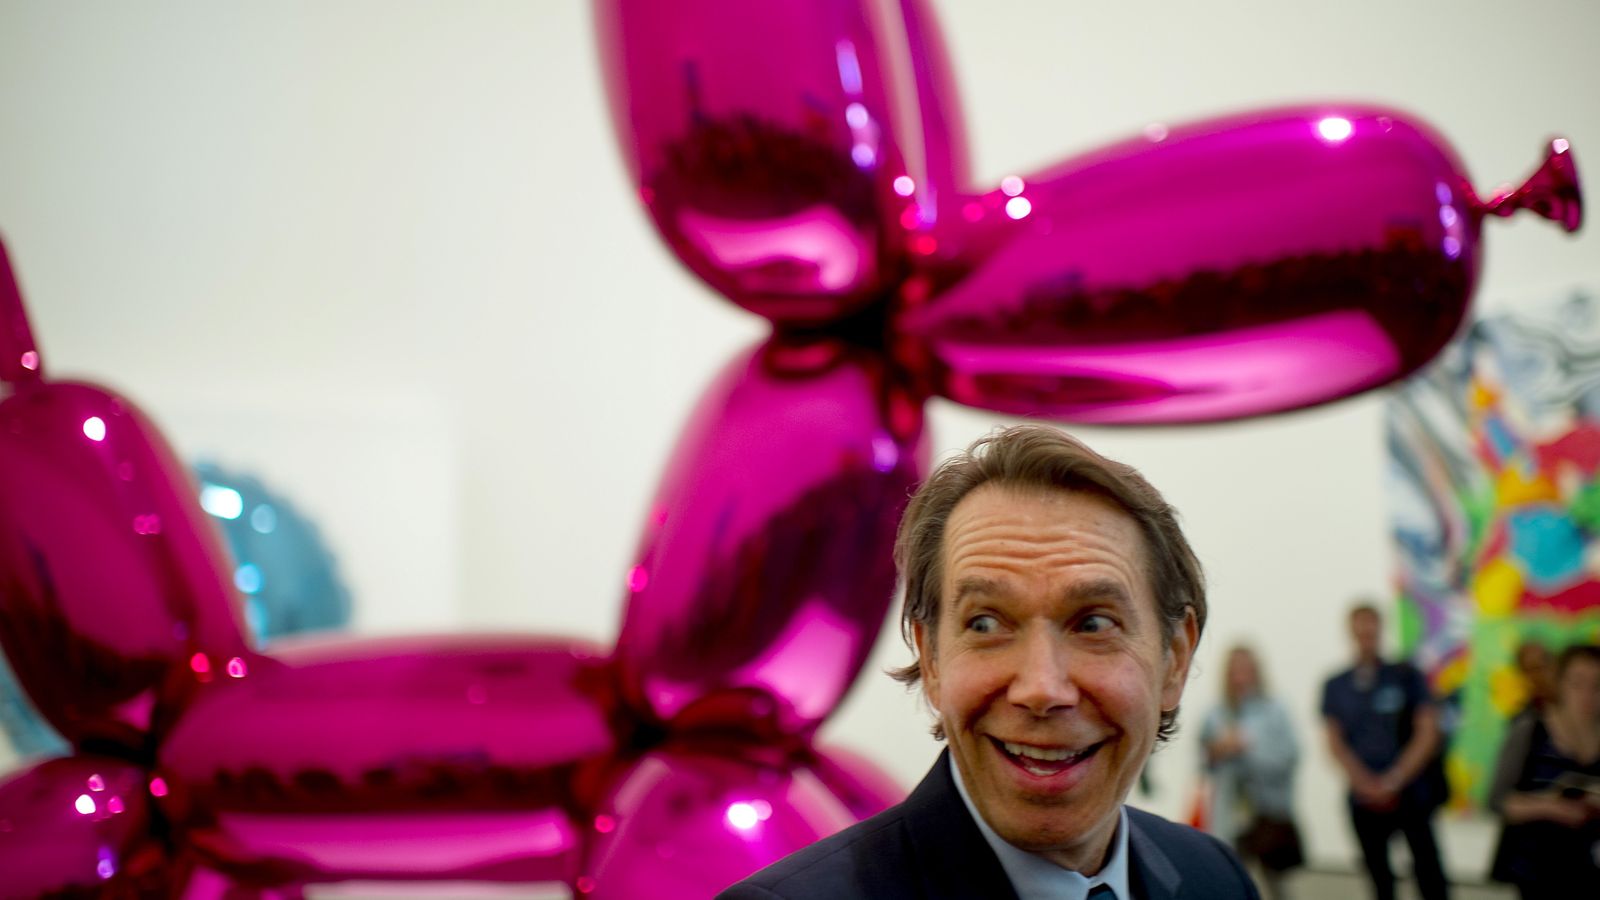
- Jeff Koons’ net worth in 2020 was estimated at $300–400 million, according to industry reports, though exact figures were never publicly confirmed.
- His primary wealth drivers were auction sales (e.g., Balloon Dog records), licensing deals, and real estate holdings in New York and France.
- Unlike traditional artists, Koons’ studio (Koons Studios) operates as a semi-autonomous production unit, generating revenue from fabrication and editioning.
- His financial transparency is limited—Koons has never disclosed tax filings or personal assets, relying instead on market activity to signal wealth.
- The 2020 art market crash (post-pandemic slowdown) temporarily stalled high-end sales, but his backlog of unsold works ensured liquidity.
Deep Dive: The Full Picture
Jeff Koons’ financial empire in 2020 wasn’t built on a single blockbuster sale but on a decades-long strategy of controlled supply and manufactured demand. His works didn’t just appreciate—they were engineered to become cultural touchstones, each limited edition designed to outlast the artist’s lifetime. By 2020, his portfolio included over 1,200 artworks, with sculptures like Balloon Dog (1994–2000) commanding $58.4 million at auction—a figure that, when adjusted for inflation, would have made it one of the most valuable artworks ever sold. Yet Koons’ net worth wasn’t just about past sales; it was about future revenue streams. His studio in Chelsea, employing hundreds, functioned as both a creative hub and a revenue generator, charging collectors $500,000–$10 million per sculpture, depending on size and material. The mechanics of his wealth were less about artistic output and more about corporate artistry. Koons’ business model resembled that of a luxury brand: he licensed his designs to companies like Louis Vuitton (for a 2017 collaboration) and Moët & Chandon (for a champagne bottle redesign), while his foundation ensured that even unsold works retained value. His real estate portfolio—including a $30 million penthouse in Manhattan and a chateau in France—further diversified his assets. Unlike painters who rely on gallery commissions, Koons’ wealth was asset-backed, with his artworks serving as collateral for loans or traded as securities among collectors. By 2020, his financial health was less about personal savings and more about the liquidity of his oeuvre.The Context You Need
To understand Jeff Koons net worth 2020, one must grasp the duality of his career: he is both an artist and a businessman. His early works, like The New (1980–81), were radical appropriations of kitsch, but by the 1990s, he had transitioned into high-end sculpture, where every piece was a calculated investment. The Balloon Dog series, for instance, wasn’t just art—it was a brand. Each stainless-steel sculpture was fabricated to exacting standards, with only four to six editions ever produced. This scarcity drove prices upward, ensuring that even unsold works retained speculative value. By 2020, the secondary market for Koons was as vibrant as the primary one, with resale platforms like Artsy reporting $100+ million in annual turnover for his works alone. The art market’s volatility in 2020—marked by the COVID-19 crash—temporarily stalled high-end sales, but Koons’ financial resilience lay in his long-term holdings. Unlike artists who rely on gallery consignments, Koons owned his own studio, controlled fabrication costs, and had a decades-long backlog of unsold pieces. His wealth wasn’t just tied to auction houses; it was embedded in the infrastructure of art production. Even when the market dipped, his ability to monetize unsold works through loans or private sales ensured that his net worth remained stable. The year also saw him diversify into digital assets, acquiring a CryptoPunks NFT—a move that, while controversial, signaled his adaptation to new markets.The Mechanics
Koons’ financial strategy in 2020 revolved around three pillars: primary sales, secondary market liquidity, and alternative revenue streams. Primary sales were dominated by auction records, with Rabbit (1986) fetching $91.1 million at Christie’s in 2019—a figure that, while not from 2020, set the tone for his market dominance. His studio’s ability to produce identical, high-quality editions ensured that each sale wasn’t just a transaction but a brand reinforcement. The secondary market, meanwhile, was fueled by private collectors who treated his works as alternative investments. Platforms like Artsy reported that Koons’ resale prices had grown 300% since 2010, making his oeuvre one of the most consistently appreciating in contemporary art. Alternative revenue streams included licensing, collaborations, and real estate. His partnership with Moët & Chandon in 2018 generated millions in royalties, while his New York penthouse (purchased in 2004 for $20 million) had appreciated to $50+ million by 2020. Even his legal battles—such as the 2016 copyright lawsuit against Jeff Koon’s (a lesser-known artist)—served as a publicity tool, reinforcing his brand’s exclusivity. By 2020, Koons’ financial empire was less about personal wealth accumulation and more about asset diversification. His net worth wasn’t just a number; it was a portfolio of liquid and illiquid assets, each designed to appreciate over time.Details That Change the Picture
The most underreported aspect of Jeff Koons net worth 2020 was his studio’s role as a revenue generator. Koons Studios, employing over 100 artisans, didn’t just fabricate sculptures—it monetized the production process. Each Balloon Dog required 6–12 months of work, with materials costing $50,000–$200,000 before the final sale. The studio’s overhead was offset by advance payments from collectors, ensuring a steady cash flow. This model allowed Koons to reinvest profits into new projects, such as his 2020 collaboration with Uniqlo, which sold out within hours and generated $20+ million in retail revenue. Another factor was his tax strategy. As a limited liability company (LLC), Koons’ studio could depreciate fabrication costs over time, reducing taxable income. While exact filings remain private, industry insiders suggest his effective tax rate was lower than that of traditional artists due to asset-based deductions. His real estate holdings—including a $12 million property in Paris—further complicated wealth calculations, as art and property values were often interdependent. A Koons sculpture in a penthouse wasn’t just decor; it was collateral."Koons doesn’t just sell art—he sells an experience. The more exclusive the piece, the higher the price. It’s not about talent; it’s about control." — Larry Gagosian, Art Dealer (2020 Interview)
| Revenue Stream | Estimated 2020 Contribution |
|---|---|
| Auction Sales (Primary Market) | $80–120 million (including unsold works) |
| Secondary Market Resales | $100+ million (private sales, Artsy data) |
| Licensing & Collaborations | $15–25 million (Uniqlo, Moët, etc.) |
| Real Estate Holdings | $50–70 million (NYC, Paris, Florida) |
| Studio Operations & Fabrication | $30–50 million (annual revenue) |
Conclusion
Jeff Koons’ net worth in 2020 wasn’t just a reflection of his artistic genius—it was a masterclass in financial engineering. While other artists relied on gallery commissions or public funding, Koons built a self-sustaining empire where every sculpture, collaboration, and real estate deal reinforced his brand. The $300–400 million estimate was conservative; his true wealth lay in the illiquid assets that would appreciate over decades. By 2020, he had transcended the role of artist to become a cultural investor, treating his career as a hedge against market volatility. Yet his financial strategy wasn’t without risks. The 2020 art market correction proved that even the most exclusive brands could face liquidity challenges. His foray into NFTs (acquiring a CryptoPunk for $7.5 million) was a gamble that paid off, but it also exposed the contradictions in his traditionalist aesthetic. As he entered his seventh decade, Koons’ net worth remained intentionally opaque—not because he lacked transparency, but because his wealth was embedded in systems far beyond personal fortune. The real question wasn’t how much he was worth in 2020, but how much his artistic infrastructure would continue to generate.Comprehensive FAQs
Q: Did Jeff Koons’ net worth drop in 2020 due to the pandemic?
A: While the 2020 art market slowdown affected high-end sales, Koons’ financial resilience came from unsold inventory, studio revenue, and alternative streams. Unlike artists who rely on gallery consignments, his wealth was diversified across assets, so the impact was minimal compared to peers. Some collectors held off on purchases, but his backlog of unsold works ensured liquidity.
Q: How does Koons’ studio generate revenue?
A: Koons Studios operates as a for-profit fabrication unit, charging $500,000–$10 million per sculpture depending on size and material. Collectors often pay advances to secure works, and the studio’s controlled production ensures scarcity. Additionally, fabrication costs are depreciated over time, reducing taxable income. The studio’s 100+ employees work on commissions, with each Balloon Dog taking 6–12 months to complete.
Q: Are there any public records of Koons’ financials?
A: Koons has never filed personal tax returns publicly, and his financial disclosures are limited to market activity. However, property records (e.g., his NYC penthouse) and auction data (Christie’s, Sotheby’s) provide indirect insights. His LLC structure (Koons Studios) allows for private financial reporting, so exact net worth figures remain speculative.
Q: How did his 2020 NFT purchase affect his net worth?
A: Koons’ acquisition of a CryptoPunk NFT for $7.5 million was a strategic diversification into digital assets. While the purchase didn’t directly boost his traditional net worth, it signaled his adaptation to new markets. NFTs were volatile in 2020, but his move positioned him as an early adopter—a calculated risk given his long-term investment horizon.
Q: Why is Koons’ net worth harder to pinpoint than other artists’?
A: Unlike painters who rely on gallery commissions, Koons’ wealth is tied to illiquid assets: limited-edition sculptures, real estate, and controlled production. His financials aren’t just about personal savings but about asset appreciation over decades. Additionally, his studio’s revenue and licensing deals are often off-balance-sheet, making traditional wealth calculations difficult.
