
Breaking Down the Numbers
Japan’s net worth and debts of Japan are often framed as a warning, but the narrative oversimplifies a complex interplay of public and private finance. The country’s gross public debt—reportedly exceeding $12 trillion as of recent fiscal years—is a figure that dominates headlines. Yet this debt is not held solely by foreign creditors; roughly 70% is domestically owned, primarily by Japanese banks, insurance companies, and households. This domestic circulation creates a feedback loop where debt service costs are internalized, reducing the risk of sudden default. Meanwhile, Japan’s household net worth—estimated at over $30 trillion—dwarfs its public liabilities, a reflection of decades of disciplined savings, real estate holdings, and pension funds. The challenge, then, is not insolvency but structural efficiency: ensuring that private wealth continues to absorb public debt without stifling growth. The tension between Japan’s net worth and debts of Japan becomes clearer when examining corporate balance sheets. Japanese firms hold trillions in cash reserves—a legacy of keiretsu-era capital accumulation and conservative lending practices. While this hoarding has drawn criticism for stifling investment, it also serves as a buffer against economic shocks. The Bank of Japan’s yield curve control policy further stabilizes the system by capping borrowing costs, allowing the government to roll over debt with minimal strain. Yet this stability is not without trade-offs. The same policies that sustain Japan’s net worth and debts of Japan also suppress wage growth, limit consumer spending, and create a demographic time bomb as an aging population retires with fewer workers to support them.The Verified Baseline
Publicly available data confirms that Japan’s net worth and debts of Japan are defined by three immutable pillars: 1. Gross Government Debt: As of the latest Ministry of Finance reports, Japan’s gross debt stands at around 260% of GDP, a figure that has remained relatively stable for over a decade. This stability is partly due to nominal GDP growth, which outpaces debt accumulation in most years. 2. Primary Budget Balance: Japan has run primary surpluses (revenue minus non-interest expenditures) for nearly two decades, meaning it generates enough tax revenue to cover day-to-day spending—interest payments are the sole driver of deficits. 3. Domestic Debt Ownership: The Debt Management and Investment Center (DMIC) reports that over 90% of government bonds (JGBs) are held by Japanese entities, including the Bank of Japan itself, which has become the largest single holder through quantitative easing programs. These figures are not speculative; they are audited and published annually. The key takeaway is that Japan’s net worth and debts of Japan operate within a closed-loop system, where creditors and debtors are largely the same economic actors. This reduces the risk of external shocks, but it also means the system is vulnerable to domestic disruptions, such as a sudden shift in savings behavior or a collapse in asset prices.What the Estimates Suggest
Beyond the verified numbers, industry estimates paint a picture of hidden vulnerabilities in Japan’s net worth and debts of Japan. Economists suggest that household debt, while lower than in the U.S. or Europe, is concentrated among older cohorts who rely on real estate equity to fund retirement. If property values decline—even modestly—this could trigger a wealth effect crisis, forcing retirees to liquidate assets at fire-sale prices. Separately, corporate zombie firms—companies kept alive by low interest rates but with no path to profitability—are estimated to hold over $1 trillion in excess cash, which could be deployed more productively if market conditions normalized. Another layer of uncertainty surrounds the Bank of Japan’s exit strategy. While the central bank has signaled plans to tighten monetary policy, the process is expected to be gradual and data-dependent. Sudden moves could send JGB yields spiking, increasing debt service costs and potentially forcing a reassessment of Japan’s net worth and debts of Japan. Some analysts argue that the true risk lies not in default but in inflation eroding the real value of savings, which could undermine the private wealth that currently offsets public liabilities.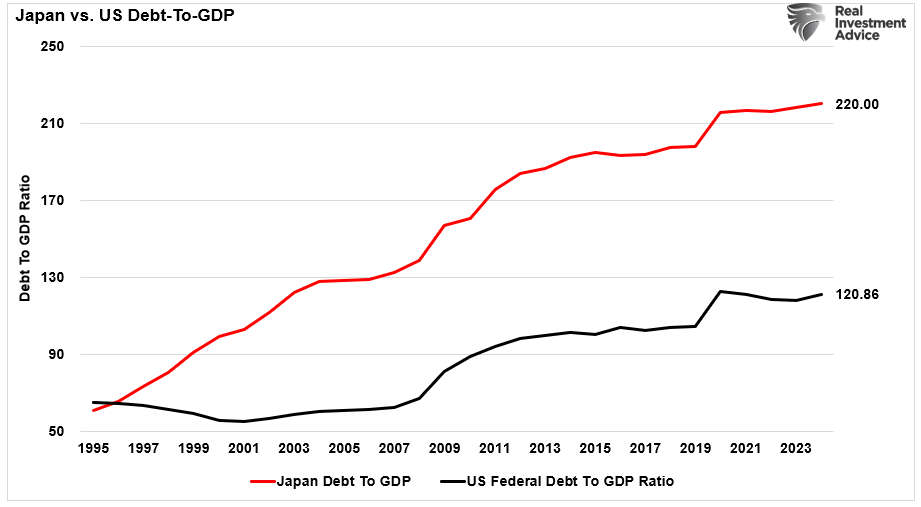
Case Study: A Closer Look
No examination of Japan’s net worth and debts of Japan is complete without analyzing the 2014 sales tax hike—a policy decision that exposed the fragility of the system. In April 2014, the government raised the consumption tax from 5% to 8% to address its fiscal gap, expecting higher revenue to offset the debt burden. Instead, the move triggered a sharp contraction in consumer spending, pushing the economy into recession. Retail sales plummeted, corporate profits dipped, and the government was forced to delay further tax hikes indefinitely. The episode underscored how sensitive Japan’s net worth and debts of Japan are to domestic confidence, particularly when private sector behavior is the only counterweight to public liabilities. The aftermath of the tax hike revealed another critical dynamic: regional disparities. While Tokyo and urban centers absorbed the shock with relative resilience, rural prefectures—already struggling with depopulation—saw public finances deteriorate further. Local governments, which rely heavily on national transfers, found their budgets strained as tax revenue fell. This case study highlights a core tension in Japan’s net worth and debts of Japan: national stability depends on regional stability, yet the tools to address local fiscal stress are limited."Japan’s debt isn’t the problem—it’s the solution. The real issue is whether the private sector can continue to absorb it without choking the economy. So far, the math has worked, but the demographics won’t." — Takatoshi Kato, former deputy governor of the Bank of Japan (2018)
| Factor | Estimated Impact on Net Worth and Debts of Japan |
|---|---|
| Consumption Tax Hike (2014) | Temporarily widened fiscal deficit by ~1.5% of GDP due to revenue shortfalls; delayed tax increases became a structural policy. |
| Bank of Japan’s QE Programs | Reduced long-term borrowing costs but inflated asset prices, creating a wealth gap between urban and rural households. |
| Aging Population | Increases pension and healthcare costs, pressuring primary surpluses; estimated to add $1 trillion+ to debt over the next decade if unaddressed. |
What This Means Going Forward
The interplay between Japan’s net worth and debts of Japan will define its economic trajectory in the 2020s. The most immediate challenge is demographic decline, which threatens to shrink the tax base while increasing social welfare expenditures. Without structural reforms—such as immigration policies, labor force participation increases, or productivity gains—the private wealth that currently offsets public debt may not be sufficient. The second critical variable is global monetary policy. If the U.S. Federal Reserve or the European Central Bank tightens aggressively, Japan’s ultra-low rates could come under pressure, forcing a reckoning with its net worth and debts of Japan. There is also the geopolitical dimension. Japan’s reliance on domestic debt ownership makes it less vulnerable to foreign creditor pressure, but it also insulates the government from external discipline. As China’s economic influence grows in Asia, Japan may face diplomatic trade-offs between debt sustainability and regional alliances. The question is whether Tokyo can leverage its net worth and debts of Japan as a strategic asset—for example, by using its savings surplus to invest in infrastructure or technology—or if it will remain trapped in a low-growth equilibrium.
Conclusion
Japan’s net worth and debts of Japan are a masterclass in fiscal alchemy, where liabilities and assets exist in a delicate balance. The country’s ability to sustain this equilibrium for decades is a testament to its institutional resilience, but it is not a model easily replicable elsewhere. The lesson for other nations is clear: debt is only as dangerous as the system that holds it. Japan’s case shows that with the right mix of monetary policy, domestic ownership, and private sector buffers, even extreme debt levels can be managed—provided the underlying economy remains stable. Yet stability is not forever. The pressures of an aging society, stagnant wages, and global monetary shifts mean Japan’s net worth and debts of Japan will face unprecedented tests in the coming years. The outcome will hinge on whether the nation can adapt its economic model without destabilizing the very mechanisms that have kept it afloat. For now, Japan’s paradox remains intact: a debt burden that terrifies outsiders, yet a wealth reserve that keeps the system running.Comprehensive FAQs
Q: How does Japan’s net worth and debts of Japan compare to other advanced economies?
Japan’s public debt-to-GDP ratio (~260%) is the highest among G7 nations, but its private sector wealth (households + corporations) is also the largest, creating a unique offset. The U.S. and Eurozone have lower debt ratios but face higher external debt exposure and less domestic absorption capacity.
Q: Could Japan ever default on its debt?
Default is extremely unlikely in the short to medium term due to domestic ownership of debt and the Bank of Japan’s role as a backstop. However, a sudden loss of confidence—such as a spike in JGB yields—could force a crisis if the private sector stops absorbing new issuance.
Q: Why doesn’t Japan raise taxes to reduce its debt?
Past attempts (e.g., the 2014 consumption tax hike) backfired, triggering recessions. Japan’s tax system is also regressive, with heavy reliance on consumption taxes that disproportionately affect lower-income households. Structural reforms to broaden the tax base (e.g., property or wealth taxes) have stalled due to political resistance.
Q: How do Japanese households afford such high debt levels?
Household debt in Japan is lower than in the U.S. or Europe (around 60% of disposable income vs. 100%+ elsewhere). The key factors are high savings rates (over 30% of income), real estate ownership, and pension funds, which act as collateral and income streams.
Q: What happens if the Bank of Japan stops buying government bonds?
If the BoJ ends its yield curve control, JGB yields could rise sharply, increasing debt service costs. Estimates suggest a 1% yield increase could add ~2% of GDP annually to the deficit, forcing painful austerity or tax hikes.
Q: Are there any bright spots in Japan’s net worth and debts of Japan?
Yes. Japan’s corporate cash hoard (~$1.5 trillion) could fund innovation if deployed, and its foreign reserves (~$1.3 trillion) provide a buffer against external shocks. Additionally, low unemployment (around 2.5%) suggests labor market flexibility, though wage stagnation remains a challenge.
Q: Could Japan’s model work for other countries?
Unlikely. Japan’s success depends on unique factors: an aging population with high savings, a homogeneous domestic debt market, and a central bank willing to act as a lender of last resort. Most economies lack this combination, making Japan’s approach highly context-specific.
Q: What’s the biggest risk to Japan’s net worth and debts of Japan?
The demographic time bomb—a shrinking workforce supporting a growing retiree population—poses the greatest long-term threat. Without immigration or productivity gains, Japan’s primary surpluses could turn into deficits within a decade, forcing a reckoning with its debt dynamics.
