Breaking Down the Numbers
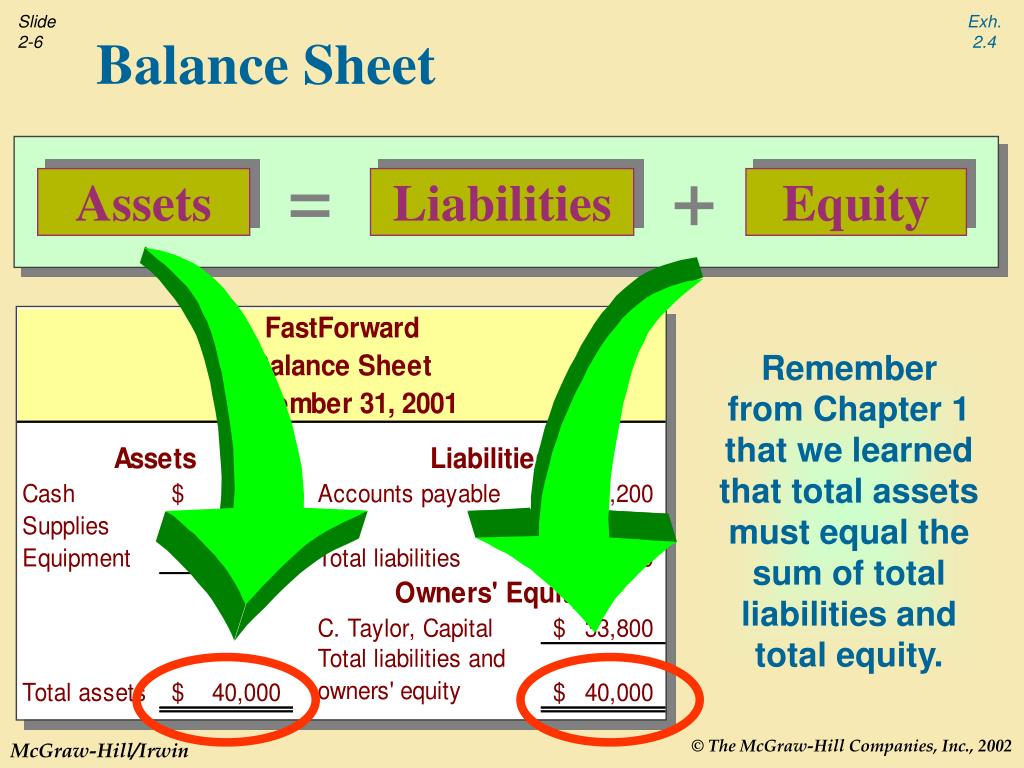
The balance sheet’s fundamental equation—assets = liabilities + equity—is non-negotiable. It’s the bedrock of double-entry accounting, ensuring every transaction is recorded twice. When someone asks does total liabilities plus equity equal net worth?, they’re essentially asking whether liabilities + (assets – liabilities) equals assets – liabilities. Mathematically, that simplifies to assets = assets, which is true but trivial. The real question is whether this accounting identity aligns with the practical concept of net worth. For individuals, net worth is a personal wealth metric; for corporations, equity is a financial claim. The two serve different purposes. Net worth answers, “What’s left if I sold everything and paid off debts?” Equity answers, “What do shareholders own after settling all obligations?” The overlap exists only when the entity is a single-person business, where personal net worth and corporate equity blur. The confusion deepens when considering different types of equity. Common stock, retained earnings, and treasury stock all contribute to shareholders’ equity, but their relationship to net worth varies. For a sole proprietorship, equity and net worth are functionally identical because the business’s assets and liabilities are the proprietor’s assets and liabilities. For a corporation, however, equity is a subset of the broader financial picture. A company might have substantial net worth (assets exceeding liabilities) but still issue equity that doesn’t reflect the full residual value—think of a firm with hidden intangible assets or off-balance-sheet liabilities. The question is total liabilities and equity the same as net worth? thus hinges on whether you’re analyzing a personal balance sheet or a corporate one. The answer shifts depending on the entity’s structure and the context of the inquiry.The Verified Baseline
Publicly available financial statements provide the clearest answers. For a corporation, the balance sheet explicitly lists assets, liabilities, and equity. The equity section breaks down into components like paid-in capital, retained earnings, and accumulated other comprehensive income. These figures are audited and verified, offering a transparent view of the company’s financial position. When calculating net worth in a corporate context, you subtract total liabilities from total assets—the equity figure already represents this difference. There’s no need to add liabilities to equity; doing so would misrepresent the company’s financial health. For example, if a company reports assets of $500 million, liabilities of $300 million, and equity of $200 million, the net worth (or shareholders’ equity) is already $200 million. Adding liabilities to equity would yield $500 million, which matches total assets—a correct but meaningless restatement. For individuals, the IRS and financial advisors use net worth as a measure of financial standing. Here, equity isn’t a separate line item; it’s the outcome of subtracting liabilities from assets. The question is total liabilities and equity the same as net worth? doesn’t apply because equity isn’t a distinct category in personal finance. Instead, net worth is the equity in one’s personal balance sheet. This distinction is critical for tax purposes, estate planning, and creditworthiness assessments. For instance, a person with $1 million in assets and $600,000 in liabilities has a net worth of $400,000. There’s no “equity” figure to add to liabilities—net worth is the equity itself. The confusion arises when individuals try to apply corporate accounting terms to personal finances, where the frameworks differ fundamentally.What the Estimates Suggest
Industry estimates often blur the lines between personal and corporate finance, leading to speculative interpretations. For privately held businesses, equity valuation can be subjective, relying on methods like discounted cash flow or comparable company analysis. In these cases, the equity figure may not align neatly with the accounting definition, especially if the business has significant goodwill or intangible assets. Estimates for equity in such firms can vary widely, making it difficult to answer is total liabilities and equity the same as net worth? with precision. For example, a startup with $10 million in assets and $8 million in liabilities might have equity valued at $2 million on paper, but if its intellectual property is worth $5 million, the true net worth could be higher. Estimates here are inherently uncertain, relying on assumptions about future cash flows or market conditions. For high-net-worth individuals, the distinction between personal net worth and business equity becomes even more pronounced. A person might own a company where their personal net worth exceeds the company’s equity due to other investments or assets. In such cases, the question does total liabilities plus equity equal net worth? would only apply to the business portion of their finances, not their overall wealth. Financial advisors often use consolidated net worth statements that combine personal and business assets, further complicating the equation. For instance, a real estate investor with a portfolio valued at $20 million, $5 million in personal liabilities, and a business with $3 million in equity might have a net worth of $15 million—but the business’s equity alone wouldn’t reflect this. The estimates here depend on how assets and liabilities are categorized, whether they’re held personally or through entities.
Case Study: A Closer Look
Consider a mid-sized manufacturing firm with the following balance sheet (figures rounded for clarity): - Total Assets: $45 million - Total Liabilities: $20 million - Shareholders’ Equity: $25 million At first glance, the question is total liabilities and equity the same as net worth? seems to hold: $20 million (liabilities) + $25 million (equity) = $45 million, which matches total assets. But this is a tautology—it’s the accounting identity in action. The net worth of the company, from a shareholder perspective, is the $25 million equity. Adding liabilities back in doesn’t change the equity value; it merely restates the assets. The confusion arises when stakeholders focus on the $45 million total rather than the $25 million residual claim. For creditors, the $20 million in liabilities is a priority; for shareholders, the $25 million equity is the focus. The two perspectives aren’t interchangeable. This disconnect becomes critical during financial distress. Suppose the firm’s assets decline to $30 million due to market downturns, while liabilities remain at $20 million. Equity would then be $10 million—a 60% drop from its previous value. If creditors demand repayment, the company might liquidate assets to cover liabilities, leaving shareholders with nothing. Here, the question does total liabilities plus equity equal net worth? becomes moot because equity has turned negative (a deficit). The net worth is still assets minus liabilities ($10 million), but the equity figure now reflects insolvency. The case study underscores that equity is a dynamic measure tied to solvency, not a static wealth indicator like personal net worth.“Equity is the mirror of a company’s financial health, but it’s not the company itself. You can’t add debt to equity and expect to measure wealth—you’re just restating the assets. The real insight comes from understanding how equity changes over time, not how it interacts with liabilities in a mathematical abstraction.” — Mark R. Hussey, CPA and forensic accountant
| Factor | Estimated Impact |
|---|---|
| Asset Depreciation | Can reduce equity by up to 10–15% annually for capital-intensive firms, depending on useful life assumptions. |
| Off-Balance-Sheet Liabilities | Reportedly inflates net worth estimates by 5–20% if unrecorded obligations (e.g., guarantees, leases) are excluded. |
| Intangible Assets | May add 20–50% to equity value if goodwill or IP is undervalued, though this is speculative without market validation. |
| Debt Restructuring | Can artificially boost equity by converting liabilities to equity (e.g., debt-for-equity swaps), but long-term solvency may weaken. |
| Tax Liabilities | Accrued but unpaid taxes can reduce equity by 3–10% if not reflected in financial statements, depending on jurisdiction. |
What This Means Going Forward
The question is total liabilities and equity the same as net worth? reveals a fundamental gap between accounting theory and practical financial analysis. For businesses, equity is a component of the balance sheet, not a standalone wealth metric. Adding liabilities to equity doesn’t yield net worth; it restates assets. The confusion persists because laypeople and even some professionals treat equity as if it were independent of liabilities, when in reality, it’s the residual after liabilities are accounted for. Moving forward, financial literacy efforts should emphasize the difference between accounting identities (assets = liabilities + equity) and economic outcomes (net worth = assets – liabilities). This distinction is critical for investors, creditors, and policymakers who rely on financial statements to assess risk. The implications extend beyond semantics. Misapplying the relationship between liabilities, equity, and net worth can lead to poor capital structure decisions. For example, a company might overlever (take on excessive debt) under the mistaken belief that equity can absorb the risk, only to find that its net worth erodes faster than anticipated. Conversely, conservative entities might underinvest due to a misunderstanding of how equity and debt interact. The key is recognizing that equity is a function of assets and liabilities, not a separate variable. When asking does total liabilities plus equity equal net worth?, the answer is yes—but only in the trivial sense that it equals assets. The meaningful question is how equity changes as liabilities fluctuate, and how that affects the company’s ability to generate returns for shareholders.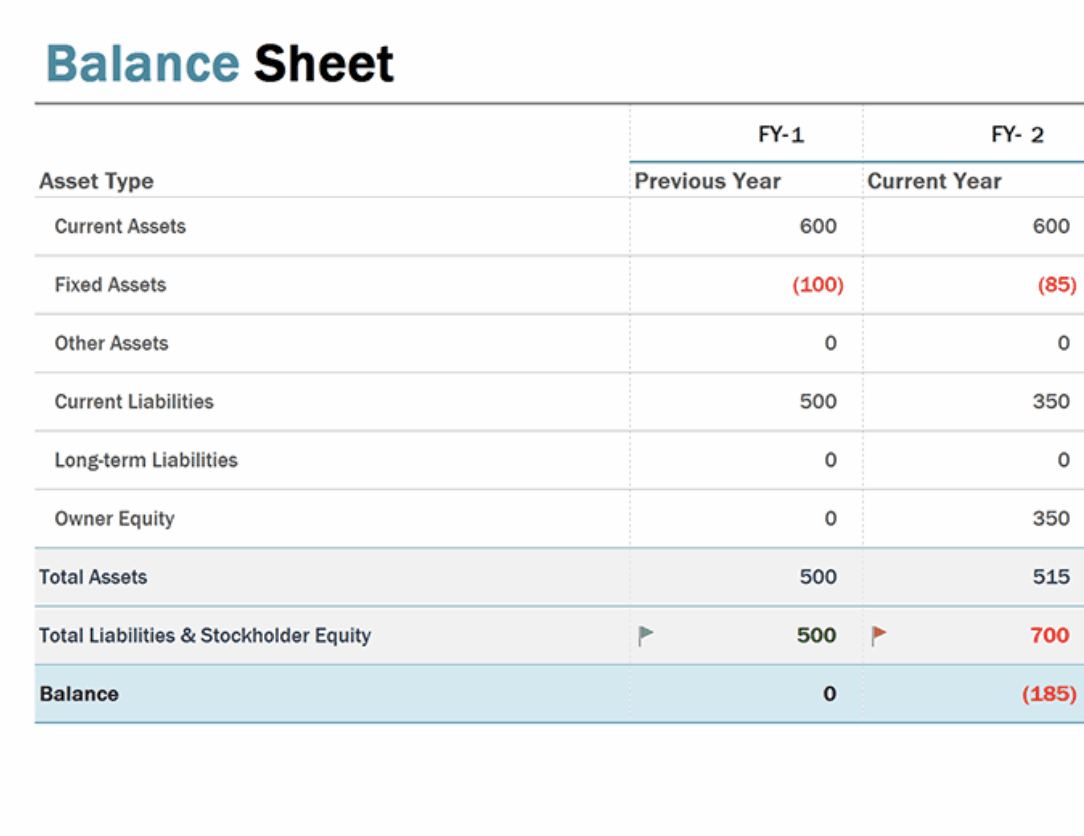
Conclusion
The question is total liabilities and equity the same as net worth? is a gateway to understanding the difference between accounting mechanics and economic reality. Equity and net worth are closely related but serve distinct purposes. Equity is a balance sheet line item; net worth is a measure of wealth. One is a snapshot of a moment in time; the other is a dynamic assessment of solvency and value. The confusion arises when the two are conflated, leading to misinterpretations of financial health. For individuals, net worth is straightforward: what you own minus what you owe. For corporations, equity is a claim on assets after liabilities, and adding liabilities to equity doesn’t change its fundamental nature. The takeaway is simple: equity is not an independent variable in the net worth equation. It’s the result of the assets-liabilities relationship, and treating it otherwise risks obscuring the true financial picture. The deeper lesson lies in precision. Financial discussions often mix personal and corporate contexts, blurring the lines between net worth and equity. Clarity requires recognizing that is total liabilities and equity the same as net worth? is a question with two answers: mathematically, yes, but only because it restates assets; practically, no, because equity and net worth are distinct concepts serving different analytical purposes. As financial markets grow more complex—with leveraged entities, off-balance-sheet transactions, and hybrid capital structures—the need for this distinction sharpens. Whether you’re evaluating a startup’s valuation or assessing your own financial standing, the principle remains: equity and net worth are not interchangeable. Understanding their relationship is the first step toward accurate financial decision-making.Comprehensive FAQs
Q: If equity equals assets minus liabilities, why can’t I just add liabilities to equity to get net worth?
You can mathematically, but it’s redundant. Equity is already the residual after subtracting liabilities from assets. Adding liabilities back in gives you total assets, not net worth. The confusion stems from treating equity as a standalone figure rather than the result of the assets-liabilities relationship. Net worth is specifically assets minus liabilities, which is identical to equity in a corporate context—but the two terms serve different purposes in analysis.
Q: Does this apply to personal finance the same way?
No. In personal finance, there’s no separate “equity” line item—net worth is the equity in your personal balance sheet. The question is total liabilities and equity the same as net worth? doesn’t apply because equity isn’t a distinct category. Instead, net worth is calculated as total assets minus total liabilities, which is analogous to corporate equity but framed differently. The terms align only when you’re discussing a single-owner business, where personal and business finances are indistinguishable.
Q: Can equity ever be negative, and what does that mean for net worth?
Yes, equity can be negative when liabilities exceed assets—a state called insolvency. In this case, net worth is also negative, reflecting a deficit. For corporations, negative equity signals financial distress, while for individuals, it may trigger bankruptcy proceedings. The key difference is that corporate equity can be negative while the company’s assets still have liquidation value; personal net worth is a direct reflection of solvency. The question does total liabilities plus equity equal net worth? still holds mathematically, but the negative equity highlights that the company’s net worth is equally negative.
Q: How do intangible assets affect the relationship between equity and net worth?
Intangible assets (e.g., patents, trademarks, goodwill) can inflate equity beyond what’s reflected in tangible assets. If these assets are undervalued or omitted from financial statements, the reported equity may understate the true net worth. For example, a tech firm with $100 million in book equity but $300 million in intangible assets might have a net worth closer to $400 million. The question is total liabilities and equity the same as net worth? becomes more complex because equity may not fully capture the economic value of intangibles, especially in privately held companies where valuations are subjective.
Q: Why do some financial advisors use consolidated net worth statements that include both personal and business assets?
Consolidated net worth statements combine personal and business finances to provide a holistic view of an individual’s wealth. In this context, the business’s equity is treated as part of the overall net worth, but the calculation still follows the same principle: total assets (personal + business) minus total liabilities (personal + business). The question does total liabilities plus equity equal net worth? applies to the business portion alone, not the consolidated total. Advisors use this approach to avoid double-counting assets or liabilities when the individual and business are financially intertwined, such as in family-owned enterprises.
