
Breaking Down the Numbers
The balance sheet’s equity section is where the answer to "is retained earnings a liabilities" becomes clear. Retained earnings are the cumulative profits a company hasn’t distributed as dividends, minus any losses or prior-period adjustments. This pool of capital belongs to shareholders but isn’t a debt—it’s a retained asset, even if it’s not held in cash. For example, a company might reinvest $50 million in retained earnings to expand production. That $50 million isn’t a liability; it’s equity financing that avoids interest payments. The confusion arises when stakeholders view retained earnings as a "reserve" that must be managed like debt, rather than a flexible resource for reinvestment or dividend payouts. The tax implications further highlight the divide. In many jurisdictions, retained earnings are subject to corporate tax only once—when declared as dividends. By contrast, liabilities like loans or bonds incur interest expenses annually, compounding costs. This structural difference explains why tech giants like Apple or Microsoft hold billions in retained earnings: they defer taxes by reinvesting profits rather than paying them out. The misconception that retained earnings are liabilities often stems from treating them as a hidden obligation, when in reality, they’re a deferred asset waiting to be deployed. The key takeaway? Retained earnings are equity, not debt—but their strategic use can mimic the risks of liabilities if mismanaged.The Verified Baseline
Under GAAP and IFRS, retained earnings are explicitly categorized as shareholders’ equity, not liabilities. This classification is non-negotiable: the Financial Accounting Standards Board (FASB) and the International Accounting Standards Board (IASB) both define retained earnings as "the portion of stockholders’ equity that represents the cumulative net income of the company, less any dividends paid to shareholders." The distinction is critical for financial statements. A liability requires a future economic sacrifice—such as repaying a loan or settling a vendor invoice. Retained earnings, however, represent earned capital that can be used at the board’s discretion, whether for expansion, debt repayment, or share buybacks. The balance sheet equation—Assets = Liabilities + Equity—makes this clear. Retained earnings appear on the right side of the equation, alongside common stock and additional paid-in capital. Liabilities, meanwhile, sit on the left side, representing claims by creditors. The confusion sometimes arises because retained earnings can be negative (a deficit), which might visually resemble a liability. However, even in a deficit position, retained earnings remain equity, not debt. For instance, a company with $100 million in assets, $60 million in liabilities, and a $40 million deficit in retained earnings still has net equity of zero—not a liability. The deficit is a shortfall in equity, not an obligation to outsiders.What the Estimates Suggest
Industry estimates suggest that over 60% of publicly traded companies hold retained earnings exceeding 20% of their total equity. This figure varies by sector: capital-intensive industries like utilities or manufacturing often reinvest heavily, while tech firms may hoard cash to avoid taxes. For example, a mid-sized manufacturing firm might report retained earnings of £150 million to £200 million, yet classify only £50 million as current liabilities for payables. The discrepancy underscores how retained earnings function as a low-cost financing tool. Private equity firms, in particular, target companies with substantial retained earnings because they can be deployed without diluting ownership or incurring debt. Analysts warn, however, that treating retained earnings as a debt substitute carries risks. If a company relies too heavily on retained earnings to fund operations, it may face liquidity constraints during downturns. For instance, a retail chain with $300 million in retained earnings but $400 million in current liabilities could still be insolvent if it can’t convert assets into cash quickly. The lesson? Retained earnings are equity, but their operational use can create liabilities-like pressures. This duality is why some financial models adjust retained earnings for "economic liabilities"—essentially treating them as a contingent obligation when they fund risky ventures. The bottom line: retained earnings are not liabilities, but their deployment can mirror liability risks.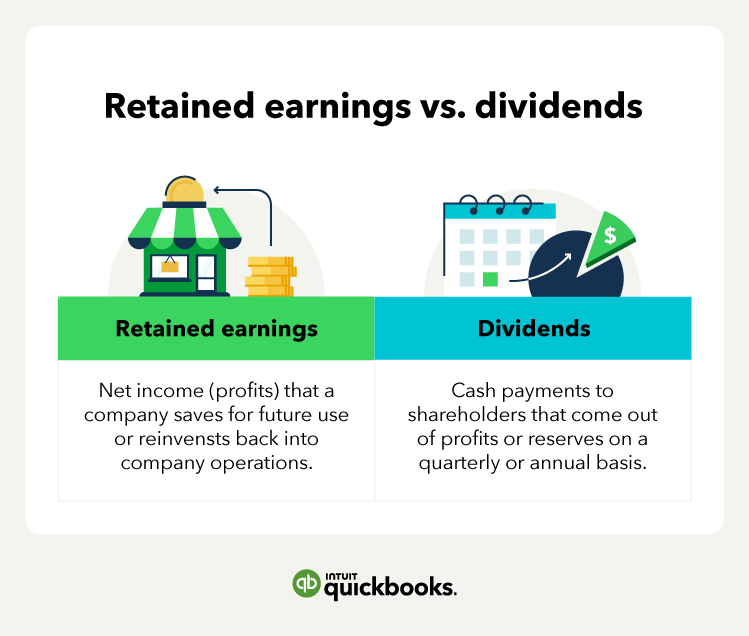
Case Study: A Closer Look
Consider the 2018 financial restructuring of General Electric (GE), where retained earnings played a pivotal but misunderstood role. GE’s balance sheet showed $40 billion in retained earnings alongside $120 billion in long-term debt—a ratio that led some investors to question whether the retained earnings were effectively backstopping liabilities. The reality was more nuanced: GE’s retained earnings were equity, but the company used them to fund dividends and share buybacks, which in turn supported its credit rating. Critics argued that the retained earnings were being treated like a liquidity buffer, not pure equity. This perception contributed to GE’s credit downgrades, even though the retained earnings themselves weren’t liabilities. The case highlights how context transforms accounting classifications. While retained earnings remained equity on paper, their use to prop up debt markets created a perception of liability. This blurring of lines is why regulators and auditors scrutinize how companies deploy retained earnings. For GE, the solution involved issuing new equity to reduce debt, but the episode revealed how retained earnings can become de facto liabilities when misapplied. The lesson? The answer to "is retained earnings a liabilities" depends on how they’re used—not just how they’re classified."Retained earnings are equity, but their strategic deployment can create risks indistinguishable from liabilities. The challenge for boards is to recognize the difference before markets do." — Mark Zandi, Chief Economist at Moody’s Analytics
| Factor | Estimated Impact |
|---|---|
| Tax Deferral | Retained earnings reduce taxable income when reinvested, saving $5M–$20M annually for a mid-cap firm (varies by jurisdiction). |
| Dividend Constraints | Over-reliance on retained earnings for dividends can trigger shareholder lawsuits if payouts exceed sustainable cash flows. |
| Credit Ratings | Agencies like S&P may downgrade firms if retained earnings are used to mask debt, even if they’re technically equity. |
| Bankruptcy Risk | Negative retained earnings (deficits) increase insolvency risk by eroding equity buffers, though they’re not liabilities. |
| M&A Valuation | Buyers may undervalue targets with high retained earnings if they assume the capital is locked in liabilities-like uses rather than growth. |
What This Means Going Forward
The debate over "is retained earnings a liabilities" isn’t just academic—it shapes corporate strategy. Companies with strong retained earnings can avoid debt, but they must communicate how they’ll deploy the capital to avoid market skepticism. For example, a biotech firm with $1 billion in retained earnings might use it to fund R&D, while an industrial conglomerate might plow it into acquisitions. The difference in perception can affect valuation: investors may penalize firms that hoard retained earnings without clear plans, assuming they’re self-financing liabilities rather than equity. Regulators are also tightening scrutiny. The SEC, for instance, has flagged instances where firms labeled retained earnings as "restricted" to obscure debt-like obligations. The message is clear: retained earnings are equity, but their operational treatment must align with that classification. For private companies, this means transparency in financial disclosures; for public firms, it means aligning dividend policies with sustainable cash flows. The future may see more standardized disclosures separating retained earnings into "available for reinvestment" and "committed to liabilities-like uses," further clarifying the distinction.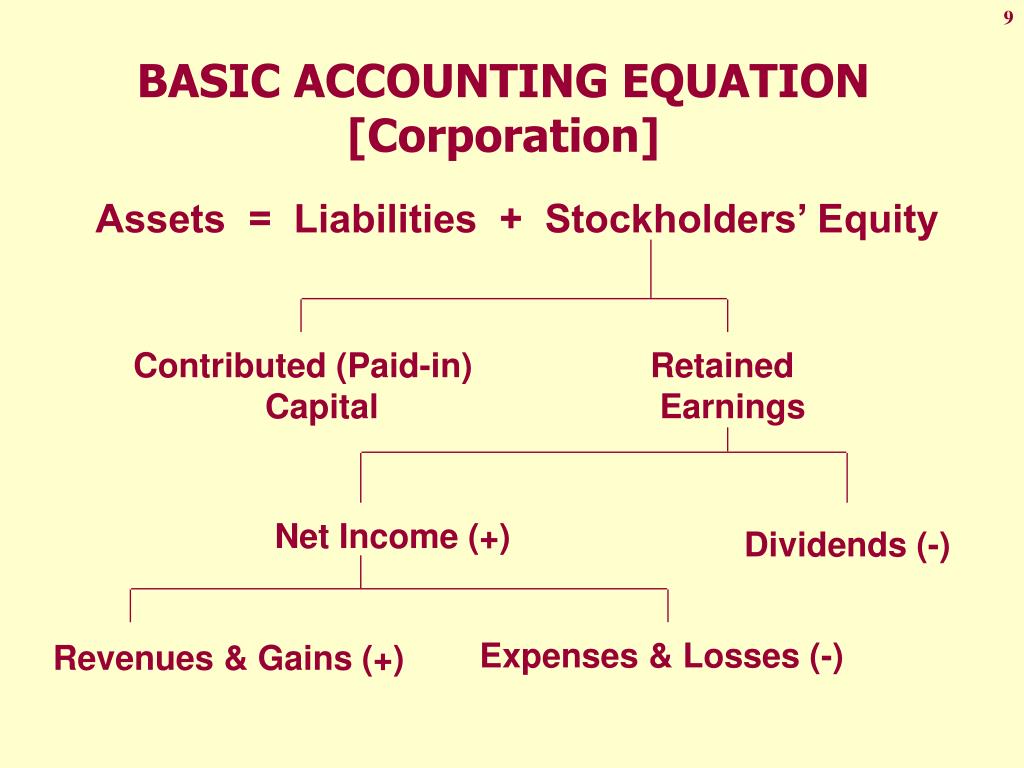
Conclusion
The answer to "is retained earnings a liabilities" is no—but the question reveals deeper truths about financial strategy. Retained earnings are equity, not debt, and their power lies in flexibility. However, their misuse can create risks that mimic liabilities, from tax inefficiencies to credit downgrades. The GE case study alone demonstrates how context reshapes accounting classifications. Moving forward, companies must treat retained earnings as strategic equity, not a passive reserve. For investors, the takeaway is to look beyond the label: retained earnings are a tool, not an obligation—and their value depends on how they’re wielded. The next frontier in financial reporting may involve real-time equity tracking, where retained earnings are dynamically categorized based on their intended use. Until then, the onus is on boards to ensure retained earnings are deployed as equity, not disguised liabilities. The line between the two isn’t always clear—but understanding it is the difference between financial health and hidden risk.Comprehensive FAQs
Q: Can retained earnings ever become a liability?
A: No, retained earnings remain equity under GAAP/IFRS. However, if a company pledges retained earnings as collateral for debt or uses them to guarantee obligations, creditors may treat them as a de facto liability in risk assessments. The accounting classification stays the same, but the economic treatment changes.
Q: How do negative retained earnings (deficits) affect a company?
A: Negative retained earnings reduce shareholders’ equity, increasing the risk of insolvency. While they’re not liabilities, they erode the equity cushion between assets and creditor claims. For example, a company with $100M in assets, $80M in liabilities, and a $30M deficit has no net equity, making it more vulnerable to bankruptcy.
Q: Do retained earnings impact a company’s credit rating?
A: Indirectly. Credit agencies like Moody’s or S&P assess whether retained earnings are being used to mask debt or fund unsustainable growth. If a firm relies on retained earnings to pay dividends while taking on new debt, raters may downgrade the company, assuming the retained earnings are effectively liabilities in practice.
Q: Can a company distribute retained earnings as dividends?
A: Yes, but only if the payout doesn’t exceed accumulated profits. Some jurisdictions require companies to maintain a legal capital reserve (e.g., 25% of retained earnings) before distributing dividends. Missteps here can lead to shareholder lawsuits or regulatory penalties, as courts may treat excessive dividends as improper liability transfers disguised as equity.
Q: How do private companies handle retained earnings differently than public firms?
A: Private companies often have less transparency around retained earnings, sometimes using them to fund operations without disclosing the strategy. Public firms, meanwhile, face SEC scrutiny and must detail how retained earnings are deployed—whether for reinvestment, debt repayment, or buybacks. This transparency forces public companies to treat retained earnings more like strategic equity, while private firms may treat them as a flexible pool with fewer constraints.
