The Complete Overview of Net Worth vs. Salary
The core confusion stems from how each term functions in personal finance. Salary is a periodic payment—typically monthly or annually—for services rendered, usually through employment. It’s a measure of income, not wealth. Net worth, by contrast, is a cumulative figure: the total value of everything you own (assets like cash, property, investments) minus everything you owe (liabilities like mortgages, loans, credit card debt). While salary fuels your ability to acquire assets, net worth reflects the end result of those financial decisions over time. The relationship between the two isn’t linear. A high salary doesn’t guarantee high net worth, nor does a low salary preclude it. For example, a surgeon with a $400,000 salary might have a net worth of $2 million due to decades of saving and investments, while a freelance designer earning $80,000 annually could have a net worth of $1.5 million if they’ve avoided debt and invested wisely. The question "Is net worth the same as salary?" ignores this critical distinction: one is a snapshot; the other is a moving target.Historical Background and Evolution
The modern concept of net worth traces back to 18th-century accounting practices, where merchants and landowners tracked their assets and liabilities to assess financial health. Salary, as a structured compensation model, emerged later with the rise of industrialization and formal employment contracts in the 19th century. Before then, income was often tied to land ownership, trade profits, or barter systems—none of which directly translated to what we now call net worth. The post-World War II era solidified the distinction between the two. The rise of white-collar jobs, corporate salaries, and consumer credit created a culture where income became a proxy for status, while net worth remained a private metric. By the 1980s, as financial markets democratized through mutual funds and retirement accounts, net worth became a more visible—and aspirational—goal. Today, the question "Is net worth the same as salary?" reflects a broader cultural shift: from measuring success by annual income to recognizing that wealth is built over time, not just earned in a paycheck.Core Mechanisms: How It Works
Salary operates on a cyclical basis. You earn it, spend it, and repeat. Net worth, however, is a residual product of how you manage that salary over years. For instance, if you earn $100,000 annually but spend $120,000 (including debt payments), your net worth will decline unless you offset the shortfall with asset appreciation or side income. Conversely, if you save $30,000 of that salary and invest it wisely, your net worth will grow even if your salary remains stagnant. The mechanics of net worth also include non-salary factors: inheritance, gifts, market fluctuations, and even lifestyle choices (e.g., buying a home vs. renting). A real estate boom can swell net worth without a salary increase, while a market crash can erode it regardless of income. This is why the question "Is net worth the same as salary?" is flawed—net worth is influenced by external forces, time horizons, and individual behavior, whereas salary is a direct exchange for labor.Key Benefits and Crucial Impact
Understanding the difference between net worth and salary is the first step in financial literacy. It clarifies why some high earners struggle with debt while others build generational wealth. Salary provides the means to live; net worth provides the means to thrive. The impact of this distinction is evident in retirement planning, where a high salary might not translate to sufficient savings if spending outpaces income growth. Meanwhile, a modest salary paired with frugality and asset accumulation can yield a comfortable net worth. The psychological effect is equally significant. Relying solely on salary as a measure of success can lead to impulsive spending, poor investment decisions, or career choices that prioritize short-term gains over long-term stability. Net worth, by contrast, offers a more holistic view of financial health—one that accounts for debt, liquidity, and future potential."A high salary is like a fast river—it can carry you far, but if you don’t build bridges (assets) along the way, you’ll still be adrift when the current slows." — Financial planner and author Tony Robbins (paraphrased from wealth-building principles)
Major Advantages
- Wealth accumulation over time. Net worth grows through compounding—assets generating returns, while salary is a finite exchange for time. The earlier you focus on net worth, the more leverage time provides.
- Debt resilience. A strong net worth acts as a buffer against financial shocks, allowing you to weather job losses or emergencies without relying solely on income.
- Investment flexibility. High net worth unlocks opportunities like real estate, private equity, or business ownership—avenues typically inaccessible on a salary alone.
- Tax efficiency. Assets held long-term (e.g., stocks, property) often benefit from lower capital gains taxes compared to taxable income from a high salary.
- Legacy planning. Net worth determines what you can pass down, whereas salary is a personal metric that ends with you.
Comparative Analysis
| Salary | Net Worth |
|---|---|
| Measured annually or monthly. | Measured as a single figure (assets minus liabilities). |
| Directly tied to employment or self-employment income. | Influenced by income, investments, debt, and external factors (e.g., market performance). |
| Can fluctuate with raises, bonuses, or job changes. | Grows slowly through consistent saving and asset appreciation. |
| Subject to immediate spending or tax obligations. | Benefits from tax-advantaged accounts (e.g., 401(k), IRA) and long-term growth. |
| Does not account for debt or liabilities. | Directly impacted by debt levels—high liabilities can drag net worth down regardless of salary. |
Future Trends and Innovations
As automation and gig economies reshape work, the relationship between salary and net worth is evolving. Traditional salary-based careers are giving way to project-based income, where net worth becomes even more critical for financial stability. Meanwhile, innovations like financial wellness platforms now track net worth in real time, integrating salary data with spending habits to provide actionable insights. The rise of passive income streams—dividends, rental yields, royalties—means net worth is increasingly decoupled from employment income. Future generations may prioritize building assets over chasing high salaries, especially as remote work and digital nomadism reduce reliance on geographic-based compensation. The question "Is net worth the same as salary?" will become obsolete as wealth-building strategies shift from income optimization to asset diversification.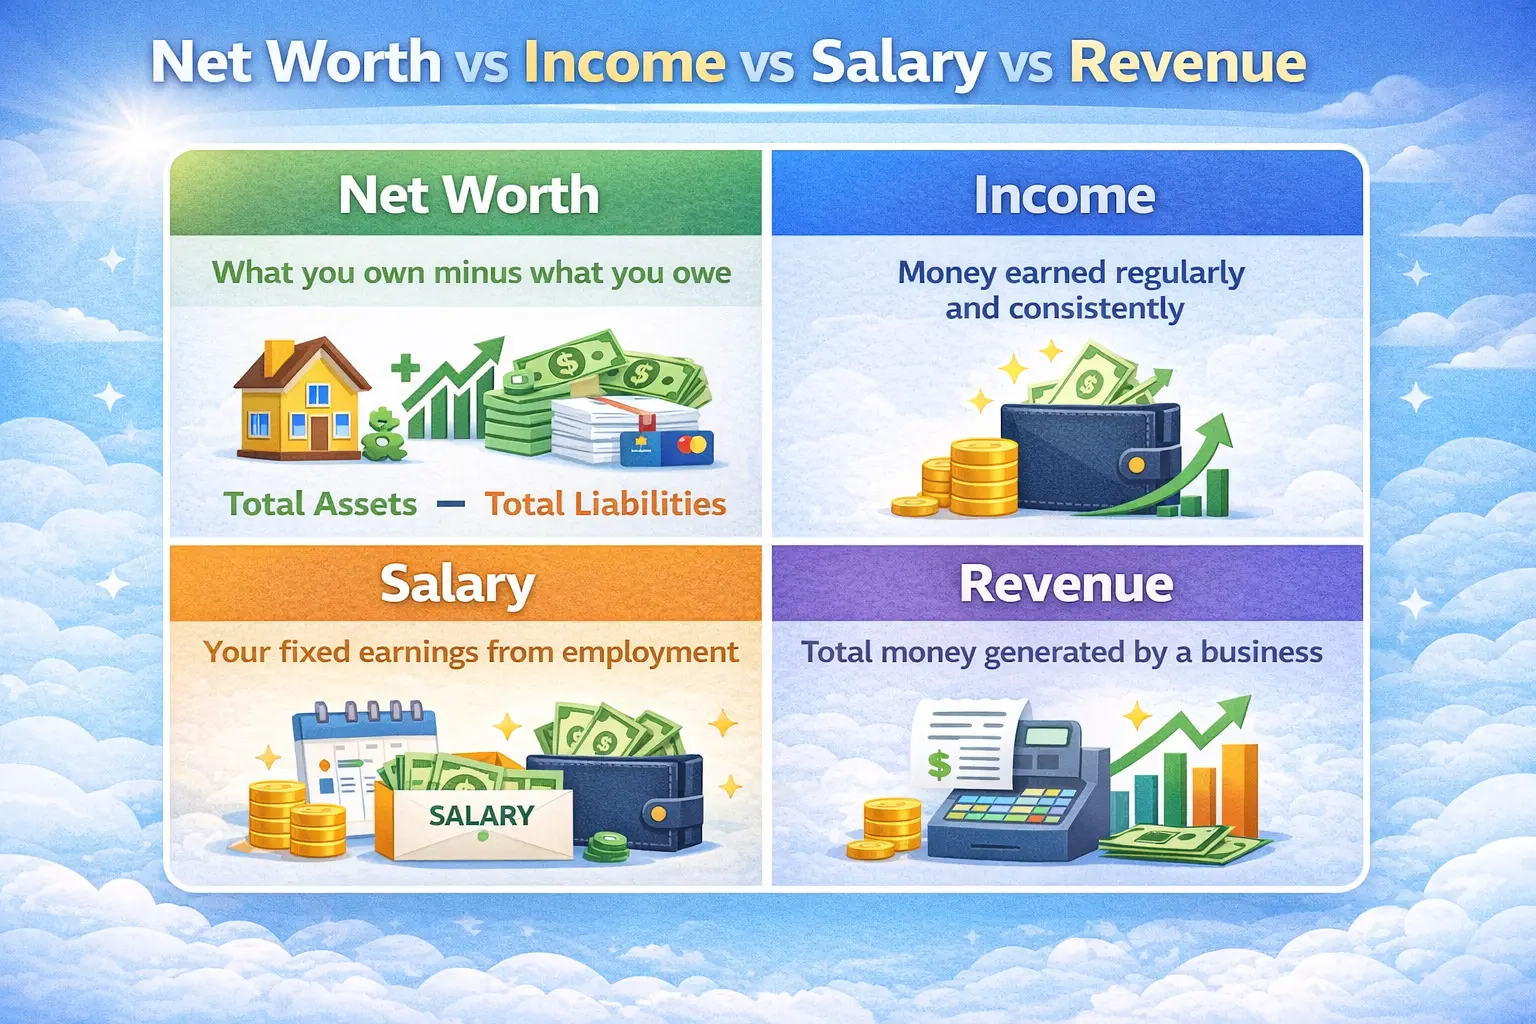
Conclusion
The answer to "Is net worth the same as salary?" is a resounding no—and the distinction matters more than ever. Salary is the engine; net worth is the destination. One fuels your daily life; the other secures your future. Ignoring this difference can lead to financial missteps, from overleveraging on a high salary to underestimating the power of long-term asset growth. The key is to treat them as complementary metrics: use salary to fund your lifestyle and build assets, but never mistake one for the other. For most people, the journey to financial independence begins with understanding this gap. It’s not about earning more—it’s about managing what you earn, protecting it, and growing it into something sustainable. The next time someone asks, "Is net worth the same as salary?" the response should be clear: no, and the difference defines your financial future.Comprehensive FAQs
Q: Can someone have a high salary but a low net worth?
A: Absolutely. High earners can accumulate debt (e.g., luxury purchases, student loans, mortgages) or spend aggressively, leaving little to build net worth. For example, a CEO earning $500,000 might have a net worth of $1 million if they live lavishly, while a teacher earning $70,000 could have a net worth of $1.5 million through disciplined saving and investments.
Q: Does a raise automatically increase net worth?
A: Not necessarily. A raise boosts your salary, but if you increase spending proportionally (or take on new debt), your net worth may not rise. Net worth grows when the raise allows you to save, invest, or pay down debt—converting income into assets.
Q: How often should I track my net worth?
A: Ideally, quarterly or annually. Tools like personal finance apps or spreadsheets make this easy. Tracking net worth helps identify trends (e.g., debt reduction, asset growth) and adjust strategies before small imbalances become major issues.
Q: Can net worth be negative?
A: Yes. If your liabilities (debts) exceed your assets, your net worth is negative. This is common among young professionals with student loans or mortgages but no significant savings or investments. Over time, paying down debt and building assets can turn a negative net worth positive.
Q: Does inheritance affect net worth?
A: Directly. Inheritance adds to your assets, increasing net worth. However, it’s not guaranteed—inheritance taxes or legal fees can reduce the amount. Strategically, inherited wealth should be integrated into your long-term financial plan to avoid lifestyle inflation that erodes its growth potential.
Q: Why do some people focus on salary while others prioritize net worth?
A: Life stages and goals dictate this. Younger professionals may prioritize salary for stability, while those nearing retirement focus on net worth to ensure financial security. High-net-worth individuals often shift from income optimization to asset preservation and legacy planning.
Q: How does inflation impact the relationship between salary and net worth?
A: Inflation erodes the purchasing power of salary over time, but net worth can hedge against it through assets like real estate or stocks. Historically, assets have outpaced inflation, making net worth a better long-term indicator of financial health than nominal salary growth.
