Breaking Down the Numbers
The core of the confusion lies in how each term is calculated—and what those calculations actually represent. Shareholders’ equity is derived from a company’s balance sheet: it’s the residual claim on assets after all liabilities (debts, payables, taxes) are deducted. For a publicly traded firm, this figure is publicly disclosed, but for private companies, it’s often an estimate based on valuation methods like discounted cash flow or comparable multiples. Net worth, by contrast, is a personal calculation: it includes tangible assets (real estate, vehicles), intangible assets (intellectual property, patents), and investments (stocks, bonds, crypto), minus debts. The key difference? Shareholders’ equity is a corporate accounting construct, while net worth is a personal financial metric. The two can align in specific scenarios, such as when a sole proprietor’s business assets equal their personal net worth. But even then, the treatment differs. A company’s equity can be diluted by issuing new shares, while an individual’s net worth might grow through appreciation or additional income streams. The real misalignment occurs with illiquid assets. A founder holding 10% of a pre-revenue startup might see their net worth skyrocket if the company’s valuation jumps—but the company’s shareholders’ equity remains tied to its actual financial performance, not its perceived potential. This disconnect has fueled debates over whether private equity valuations reflect reality or hype.The Verified Baseline
Publicly traded companies provide the clearest data points. For instance, Apple’s shareholders’ equity in 2023 was reported at $130 billion, based on its balance sheet. This figure doesn’t include the personal net worth of its executives or major shareholders—only what the company itself owns after debts. Conversely, Tim Cook’s net worth, while influenced by his Apple stock holdings, is a separate calculation that includes other assets like real estate and cash. The two are linked but not identical. Even when an individual’s primary asset is stock in a company they lead, their net worth isn’t the same as that company’s equity. Private companies complicate the picture further. Take a hypothetical biotech firm valued at $500 million with $100 million in debt. Its shareholders’ equity would be $400 million—but if the CEO owns 20% of the equity, their net worth might only reflect the liquidation value of those shares, not the inflated valuation. This is why private equity stakes often trade at discounts to their "official" valuations. The lesson? Shareholders’ equity is a corporate ledger entry; net worth is a personal wealth statement. One is an accounting truth; the other is a snapshot in time.What the Estimates Suggest
Industry estimates often conflate the two, particularly in startup ecosystems. A Series B venture-backed company might boast a $200 million valuation, implying its shareholders’ equity is similarly high—but this is a pre-money figure, not a balance sheet reality. The actual equity would depend on how much capital was raised and how it was allocated. Meanwhile, a founder’s net worth might balloon if their personal stake is marked up, even if the company’s underlying equity hasn’t grown. This is why private equity investors use terms like "fully diluted equity"—to account for potential future share issuance that could dilute existing stakes. The disconnect becomes glaring during downturns. During the 2022 tech correction, many private companies saw their equity valuations plummet, but founders’ net worths didn’t always reflect this—because their personal balance sheets might include other assets or debt structures that cushioned the blow. For example, a founder with $50 million in company stock and $30 million in personal cash might see their net worth drop by 20% if the stock loses value, but their liquidity remains intact. The company’s shareholders’ equity, however, would take a direct hit to its balance sheet. This is why financial advisors urge entrepreneurs to diversify personal assets—to insulate against corporate volatility.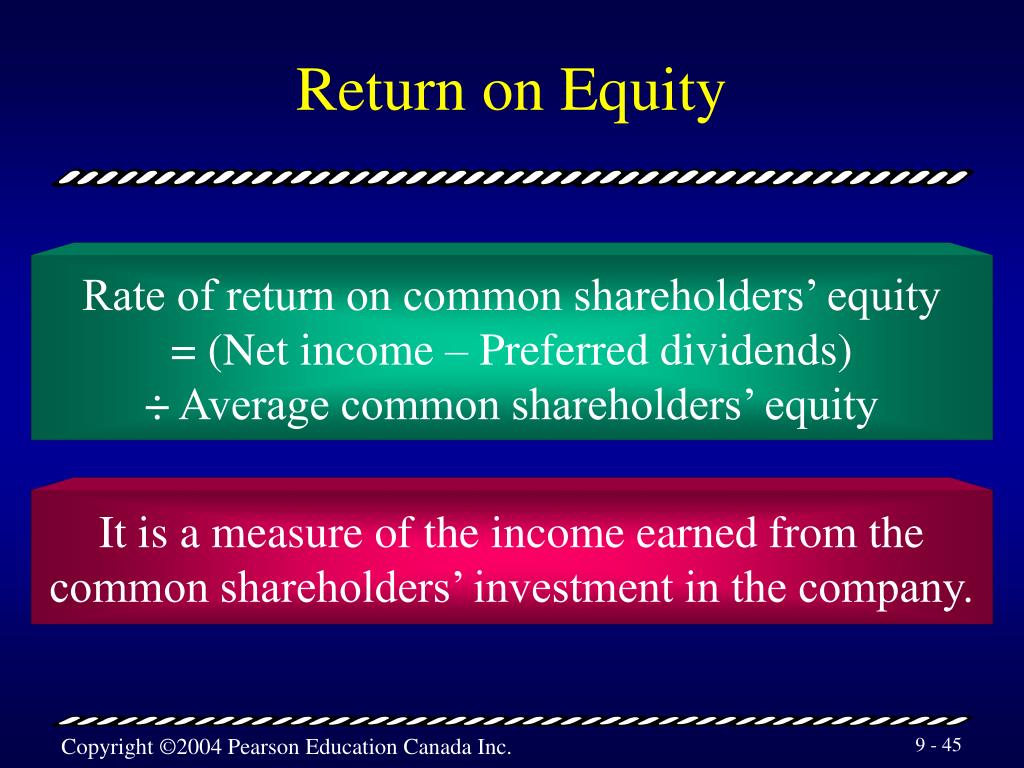
Case Study: A Closer Look
Consider the 2018 collapse of WeWork. Adam Neumann’s net worth reportedly peaked at $7 billion at its height, largely tied to his WeWork shares. But the company’s shareholders’ equity was a different story: its balance sheet showed negative equity by 2019, thanks to mounting losses and debt. Neumann’s personal wealth wasn’t just a reflection of WeWork’s equity—it was a bet on its future growth, one that turned out to be unsustainable. The lesson? Net worth can inflate based on perceived value, while shareholders’ equity is bound by hard financials. The discrepancy also played out in Neumann’s compensation. As CEO, he received shares valued at hundreds of millions, but those shares were subject to vesting schedules and dilution. His net worth might have appeared robust on paper, but the company’s equity was a red flag long before the public knew. This case underscores why "is net worth shareholders equity" isn’t just a theoretical question—it’s a matter of risk exposure."Shareholders’ equity is what you have after paying all your bills. Net worth is what you think you have after accounting for hype, options, and unproven assets." — David Sacks, former PayPal executive and investor
| Factor | Estimated Impact on Net Worth vs. Shareholders’ Equity |
|---|---|
| Illiquid Assets (e.g., private company stock) | Can inflate net worth without affecting shareholders’ equity until realized. |
| Debt Structure | Personal liabilities reduce net worth; corporate debt reduces shareholders’ equity equally. |
| Valuation Methods | Private equity valuations may overstate net worth; GAAP accounting reflects true equity. |
| Dilution Events | New share issuances reduce shareholders’ equity; may or may not impact founder net worth immediately. |
What This Means Going Forward
For individuals, the distinction matters when structuring personal finances. A founder with most of their wealth tied to a single company’s equity faces concentration risk—if the company’s equity tanks, their net worth can evaporate overnight. Diversification, whether through cash reserves, real estate, or other investments, acts as a buffer. Meanwhile, companies must ensure their equity reflects real financial health, not just market hype. The rise of ESG (Environmental, Social, and Governance) metrics has added another layer: a company’s equity might be strong on paper, but if its governance is weak, its true value could be at risk. Regulators are also paying closer attention. The SEC’s crackdown on SPAC valuations and private company disclosures stems from a recognition that inflated equity valuations don’t always translate to real net worth for shareholders. Similarly, tax authorities scrutinize whether personal asset allocations align with corporate equity structures—especially in cases of related-party transactions. The takeaway? Transparency in one doesn’t guarantee clarity in the other.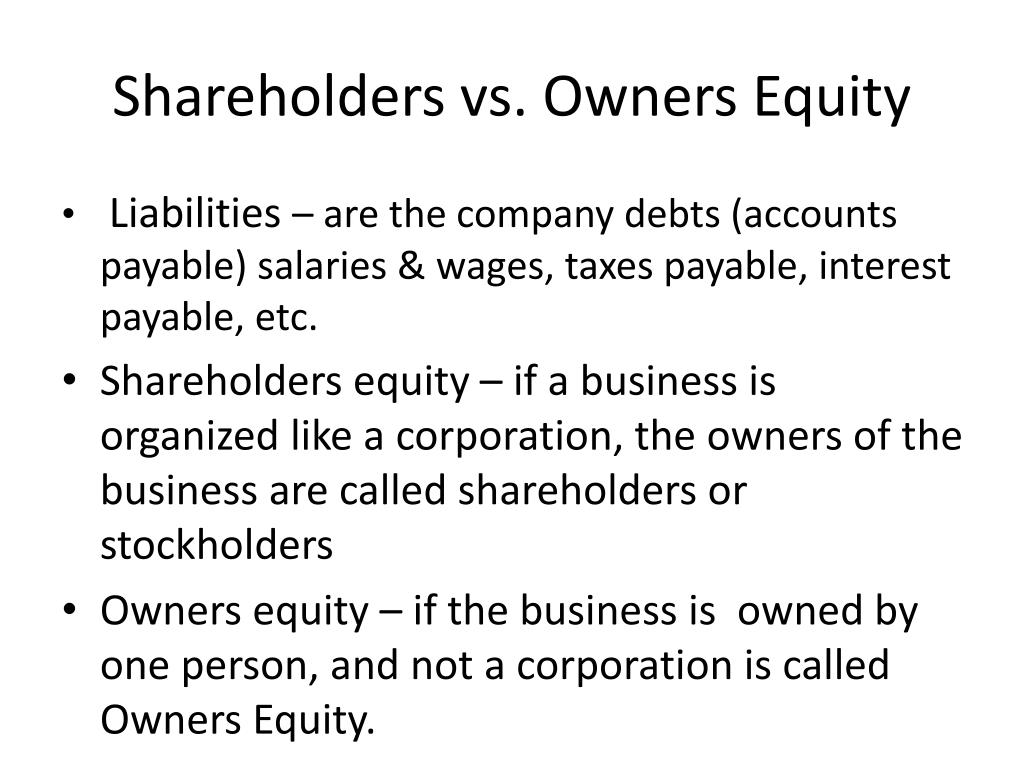
Conclusion
The question "is net worth shareholders equity" exposes a fundamental tension in finance: perception versus reality. While both measure what’s left after obligations, one is a corporate ledger entry and the other a personal wealth statement. The confusion persists because the two often move in parallel—until they don’t. For investors, this means due diligence must go beyond valuations to assess liquidity, debt, and true ownership stakes. For entrepreneurs, it’s a reminder that personal wealth and corporate equity are separate beasts, and one shouldn’t be mistaken for the other. The key to navigating this divide is rigor. Public companies provide the clearest data, but private ones require deeper analysis. Founders should treat their equity stakes as one part of a broader wealth strategy, not the sole determinant of their financial health. Meanwhile, shareholders should ask: Is this equity backed by real assets, or is it a bet on future growth? The answer will determine whether net worth and shareholders’ equity align—or diverge disastrously.Comprehensive FAQs
Q: Can an individual’s net worth ever equal a company’s shareholders’ equity?
A: Only in rare cases, such as a sole proprietorship where the business’s assets and liabilities directly mirror the owner’s personal balance sheet. Even then, accounting treatments (e.g., depreciation, tax liabilities) ensure they’re not identical. For most scenarios, the two are distinct.
Q: How do stock options affect the net worth vs. shareholders’ equity divide?
A: Stock options inflate an executive’s net worth if they’re vested and exercisable, but they don’t directly impact the company’s shareholders’ equity until exercised. Unexercised options are a contingent liability—they reduce equity only if converted to shares. This creates a lag where net worth can appear stronger than the company’s actual equity position.
Q: Why do private companies’ equity valuations often exceed their shareholders’ equity?
A: Private equity valuations are forward-looking, based on projected growth, while shareholders’ equity is backward-looking (assets minus liabilities). A pre-revenue startup might be valued at $1 billion based on IP or market potential, but its equity could be negative if it hasn’t generated revenue or secured funding to cover losses.
Q: Does a high net worth guarantee strong shareholders’ equity in a company?
A: No. A founder’s high net worth might stem from personal assets or illiquid stock, while the company’s equity could be weak due to debt or poor financial management. For example, a real estate tycoon who owns a struggling airline sees their personal net worth stay high, but the airline’s shareholders’ equity could be in freefall.
Q: How do dividends affect the relationship between net worth and shareholders’ equity?
A: Dividends reduce a company’s shareholders’ equity (as retained earnings drop) but can increase an investor’s net worth if reinvested or taken as cash. However, if dividends are unsustainable, they may signal financial distress—eroding both equity and long-term net worth.
Q: Can shareholders’ equity be negative while net worth remains positive?
A: Yes. A company with heavy debt (e.g., a leveraged buyout firm) might have negative equity, but its largest shareholders could still hold personal assets (like cash or other investments) that keep their net worth positive. This is common in distressed firms where creditors have priority over equity holders.
Q: What role do audits play in reconciling net worth and shareholders’ equity?
A: Audits ensure shareholders’ equity is accurately reported, but they don’t verify an individual’s net worth unless the person is also the company’s owner. For public companies, audits prevent equity fraud, but private firms often rely on fair value assessments, which can be subjective and lead to discrepancies between reported equity and true net worth.
Q: How does inflation impact the gap between net worth and shareholders’ equity?
A: Inflation erodes the real value of both, but the effects differ. Shareholders’ equity is tied to nominal assets/liabilities, while net worth can be hedged with inflation-resistant assets (e.g., real estate, commodities). A company’s equity might shrink in real terms, but a diversified individual’s net worth could hold up better if they’ve allocated assets accordingly.
