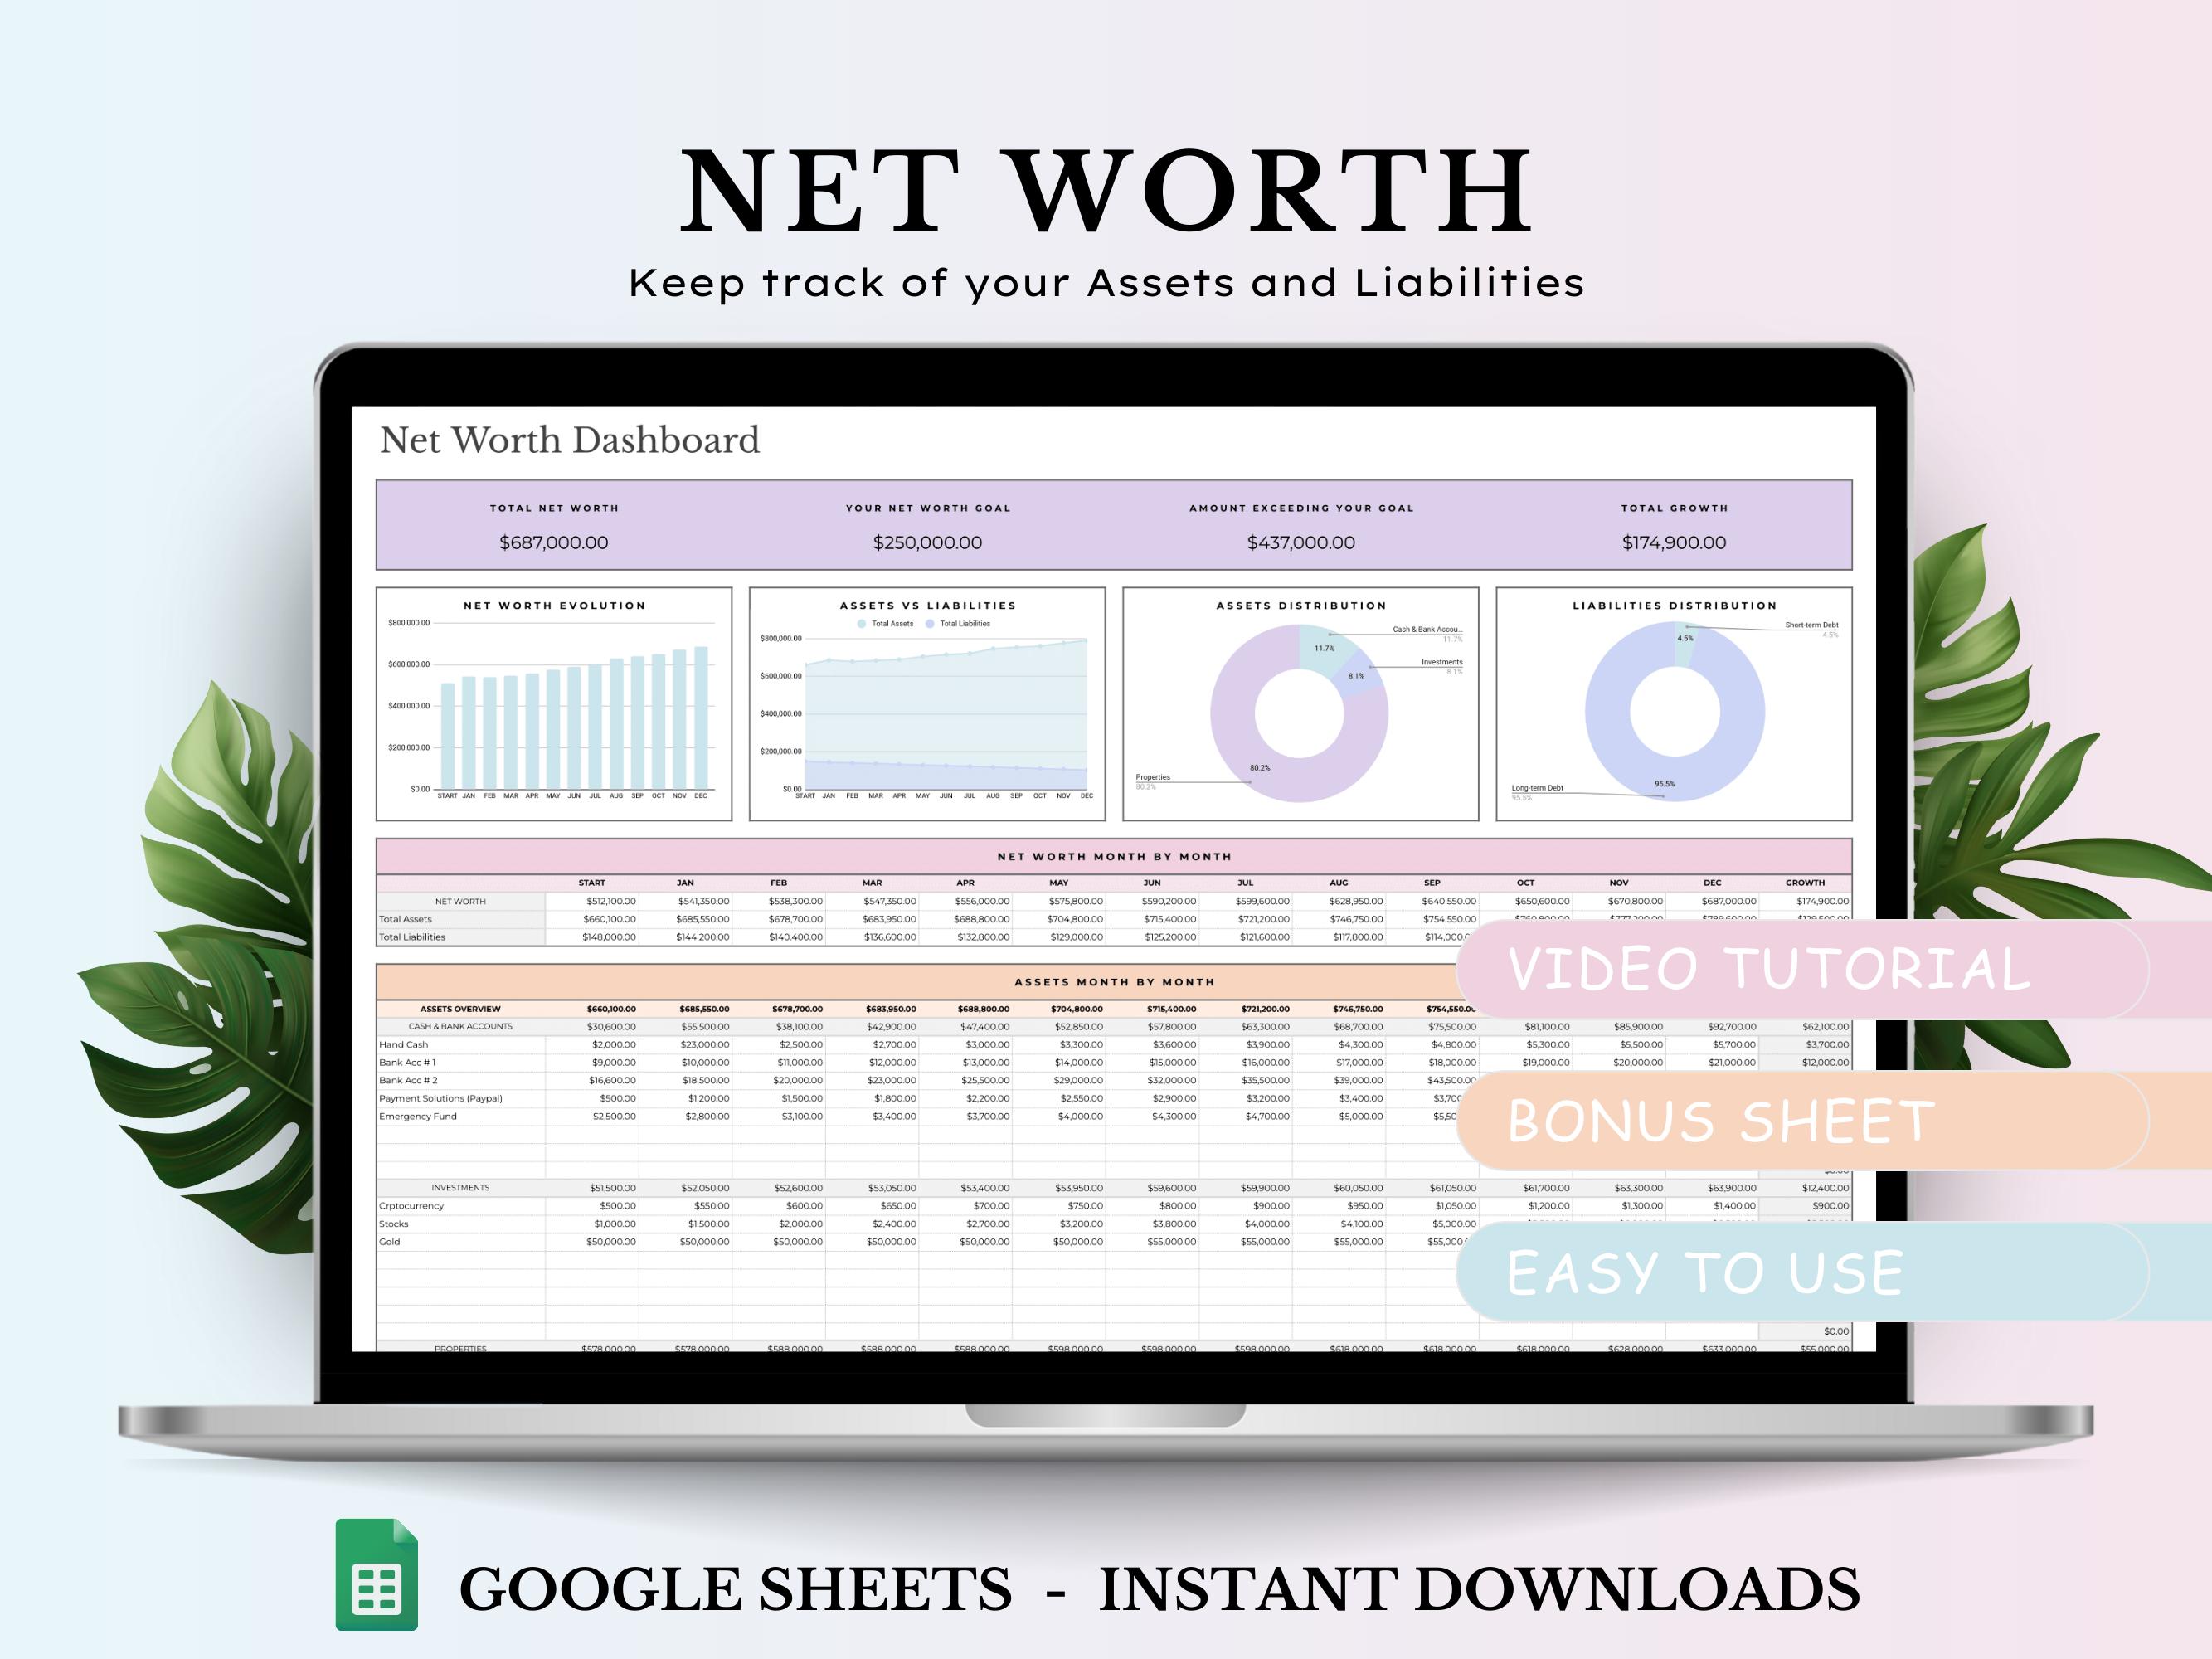
6 Things Worth Knowing About Is It Your Earned Income or Your Net Worth That Determines Wealth
The debate over what truly defines wealth isn’t just theoretical. It has practical implications for tax planning, investment decisions, and even lifestyle choices. Below are six critical insights that reshape how to think about financial health.1. Earned income is volatile; net worth is a lagging indicator
Earned income is the cash you receive from work, salaries, or business operations. It’s the lifeblood of daily expenses but also the most unpredictable measure of wealth. A single layoff, industry downturn, or health issue can slash income overnight. Net worth, however, smooths out these fluctuations by capturing the value of assets over time. A doctor earning $300,000 a year might have a net worth of $500,000 after years of saving, while a software engineer earning $150,000 could have a net worth of $3 million through stock options and real estate. The lesson? Income tells you what you make; net worth tells you what you’ve retained. The volatility of earned income is why financial planners often advise against relying solely on salary as a wealth metric. For example, a hedge fund manager’s income might spike to $50 million in a single year, only to vanish if the fund underperforms. Meanwhile, a teacher with a modest salary could see their net worth grow steadily through pension contributions and homeownership. The key difference is that net worth reflects accumulated value, not just current cash flow.2. Net worth compounds over time; income does not
One of the most overlooked truths about wealth is that net worth benefits from compounding—assets generate returns that, in turn, generate more returns. A $100,000 investment in a diversified portfolio could grow to $500,000 over 20 years with a 7% annual return, without requiring additional earned income. Income, by contrast, doesn’t compound in the same way. Even if you save $50,000 annually, that money must be deployed into assets to grow. The math behind this is simple: net worth is the sum of all your assets minus liabilities, and those assets (stocks, property, businesses) appreciate independently of your paycheck. This is why ultra-high-net-worth individuals often prioritize passive income streams—dividends, rental yields, or capital gains—over chasing higher salaries. Warren Buffett’s wealth isn’t tied to his annual income (reportedly around $100 million) but to his ownership stakes in companies like Coca-Cola and Apple, which have appreciated exponentially. The takeaway? Wealth is a function of asset growth, not just earnings.3. Debt distorts the relationship between income and net worth
Here’s where the debate gets messy: debt. A high earner with significant liabilities (mortgages, student loans, credit cards) may have a strong income but a negative or stagnant net worth. Conversely, someone with a modest income but no debt could see their net worth rise steadily through savings and investments. This is why net worth is often called the "true wealth metric"—it accounts for what you owe, not just what you earn. Consider two scenarios: - Scenario A: A lawyer earns $400,000 but has $300,000 in student loans and a $200,000 mortgage. Their net worth might be just $50,000. - Scenario B: A nurse earns $80,000, owns a home outright, and has $150,000 in retirement accounts. Their net worth could be $300,000. In both cases, income is a poor predictor of wealth. The lawyer’s high salary doesn’t translate to financial security because of debt, while the nurse’s lower income is offset by asset ownership. This is why financial independence is often measured by net worth multiples (e.g., 25x annual expenses) rather than income alone.4. Income inequality hides net worth inequality
Public discussions about wealth often focus on income disparities, but net worth tells a different story. According to Federal Reserve data, the top 1% of households by income hold roughly 35% of all privately held wealth, while the top 10% hold about 70%. The gap widens when examining net worth: the top 1% own nearly half of all liquid assets, including stocks, bonds, and business equity. This disparity exists because wealth compounds over generations—inherited assets, real estate appreciation, and stock market gains create a feedback loop that income alone cannot replicate. The implication? Income mobility is real, but wealth mobility is far rarer. A high earner can increase their salary, but without asset accumulation, their net worth may not keep pace. Meanwhile, someone with a modest income who invests consistently can outpace high earners who spend aggressively. This is why net worth is the better indicator of intergenerational wealth transfer.5. Passive income shifts the balance toward net worth
The ability to generate income from assets—rather than trading time for money—is where net worth outshines earned income. Passive income (dividends, royalties, rental yields) allows wealth to grow without active labor. For example: - A real estate investor with a $2 million portfolio might earn $100,000 annually in rental income without lifting a finger. - A tech founder who sold their company for $50 million now lives off dividends and capital gains, with no need for a salary. In these cases, net worth is the engine of future income. Earned income becomes secondary once assets are large enough to sustain a lifestyle. This is the principle behind financial independence, retire early (FIRE) movements—where the goal isn’t to maximize income but to build a net worth that can fund life indefinitely.6. Taxes and liquidity reveal the hidden costs of income vs. net worth
Income is taxed annually, often at progressive rates that rise with earnings. Net worth, however, benefits from tax-deferred growth (e.g., 401(k)s, IRAs) and lower capital gains rates when assets are sold. A high earner might pay 40%+ in marginal taxes on their salary, while a long-term investor pays 15-20% on capital gains. This structural advantage means that net worth grows more efficiently than income after taxes. Liquidity is another factor. A high income doesn’t guarantee access to cash—wage earners can face paycheck-to-paycheck struggles despite six-figure salaries. Net worth, by contrast, provides a buffer. Someone with a $1 million net worth can tap into assets (selling stocks, taking a loan against property) without relying on future income. This is why liquid net worth (cash, stocks, bonds) is more valuable than illiquid assets (e.g., a primary residence) in a crisis.
How These Facts Connect
The tension between earned income and net worth isn’t just semantic—it’s structural. Income is the fuel that allows you to build net worth, but net worth is the machine that generates sustainable wealth. High earners without asset discipline may never escape the cycle of high expenses and debt, while modest earners with strong savings and investment habits can accumulate fortunes. The data supports this: studies show that net worth grows faster for those who save and invest consistently, regardless of income level. The table below compares the two metrics across key dimensions:| Metric | Earned Income | Net Worth |
|---|---|---|
| Primary Driver | Labor, business operations | Asset appreciation, savings, investments |
| Volatility | High (dependent on employment, industry) | Lower (diversified assets smooth fluctuations) |
| Tax Efficiency | Progressive taxation (often 20-40%) | Lower rates on capital gains, tax-deferred growth |
| Wealth Transfer | Limited (income stops at retirement/death) | Intergenerational (assets pass to heirs) |
| Financial Freedom | Requires continuous work | Can fund lifestyle without labor |
Conclusion
The question of whether earned income or net worth determines wealth isn’t an either/or proposition. Both matter, but in different ways and at different stages of life. Early in your career, income is critical for building savings and paying debts. Later, net worth becomes the primary lever for financial independence. The mistake is assuming that high income alone equals wealth—or that low income precludes it. The truth lies in the interaction between the two: income funds asset accumulation, while assets generate future income. The path to lasting wealth requires a shift in mindset. Instead of chasing higher salaries, focus on converting income into assets. This means saving aggressively, investing wisely, and minimizing debt. The goal isn’t just to earn more but to own more—and to own assets that appreciate over time. In the end, it’s not the size of your paycheck that defines your financial future, but the size of your net worth.Comprehensive FAQs
Q: Can someone with a high income have a low net worth?
A: Absolutely. High earners often face lifestyle inflation, excessive debt (mortgages, student loans, luxury spending), or poor investment decisions. For example, a Wall Street banker earning $500,000 might have a net worth of just $200,000 if they live beyond their means. Net worth is a function of what you keep, not what you earn.
Q: Is net worth more important than income for retirement?
A: Yes. Retirement planning is primarily about asset decumulation, not income replacement. A $2 million net worth can generate $80,000 annually in withdrawals (4% rule), while a $200,000 salary might require working until 70 to maintain the same lifestyle. Net worth provides the buffer to cover gaps in Social Security or pensions.
Q: How do taxes affect the income vs. net worth debate?
A: Income is taxed annually at progressive rates (up to 37% in the U.S.), while net worth benefits from tax-deferred growth (401(k)s, IRAs) and lower capital gains rates (0-20%). A high earner paying 40% in taxes on $500,000 has less to invest than someone with a $100,000 income who saves 30% ($30,000) and invests it tax-efficiently.
Q: Can passive income replace earned income for wealth?
A: Yes, but it requires a critical net worth threshold. The Trinity Study suggests a 4% withdrawal rate is sustainable for retirement. To replace a $100,000 salary, you’d need $2.5 million in passive income-generating assets (e.g., dividends, rentals, business ownership). This is why ultra-high-net-worth individuals focus on asset-based income over salaries.
Q: What’s the biggest mistake people make when focusing only on income?
A: Assuming that higher income = higher wealth. Many high earners fall into the "treadmill effect"—earning more to keep up with expenses, never building assets. The fix? Automate savings, invest early, and prioritize net worth growth over short-term spending. Wealth is built in the gaps between income and expenses.
Q: How does homeownership affect the net worth vs. income debate?
A: Homeownership is a double-edged sword. It boosts net worth through equity but also ties up liquidity. A homeowner with a $500,000 mortgage may have a high net worth on paper, but the asset isn’t liquid. Renters, by contrast, can invest their housing costs elsewhere (stocks, ETFs), potentially growing wealth faster. The key is asset liquidity—not all net worth is equal.
Q: Are there cases where earned income is a better wealth indicator than net worth?
A: Rarely, but in early-career stages or for service-based professionals, income can be a leading indicator. A surgeon’s salary funds future asset accumulation, while a freelancer’s income volatility may require a higher net worth buffer. However, even in these cases, net worth eventually surpasses income as the primary wealth driver.
