7 Things Worth Knowing About Is an Annuity Purchase Figured in Net Worth
The debate over whether an annuity purchase is figured in net worth isn’t binary. It’s a spectrum shaped by accounting rules, tax codes, and personal financial goals. Below are seven critical factors that determine how—and if—annuities appear on a net worth statement.1. Deferred Annuities Are Often Omitted—But Shouldn’t Always Be
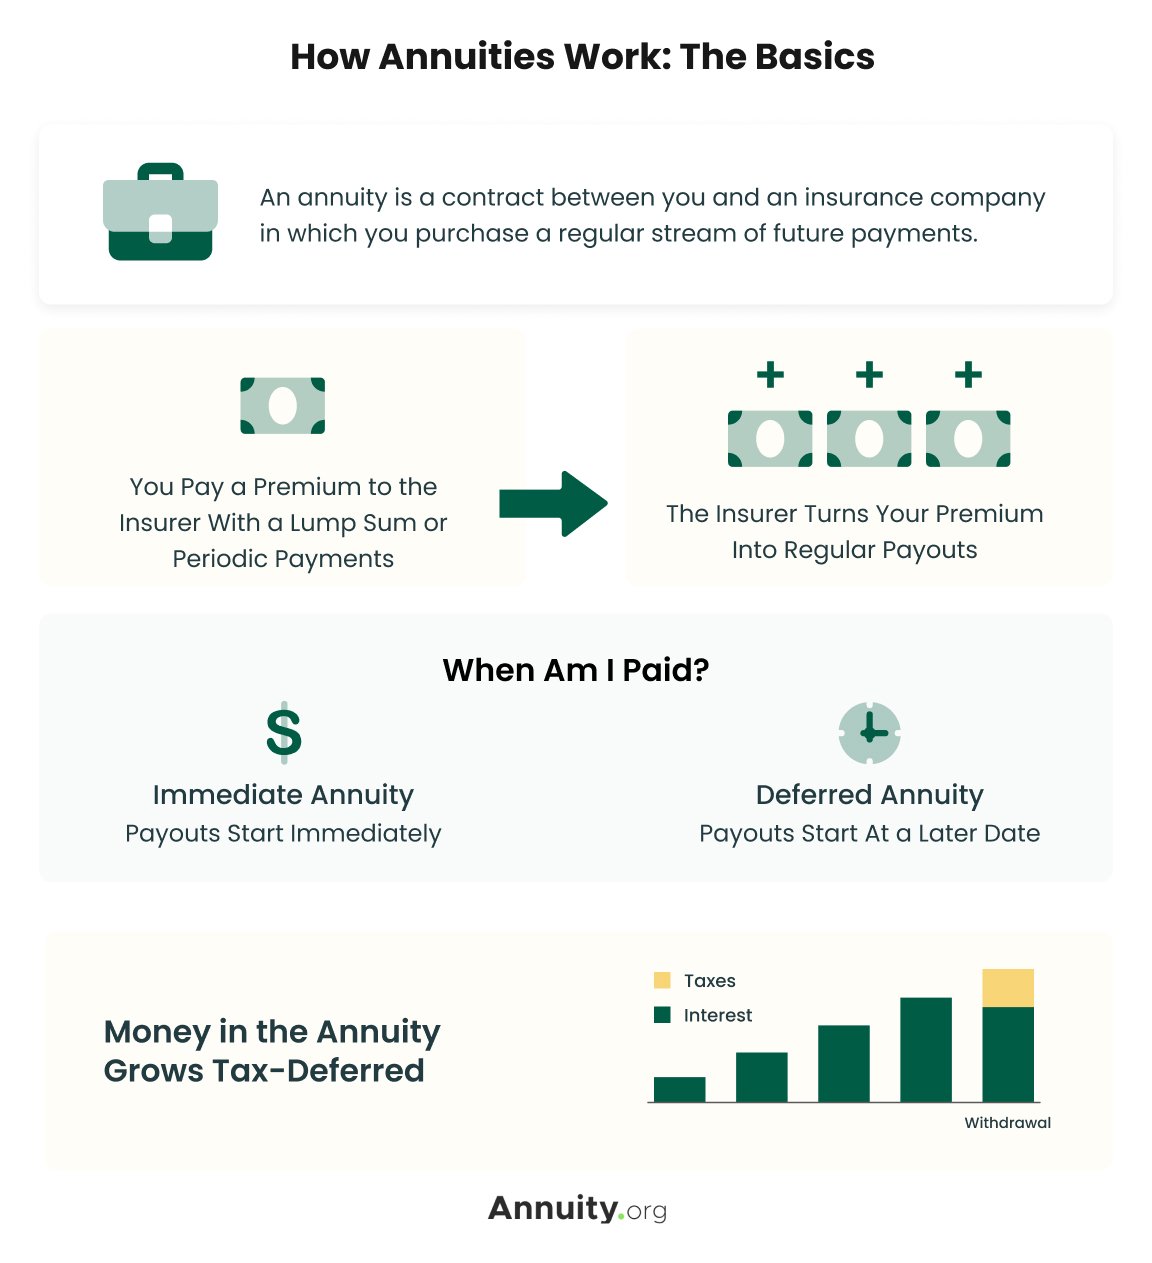
Deferred annuities, where growth compounds tax-free until withdrawal, pose a unique challenge. Traditional net worth calculations exclude them entirely because their value isn’t immediately accessible. Yet, this approach ignores their future purchasing power. For example, a $500,000 deferred income annuity might yield $30,000 annually for life—an asset worth far more than its current cash value. Financial planners increasingly argue that projected income streams (not just cash surrender value) should factor into net worth, especially for retirees. The catch? No standardized method exists. Some advisors use present-value calculations; others treat deferred annuities as "illiquid assets" and exclude them unless the policyholder plans to annuitize within five years. The IRS, meanwhile, treats deferred annuities as modified endowment contracts (MECs) if funded improperly, complicating matters further. The result? A gap between what’s reported and what’s strategically valuable.2. Immediate Annuities Are Rarely Included—Unless You’re an Actuary
Immediate annuities—where a lump sum buys a guaranteed payout—are the most straightforward to exclude. Once purchased, the premium disappears from the balance sheet, replaced by a stream of payments. Yet, this treatment masks the economic value of the annuity. A $1 million immediate annuity might provide $60,000 yearly for life, equivalent to a 6% yield. Excluding it entirely understates the retiree’s true financial security. Here’s the irony: banks and lenders often ignore annuity income when assessing creditworthiness, treating it as non-discretionary cash flow. This creates a paradox—an asset that generates reliable income is invisible to both wealth assessments and underwriting models. Some financial planners now advocate for a hybrid approach: listing the annuity’s remaining present value (based on actuarial tables) as a non-liquid asset, with a footnote clarifying its income-generating potential.3. Tax-Deferred Growth Means Hidden Value
The tax advantages of annuities—deferred growth, tax-free loans, and step-up in basis at death—make them a wealth-preservation tool. Yet, these benefits vanish if the annuity isn’t accounted for in net worth. For instance, a $1 million annuity with $200,000 in accumulated gains might appear as $1 million on paper, but the realizable value could be far lower due to surrender charges or tax liabilities upon withdrawal. The solution? Some ultra-high-net-worth families use private placement annuities (PPAs), which offer customizable terms and potential for higher returns. These are often excluded from public net worth disclosures but play a pivotal role in estate planning. The key takeaway: tax-deferred assets distort net worth calculations, and ignoring them risks misjudging liquidity and risk tolerance.4. Surrender Charges Create a "Dark Matter" Problem
Annuities with surrender periods (typically 5–15 years) introduce a temporal distortion in net worth. During the early years, the contract’s cash value may be artificially low due to fees, making it appear as though the asset has shrunk. This is particularly problematic for high-net-worth individuals who might need to access funds unexpectedly. For example, a $1 million annuity could show a $600,000 cash value in Year 3 due to surrender charges—even though the underlying investments have grown. Financial advisors often recommend front-loading annuity purchases to minimize the impact of surrender periods on net worth. Alternatively, some clients hold annuities in separate legal entities (like trusts) to isolate their value from broader wealth assessments. The lesson? Surrender charges aren’t just a cost—they’re an accounting quirk that can skew perceived net worth.5. Annuities in Trusts Are a Gray Zone
Placing an annuity in an irrevocable trust alters how it’s treated in net worth calculations. The trust itself may be an asset, but the annuity’s cash value is often excluded from the grantor’s net worth—even though the payouts remain part of the estate. This strategy is common among families aiming to reduce estate taxes, but it creates confusion. The annuity’s value still exists; it’s just off-balance-sheet. Some estate planners argue that annuities in trusts should be disclosed separately, with a note on their projected income. Others treat them as "non-probate assets" and omit them entirely. The IRS has yet to provide clear guidance, leaving room for interpretation. The bottom line? Trust-based annuities complicate net worth reporting, and transparency depends on the advisor’s risk tolerance.6. Indexed Annuities Defy Simple Valuation
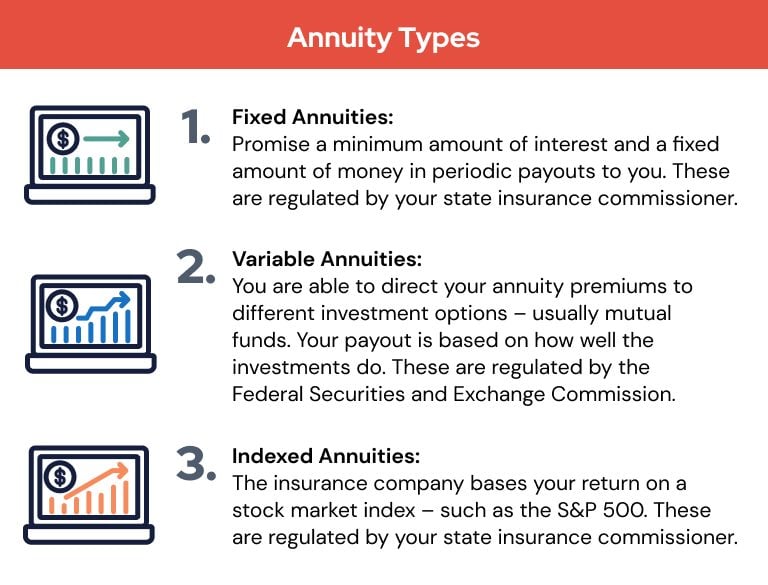
Indexed annuities, which offer upside potential tied to market performance, are among the hardest to value. Their cash value fluctuates based on participation rates, caps, and reset periods—none of which align with traditional asset valuation methods. As a result, many financial statements undervalue or overvalue indexed annuities, leading to misaligned financial planning. Consider a $500,000 indexed annuity with a 70% participation rate. If the S&P 500 rises 10%, the annuity’s value might grow by only 7%. Yet, the perceived risk-reward tradeoff makes it attractive to conservative investors. The challenge? Net worth calculations can’t capture this nuance without assuming a hypothetical growth scenario. Some advisors now use Monte Carlo simulations to estimate indexed annuity values, but this adds complexity—and potential for error—to wealth assessments.7. The "Invisible Income" Dilemma
Perhaps the biggest oversight is the income generated by annuities. A retiree with a $1 million annuity might receive $70,000 annually, but if the contract isn’t listed in net worth, that income appears as if it’s coming from nowhere. This creates a liquidity illusion: the retiree may overestimate their ability to handle market downturns or unexpected expenses."Annuities are the financial equivalent of a black box—you know the inputs, but the outputs are unpredictable until you open it. The real question isn’t whether to include them in net worth, but how to account for their income-generating capacity without overstating liquidity." — David M. Blanchett, Ph.D., Head of Retirement Research at MorningstarThe fix? Some planners now use cash flow analysis alongside net worth statements, treating annuity payouts as a separate line item. Others advocate for dynamic net worth tracking, where annuity values are recalculated annually based on market conditions and payout schedules.
How These Facts Connect
The seven factors above reveal a fundamental truth: an annuity purchase is figured in net worth only if you define what "net worth" means. Traditionalists exclude annuities entirely, viewing them as liabilities or non-liquid assets. Progressive planners, however, argue that ignoring annuities distorts financial reality, especially for retirees who rely on them for income. The disconnect stems from accounting conventions that prioritize liquidity over sustainability. The table below compares key considerations when deciding whether to include annuities in net worth:| Factor | Traditional Approach | Progressive Approach | Tax/Estate Impact |
|---|---|---|---|
| Deferred Annuities | Excluded (cash value only) | Included as projected income stream | Potential MEC penalties if misfunded |
| Immediate Annuities | Excluded post-purchase | Listed as present value of payouts | No immediate tax impact, but income taxable |
| Surrender Charges | Reduces reported cash value | Noted as "non-liquid asset" with timeline | No direct tax effect, but affects liquidity |
| Indexed Annuities | Valued at cash surrender | Estimated via market-linked projections | Tax-deferred growth, but complex reporting |
| Annuities in Trusts | Often excluded from grantor’s net worth | Disclosed separately with income projections | Reduces estate tax liability |
Conclusion
The question is an annuity purchase figured in net worth has no universal answer. It’s a negotiation between accounting rigor and financial pragmatism. For pre-retirees, excluding annuities might simplify planning; for retirees, it risks obscuring a critical income source. The solution lies in customized reporting—tailoring net worth statements to reflect how annuities function in a client’s broader strategy. What’s clear is that annuities can no longer be treated as an afterthought. As life expectancies rise and traditional pensions fade, their role in wealth preservation grows. The next frontier? Integrating annuities into dynamic net worth models that account for both cash value and income potential. Until then, the debate will persist—because in finance, as in life, the devil is in the details.Comprehensive FAQs
Q: Does including an annuity in net worth affect my tax liability?
A: Not directly, but how you report it can. If you overstate the cash value, the IRS may question unrealized gains. Conversely, excluding deferred growth could trigger higher taxes when withdrawals occur. The key is consistency—stick to either cash surrender value or a conservative estimate (e.g., 80% of premium for deferred annuities).
Q: Can I adjust my net worth statement to include annuity income separately?
A: Yes, but it requires customization. Some advisors create a "liquid net worth" (excluding annuities) and "total net worth" (including projected income). This dual approach is common among retirees who need to assess both spending power and asset liquidity.
Q: What happens if I annuitize the contract—does it disappear from net worth?
A: Technically, yes. Once you convert an annuity to a payout stream, the principal is gone, replaced by future payments. However, you should document the annuitization decision in your financial records, as it affects estate planning and potential creditor claims.
Q: Are indexed annuities harder to include in net worth than fixed annuities?
A: Absolutely. Fixed annuities have predictable values, while indexed annuities depend on market performance. Some planners use worst-case scenario valuations (e.g., assuming 0% growth) to avoid overstating net worth, while others average past participation rates for a more realistic estimate.
Q: Does my lender care if I have an annuity in my net worth calculation?
A: Most lenders ignore annuity income when assessing debt capacity, treating it as non-discretionary cash flow. However, some high-net-worth lenders (e.g., private banks) may consider annuity-backed loans, where the contract itself serves as collateral. Always disclose annuities if applying for credit—omitting them could void the loan.
Q: Can I exclude an annuity from net worth if it’s in a trust?
A: Yes, but with caveats. If the trust is irrevocable, the annuity’s value is typically removed from your personal net worth. However, the payouts remain part of your taxable income, and the trust’s assets may still be subject to estate taxes if structured improperly. Consult an estate attorney to ensure compliance.
Q: What’s the best way to track annuity values over time?
A: Use a dedicated annuity tracking tool (e.g., Vanguard’s annuity calculators or Morningstar’s retirement tools) to monitor cash value, surrender charges, and projected payouts. Some wealth management platforms now offer annuity-specific dashboards that integrate with net worth statements. Update these annually or after major market shifts.
Q: Do annuities affect my Social Security benefits?
A: Indirectly. While annuities themselves don’t reduce Social Security, the income they generate may trigger the Social Security tax torement (taxes on benefits for high earners). If your combined income (including annuity payouts) exceeds $44,000 (single filer) or $88,000 (married), up to 85% of benefits become taxable. Plan accordingly by coordinating annuity withdrawals with Social Security timing.
