The first time the question surfaced in a boardroom was in 2018, when a Silicon Valley executive—let’s call him Daniel—leaned back in his chair and muttered it under his breath. He’d just sold a minority stake in his startup for $3 million, bringing his net worth to $7 million. Around the table, the private equity partners nodded politely but didn’t cheer. One sipped his coffee in silence, then said,
"That’s the new middle class." Daniel’s jaw tightened. He’d spent years building something he thought would set him free.
Freedom, of course, is relative. In Monaco, $7 million might buy you a penthouse with a view of the Mediterranean and a yacht slip at Port Hercule. In Mumbai, it could fund a dynasty for three generations. But in San Francisco, where Daniel lived, that same figure meant his monthly property taxes alone exceeded what most of his peers earned in a year. The real estate agent who’d helped him buy his home in Pacific Heights had warned him:
"You’re not rich yet. You’re just expensive." The words stuck.
Wealth isn’t a static line on a spreadsheet. It’s a moving target, shaped by geography, inflation, and the invisible ledger of opportunity costs. A $7 million net worth in 2005 would buy you a different kind of life than it does today. The same sum in Dubai might let you live like a sultan, while in Zurich, it could leave you scrambling to keep up with the taxman. The question—
is 7 million net worth considered wealthy?—isn’t just about numbers. It’s about what those numbers can
actually unlock, and what they can’t.
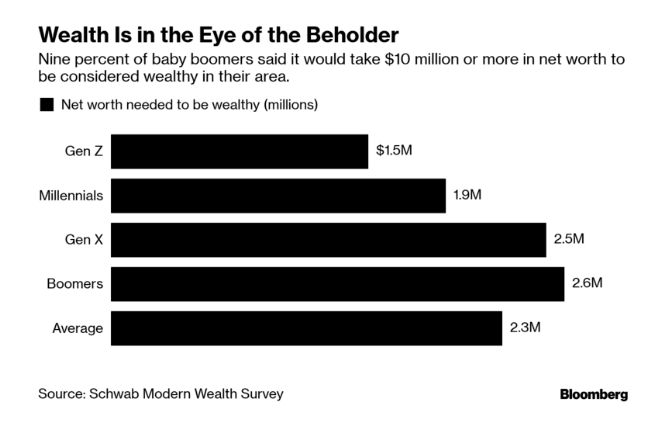
Daniel eventually sold his remaining shares for another $5 million. By then, he’d realized the truth: wealth at that level isn’t about what you have, but what you
haven’t had to sacrifice. The late nights. The deferred gratification. The quiet terror of wondering if one bad market could erase it all. That’s when he started asking the right questions—not about how much he had, but about how much he’d
earn from it.
Where It All Began
The modern obsession with net worth benchmarks traces back to the 1980s, when financial planners began codifying "wealth thresholds" as a way to sell services to the newly affluent. Before then, wealth was measured in land, titles, or social standing. The shift to cold, liquid numbers was part of a broader cultural transformation: the rise of the knowledge economy, where paper assets (stocks, bonds, intellectual property) replaced physical ones (farms, factories, gold).
The first widely cited net worth milestones appeared in studies by economists like Thomas Piketty, who argued that wealth inequality was structural, not accidental. A $7 million net worth, in his framework, placed someone firmly in the top 1% globally—but that’s a global average. In the U.S., it’s closer to the top 3%. The problem? Those percentages don’t account for
where you live. A $7 million portfolio in rural Idaho might feel like a king’s ransom; in Manhattan, it’s just enough to avoid the "struggling professional" label but not to escape the city’s gravitational pull.
The early signs of this disconnect emerged in the late 1990s, when the dot-com boom created a class of "paper millionaires" overnight. Many of them discovered too late that liquidity ≠ wealth. A $7 million net worth on paper meant nothing if it was tied up in unprofitable ventures. The crash of 2000 exposed the flaw in the narrative: wealth isn’t just about the number on a balance sheet. It’s about
control—over cash flow, over time, over legacy.
The Early Signs
By the mid-2000s, financial advisors had begun segmenting wealth into tiers, with $7 million often cited as the lower bound of "significant wealth." But the signs that this was an arbitrary cutoff were everywhere. In 2006, a study by Spectrem Group found that households with $5 million to $25 million in investable assets—Daniel’s bracket—spent nearly twice as much on financial planning as those with less. Why? Because at that level, the cost of
not optimizing becomes visible.
Consider the tax tail. In the U.S., a $7 million net worth might mean federal estate taxes kick in, depending on your state. In California, where Daniel lived, the state’s additional tax burden could eat 13% of his estate. Suddenly, that $7 million isn’t just money—it’s a liability waiting to happen. The early adopters of wealth management tools (like dynasty trusts or private family offices) were the ones who realized that
is 7 million net worth considered wealthy was the wrong question. The real question was:
How do you protect it?
The other early sign was lifestyle inflation. A $7 million net worth doesn’t guarantee comfort—it guarantees
expectations. The private jet charter that seemed like a splurge at $500,000 suddenly felt like a necessity when your neighbors were flying Gulfstreams. The same logic applied to education: sending kids to elite schools, hiring top-tier tutors, or even just the social pressure to "keep up" with peers who’d hit $10 million first. Wealth at this level becomes a performance art.
The Turning Point
The financial crisis of 2008 was the moment when the illusion of $7 million as "safe wealth" shattered. Overnight, portfolios that had seemed bulletproof—heavy in private equity or real estate—evaporated. A hedge fund manager in New York who’d bragged about his $8 million net worth in 2007 found himself scrambling to cover margin calls by 2009. The lesson?
Is 7 million net worth considered wealthy wasn’t just about the number; it was about
diversification,
liquidity, and
psychological resilience.
That’s when the ultra-high-net-worth (UHNW) crowd—those with $30 million and above—began to distance themselves. They’d weathered the storm because they’d hedged across asset classes, geography, and even currencies. The $7 million set? Many of them were left holding illiquid assets or facing forced sales. The turning point wasn’t just financial; it was cultural. Wealth below $30 million became "aspirational," while $7 million was recategorized as "vulnerable."
>
"You’re not rich until your money starts working for someone else’s problems." —
A former Goldman Sachs partner, reflecting on clients who lost fortunes in 2008.
The Build-Up, Year by Year
|
Period | What Happened / What Changed |
|------------------|--------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------|
| 2010–2014 | The rise of passive income strategies (REITs, dividend stocks) became critical for the $7M net worth crowd. Those who didn’t diversify beyond traditional investments saw their portfolios stagnate as the S&P 500 recovered. |
| 2015–2017 | The gig economy and side hustles emerged as new wealth-building tools, but the $7M set increasingly outsourced active income generation to managers. The focus shifted to
preservation over accumulation. |
| 2018–2020 | Cryptocurrency and private equity became speculative plays for some, while others doubled down on tangible assets (art, wine, rare collectibles). The pandemic exposed which $7M portfolios were truly liquid. |
| 2021–2023 | Inflation and rising interest rates turned fixed-income assets into liabilities. The $7M net worth threshold became a moving target, with many realizing they needed $10M+ to maintain their lifestyle in a high-cost city. |
Lessons From the Journey

-
Wealth at $7 million is a high-wire act. One bad bet (a failed startup, a divorce, a market crash) can reset your trajectory. The buffer isn’t just financial—it’s emotional.
- Geography is the silent killer. A $7 million net worth in Austin might fund three generations, but in New York, it’s just enough to avoid being "poor" while still feeling the pressure to "keep up."
- Taxes are the unseen partner. At this level, you’re no longer just a taxpayer—you’re a
target. Estate planning isn’t optional; it’s survival.
- Legacy isn’t automatic. Many with $7 million discover too late that wealth without a plan is just a temporary high. The question shifts from
"Is 7 million net worth considered wealthy?" to
"What will it buy my children?"
Where Things Stand Today
As of 2024, the $7 million net worth benchmark has been pushed higher by inflation, rising real estate costs, and the erosion of purchasing power. In the U.S., the median net worth for the top 1% now hovers around $10 million, meaning $7 million is no longer a threshold—it’s a
stepping stone. The real divide is between those who can generate passive income from their wealth and those who must still work to maintain it.
The shift is also generational. Millennials with $7 million net worths—if they exist—are far more likely to be entrepreneurs or tech founders than legacy inheritors. Their wealth is tied to illiquid assets (startup equity, crypto, real estate), which means volatility is baked into the equation. The old rules don’t apply. Is 7 million net worth considered wealthy? Today, the answer depends on whether you can turn it into
generational wealth—or if it’s just a pit stop on the way to $30 million.
Conclusion
The $7 million net worth question is a Rorschach test. To some, it’s a ticket to freedom; to others, it’s a gilded cage. The truth? It’s neither. It’s a number that forces you to confront the real question:
What does wealth mean to you? Is it the ability to say no? The freedom to fail? Or is it the quiet terror of realizing that no matter how much you have, there’s always someone with more?
Daniel sold his remaining shares and moved to Portugal. He kept his $12 million net worth but traded Manhattan’s rat race for a villa in the Algarve. When asked if he was wealthy, he’d shrug and say,
"Enough to be comfortable. Not enough to be careless." That’s the unspoken rule of the $7 million club: the moment you start acting like you’ve "arrived," the market reminds you that wealth is a verb, not a noun.
Comprehensive FAQs
#### Q: Is $7 million enough to retire comfortably?
A: It depends entirely on where you live and how you spend. In a low-cost area (e.g., rural U.S., Southeast Asia), $7 million could fund a $100,000/year lifestyle for decades via the 4% rule. In a high-cost city (e.g., NYC, Zurich), you’d need to withdraw less than 3% annually to avoid running out of money. Most financial planners recommend aiming for $10 million+ for true retirement flexibility, especially with healthcare costs and inflation.
#### Q: Can you live off $7 million without working?
A: Technically yes, but the word "live" is key. If you’re in the U.S., Social Security and Medicare will still require some income. A $7 million portfolio generating $280,000/year (4% withdrawal) might cover taxes and living expenses, but unexpected costs (e.g., a $200,000 medical bill) could force you back into the workforce. The real question is:
Do you want to live off it, or do you want it to grow?
#### Q: Is $7 million considered wealthy in other countries?
A: Globally, $7 million is solidly upper-middle-class to lower-tier ultra-high-net-worth in most developed nations. In Switzerland or Singapore, it’s enough to live like royalty but not to enter the "billionaire-adjacent" social circles. In Brazil or India, $7 million could fund a dynasty for generations. The key difference? In wealthier nations, $7 million is visible wealth—you’ll be noticed, targeted by advisors, and expected to "act the part." In emerging markets, it’s often invisible until you start spending.
#### Q: What’s the biggest mistake people with $7 million make?
A: Overconfidence. They assume their wealth is insulated from market downturns, taxes, or bad decisions. The most common pitfalls:
- Concentration risk (e.g., too much in one stock, real estate, or a single business).
- Lifestyle inflation (buying a $5M yacht that costs $500K/year to maintain).
- Ignoring estate taxes (assuming "it’ll be fine" until it’s not).
- Chasing returns (e.g., crypto, meme stocks) instead of preserving capital.
#### Q: How does $7 million compare to the average millionaire?
A: The average millionaire (U.S. data) has a net worth of $2.2 million, with most of it tied up in home equity. A $7 million net worth puts you in the top 0.5% globally but only the top 3–5% in the U.S.. The key difference? Liquidity. The average millionaire’s wealth is often illiquid (real estate, retirement accounts), while $7 million typically includes investable assets—meaning you can deploy it for opportunities (or losses) faster.
#### Q: Can $7 million be lost in a bad market?
A: Absolutely. A 30% market crash (not uncommon) on a $7 million portfolio means $2.1 million wiped out overnight. If you’re heavily invested in stocks, real estate, or private equity, a downturn could reset your net worth to $5 million—or less. The only way to "protect" $7 million is through diversification (cash, bonds, tangible assets) and hedging (options, gold, offshore accounts). Even then, no strategy is foolproof.
#### Q: Is $7 million enough to leave a legacy?
A: Only if you plan for it. A $7 million estate, after taxes and legal fees, might leave $4–5 million to heirs. If your goal is to fund a grandchild’s education or preserve wealth for future generations, you’ll need dynasty trusts, philanthropic giving strategies, or business ownership to stretch it further. Without planning, $7 million can disappear in one generation—through poor investments, family disputes, or inflation.
#### Q: What’s the social perception of $7 million?
A: It’s the "almost there" net worth. You’re wealthy enough to afford luxury (private schools, vacations, art) but not elite enough to move in the same circles as $50M+ earners. In business networks, you’ll be respected but not feared. At charity galas, you’ll be a donor—but not the
lead donor. The unspoken rule? $7 million gets you a seat at the table, but $30 million gets you the mic.

