
Breaking Down the Numbers
The financial implications of irrevocable trusts extend beyond the balance sheet. When assets are transferred into such a trust, they are removed from the grantor’s control, but their impact on net worth depends on the context in which that net worth is being measured. For instance, a personal financial statement prepared for a bank loan will likely exclude trust assets entirely, as the grantor no longer has access to them. However, the IRS’s definition of net worth for estate tax purposes is far broader, potentially including assets in irrevocable trusts if the grantor retained certain rights or benefits. This duality creates a scenario where the same assets might be treated differently depending on who’s asking the question. A lender reviewing a loan application will focus on liquidity and immediate access to funds, while a tax auditor will scrutinize whether the trust was established to avoid taxes—an action that could trigger inclusion of the assets in the grantor’s estate. The disconnect arises because irrevocable trusts are not a one-size-fits-all solution; their treatment varies based on the trust’s terms, the grantor’s intentions, and the jurisdiction’s laws.The Verified Baseline
Publicly available data confirms that irrevocable trusts are not automatically included in a grantor’s net worth for most personal financial calculations. Courts and financial institutions generally recognize that once assets are irrevocably transferred, they are no longer part of the grantor’s estate or personal wealth. For example, in divorce proceedings, assets held in a properly structured irrevocable trust are typically excluded from the marital estate, as they are no longer under the grantor’s control. Similarly, lenders reviewing personal net worth statements will not count trust assets unless the grantor has a legally enforceable right to reclaim them. However, there are exceptions. If the trust includes a reversionary interest—meaning the grantor or their estate could regain control under certain conditions—the IRS may treat the assets as still part of the grantor’s net worth for estate tax purposes. Additionally, some states have specific laws that treat irrevocable trusts differently, particularly in community property states where spouses may have claims on assets transferred into trusts. These nuances mean that while the general rule is exclusion, the specifics can vary widely.What the Estimates Suggest
Industry estimates suggest that around 30% of high-net-worth individuals use irrevocable trusts as part of their estate planning, but fewer than 10% fully understand the implications for net worth reporting. Financial advisors often cite cases where clients underreport assets in trusts, leading to discrepancies in loan applications or tax filings. For instance, a grantor who transfers a multimillion-dollar property into an irrevocable trust might see their reported net worth drop significantly—but if the trust includes a "powers of appointment" clause allowing the grantor to influence distributions, the IRS could argue the assets should still be included in the estate tax calculation. The variability in treatment also affects financial planning. A study by the American Academy of Financial Management found that individuals who transferred assets into irrevocable trusts without consulting tax professionals were twice as likely to face audits or disputes over asset valuation. The lesson is clear: the exclusion of trust assets from net worth is not absolute, and the specifics depend on the trust’s design and the legal context in which it’s applied.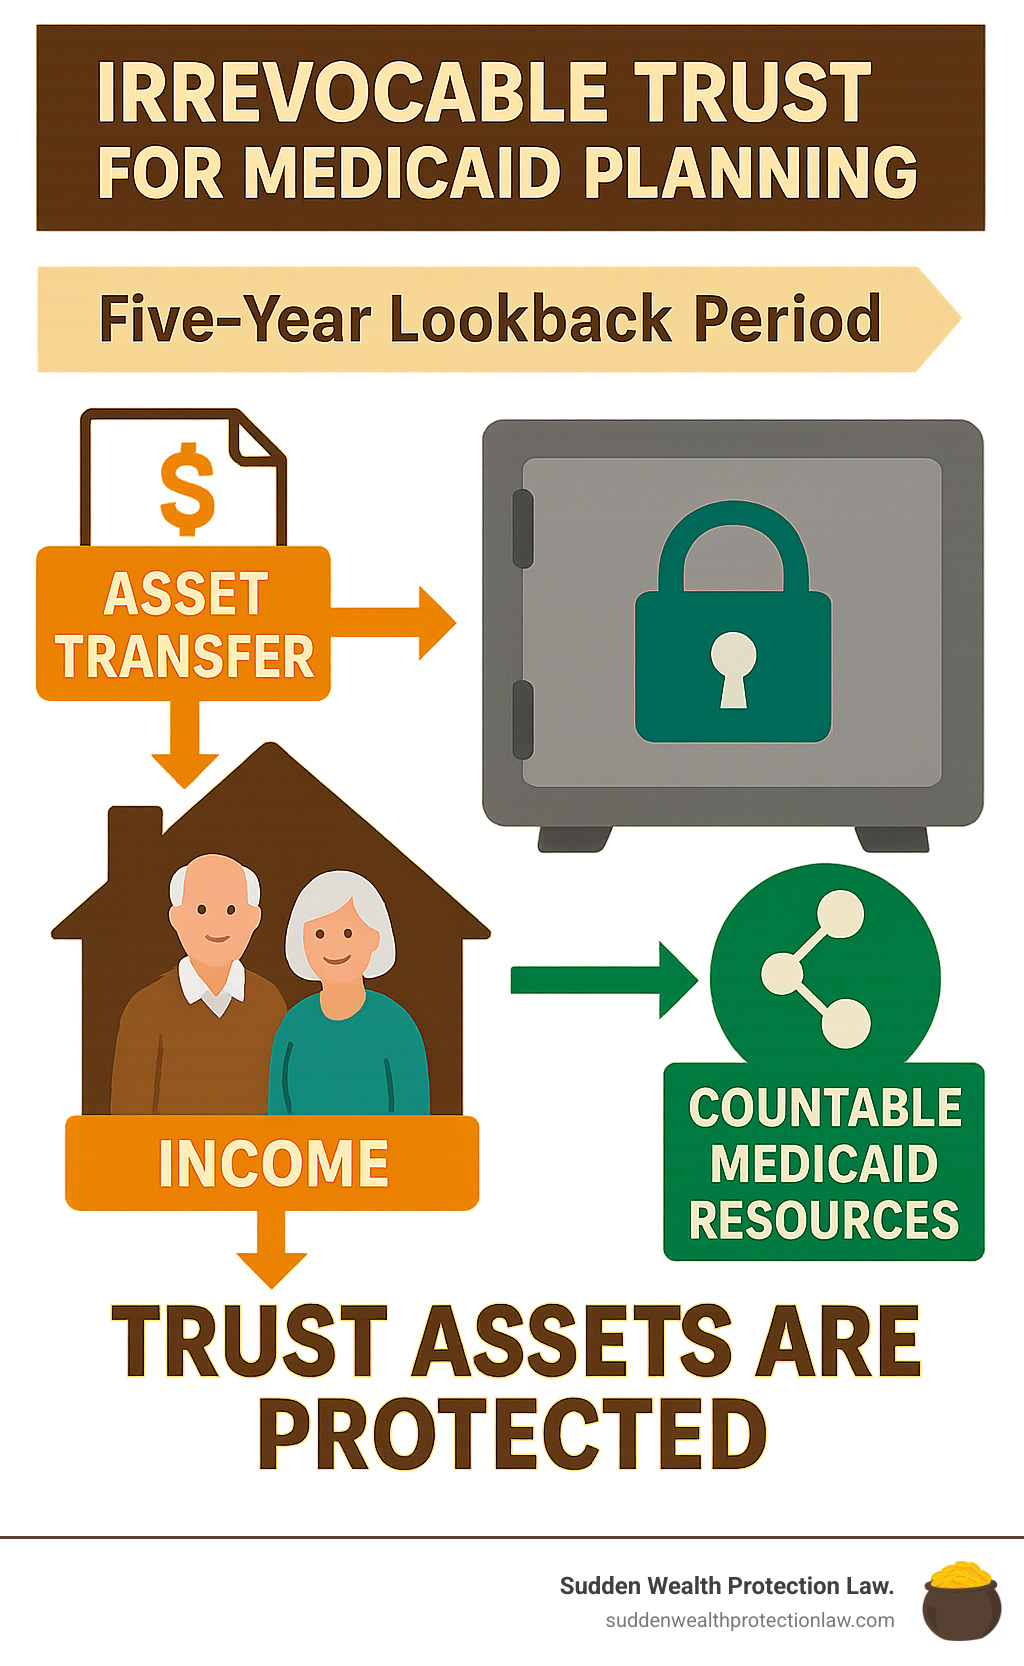
Case Study: A Closer Look
Consider the case of a tech executive who transferred a portfolio of private equity holdings—estimated at figures around the £50 million range—into an irrevocable trust to protect the assets from potential lawsuits. On paper, the transfer removed the assets from the executive’s personal net worth, reducing their reported wealth for lending purposes. However, the trust included a spendthrift clause allowing the executive to receive distributions at their discretion, which the IRS later argued constituted retained control. The dispute reached a settlement where the IRS agreed to exclude the assets from the executive’s estate tax calculation—but only after a lengthy audit and the grantor’s legal team proving that the distributions were not guaranteed. This case highlights how even irrevocable trusts can blur the lines of net worth inclusion if the grantor retains any level of influence over the assets."The key takeaway is that irrevocable trusts are not a magic bullet. If you’re transferring assets to reduce net worth, you must ensure the trust is truly irrevocable—and that no strings are attached that could bring those assets back into your taxable estate." — Estate Planning Attorney, London High Court Proceedings (2022)
| Factor | Estimated Impact on Net Worth Inclusion |
|---|---|
| Grantor Retains Powers of Appointment | Assets likely included in estate tax calculations (IRS position) |
| Trust Includes Spendthrift Clause | May still be considered part of net worth if distributions are discretionary |
| State-Specific Trust Laws (e.g., Community Property) | Spouse may have claim; assets could be partially included in net worth |
| Reversionary Interest Exists | High likelihood of IRS inclusion in estate tax calculations |
| Properly Structured Irrevocable Trust (No Control Retained) | Assets excluded from net worth for most purposes |
What This Means Going Forward
For individuals structuring irrevocable trusts, the primary consideration should be clarity—both in the trust’s legal language and in how it’s documented for financial reporting. If the goal is to reduce net worth for lending or personal financial statements, the trust must be airtight, with no provisions that could allow the grantor to regain control. Conversely, if the trust is part of a broader estate tax strategy, the grantor must be prepared for potential scrutiny from tax authorities. The rise of digital asset trusts has further complicated the issue. Cryptocurrency and NFT holdings transferred into irrevocable trusts may face additional challenges, as courts and regulators are still grappling with how to classify these assets in trust structures. The lack of precedent means that grantors must proceed with even greater caution, ensuring that their trusts comply with both traditional and emerging financial regulations.
Conclusion
The question of whether assets in an irrevocable trust remain part of a grantor’s net worth does not have a single answer. It depends on the trust’s structure, the legal jurisdiction, and the context in which net worth is being assessed. For personal financial statements and lending purposes, the general rule is exclusion—but tax and estate planning considerations introduce layers of complexity. The safest approach is to consult with both a tax professional and an estate attorney to ensure the trust aligns with the grantor’s financial goals without inviting unnecessary scrutiny. Ultimately, irrevocable trusts are powerful tools for asset protection and tax efficiency, but their effectiveness hinges on meticulous planning. Grantors must weigh the benefits of exclusion against the risks of misclassification, ensuring that their trusts serve their intended purpose without creating unintended financial or legal exposure.Comprehensive FAQs
Q: Do assets in an irrevocable trust count toward my net worth for personal financial statements?
A: Generally, no—if the trust is properly structured and you have no control over the assets, they should not appear on personal net worth statements. However, if the trust includes provisions allowing you to influence distributions or regain control, lenders or financial institutions may still consider them part of your wealth.
Q: Can the IRS include assets in an irrevocable trust in my estate tax calculation?
A: Yes, if the trust includes a reversionary interest, powers of appointment, or other clauses that allow you or your estate to benefit indirectly, the IRS may treat the assets as part of your taxable estate. This is why consulting a tax attorney is critical before transferring assets into an irrevocable trust.
Q: Will transferring assets into an irrevocable trust reduce my net worth for divorce proceedings?
A: It depends on the jurisdiction. In most cases, assets in a properly funded irrevocable trust are excluded from the marital estate. However, if the trust was established to hide assets or if your spouse can prove you retained control, a court may still consider them part of the divisible property.
Q: Are there any exceptions where assets in an irrevocable trust should be included in net worth?
A: Yes. If the trust was created fraudulently (e.g., to avoid creditors or spousal claims), or if it includes clauses that allow the grantor to benefit indirectly, courts or tax authorities may override the exclusion. Always ensure the trust complies with legal standards.
Q: How do digital assets (crypto, NFTs) in irrevocable trusts affect net worth reporting?
A: The treatment is still evolving, but the same principles apply: if you have no control over the assets, they likely won’t count toward net worth. However, because digital assets are relatively new, regulators may scrutinize these trusts more closely, increasing the risk of misclassification.
Q: What’s the biggest mistake people make when using irrevocable trusts to reduce net worth?
A: Assuming the trust is "fire-and-forget." Many grantors transfer assets without reviewing the trust’s terms or consulting professionals, only to discover later that they’ve retained rights that could bring the assets back into their taxable estate. Always review the trust document thoroughly and seek expert advice.
