The first time Indorama Ventures appeared on global radar, it was a small Thai trading firm with a single-minded focus: textiles. Founded in 1972 by
Sukree Sukplang, the company’s early years were unremarkable by today’s standards—just another player in a crowded industry. But beneath the surface, a quiet ambition was taking shape. By the 1990s, as Southeast Asia’s economies roared to life, Indorama’s leadership had spotted an opportunity: the region’s insatiable demand for synthetic fibers wasn’t just growing—it was accelerating. The company’s pivot from trading to manufacturing wasn’t just strategic; it was a bet on the future. And as the petrochemical industry boomed, so did Indorama’s valuation, turning a once-obscure name into a household term in boardrooms from Bangkok to Brussels.
Fast forward to the 2010s, and Indorama Ventures had become a force of nature. Its net worth, once a modest figure, now hovered in the
$15 billion range—a number that barely scratches the surface of its true influence. The company’s acquisitions, from Indonesia’s largest polyester plant to stakes in Europe’s chemical giants, weren’t just financial moves; they were chess plays in a high-stakes game. Analysts now watch Indorama’s balance sheet as closely as they watch oil prices, because its every move ripples through global supply chains. The question isn’t whether Indorama Ventures will remain a dominant player—it’s how far its net worth will climb, and what that means for an industry still reeling from its rise.
Where It All Began
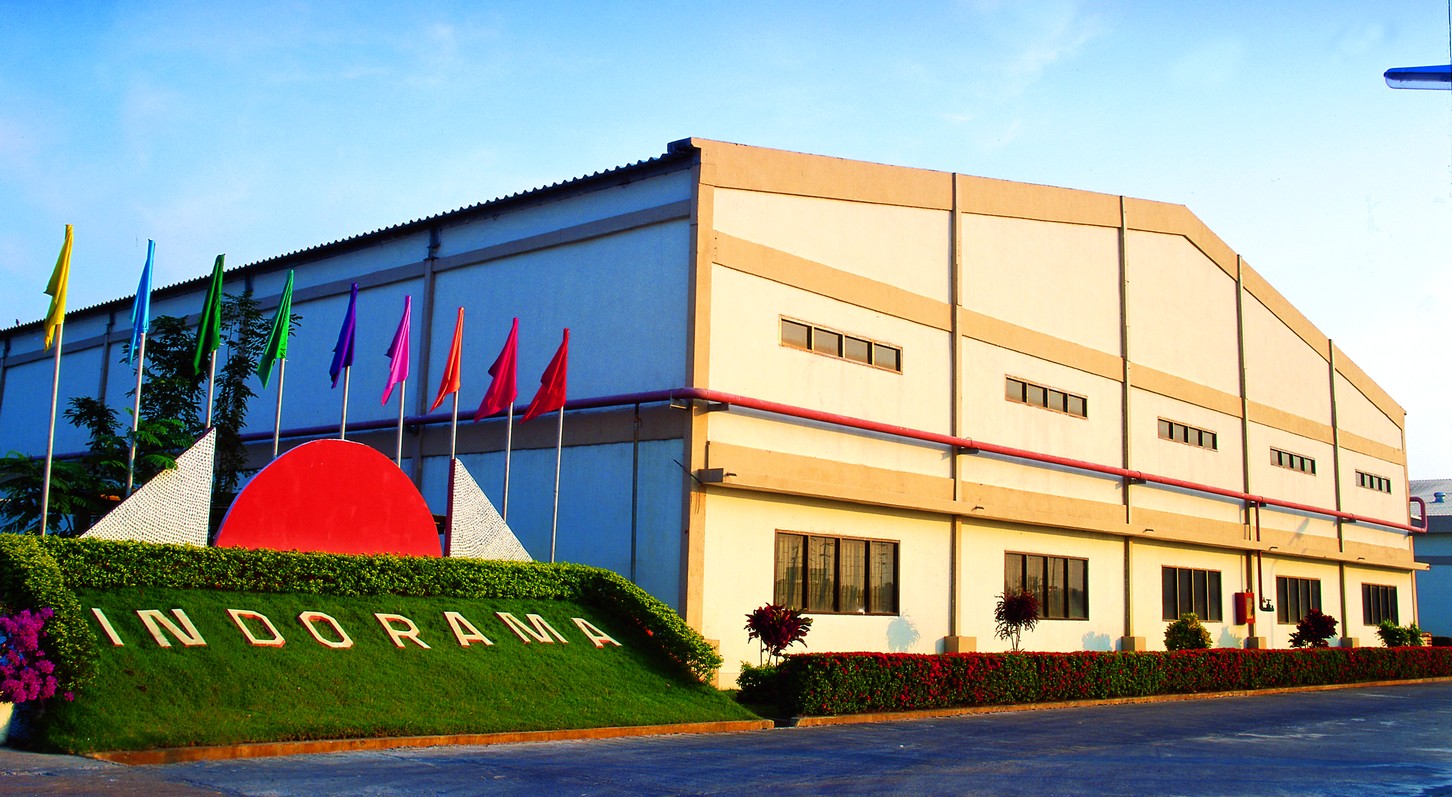
Indorama’s story starts in the humid streets of Bangkok, where Sukree Sukplang launched the company with a single office and a handful of employees. The 1970s were a different era: Thailand’s economy was agrarian, and textiles were a labor-intensive, low-margin business. But Indorama’s early success wasn’t about cutting costs—it was about
understanding the unspoken rules of the trade. While competitors focused on volume, Sukplang built relationships with textile mills in Japan and Europe, positioning Indorama as a bridge between raw material suppliers and Asian manufacturers. By the late 1980s, the company had expanded into polyester production, a shift that would define its trajectory.
The real turning point came when Indorama realized that
raw material control was the key to profitability. Instead of relying on spot markets, the company began vertically integrating—buying stakes in chemical plants, securing feedstock contracts, and even investing in ethylene crackers. This wasn’t just diversification; it was a moat. When global polyester prices spiked in the early 2000s, Indorama wasn’t at the mercy of fluctuations. It was shaping them. The company’s net worth, once tied to textile margins, now reflected something far more valuable: strategic dominance in a cyclical industry.
The Turning Point
The late 2000s marked the moment Indorama Ventures stopped being a regional player and became a global contender. The financial crisis of 2008-09 created a perfect storm: European chemical firms were desperate for cash, and Indorama had deep pockets. In 2010, it acquired
Indorama Ventures Europe, a portfolio that included assets in the UK, Belgium, and the Netherlands. The move wasn’t just about assets—it was about geopolitical leverage. By controlling European production, Indorama could bypass trade barriers, secure export markets, and hedge against currency risks. Overnight, its net worth ballooned, and its influence stretched from the Middle East to North America.
The acquisition spree didn’t stop there. In 2012, Indorama bought
Indorama Petrochemicals Indonesia, a deal that gave it control over one of the world’s largest polyester plants. The company’s net worth wasn’t just growing—it was redefining industry benchmarks. Analysts who once dismissed Indorama as a "textile trader" now took its financial reports seriously. The shift from a Thai family business to a multinational conglomerate wasn’t just organic growth; it was a calculated dismantling of traditional supply chain hierarchies.
>
"We didn’t just buy companies—we bought entire ecosystems. And once you control the ecosystem, the numbers take care of themselves." —
Indorama Ventures executive, 2015
The Build-Up, Year by Year
|
Period | Key Developments | Impact on Net Worth |
|-------------------|--------------------------------------------------------------------------------------|-----------------------------------------------------------------------------------------|
| 1990s | Shift from trading to polyester manufacturing; first vertical integration moves. | Early-stage asset accumulation; net worth crosses $100 million. |
| 2005-2010 | Expansion into Europe; acquisition of UK/Belgium chemical plants. | Net worth jumps to $2+ billion; European foothold secures long-term contracts. |
| 2012-2017 | Purchase of Indonesia’s largest polyester plant; Middle East feedstock investments. | $10+ billion valuation; supply chain dominance in Asia-Pacific. |
Lessons From the Journey
Indorama’s rise offers four critical takeaways for any company chasing scale:
- Feedstock is king. Controlling raw materials isn’t just cost-efficient—it’s a strategic weapon in volatile markets.
- Geographic diversification isn’t optional. Europe, Asia, and the Middle East aren’t just markets—they’re hedges against regional risks.
- Timing acquisitions during crises pays off. Indorama’s 2010 European buys were made possible by distressed asset pricing.
- Family ownership enables long-term bets. Unlike publicly traded firms, Indorama could afford decades-long plays without quarterly pressure.
Where Things Stand Today
As of 2024, Indorama Ventures’ net worth is estimated at over $15 billion, though exact figures remain closely guarded. The company’s portfolio now includes polyester plants in 12 countries, ethylene crackers in Saudi Arabia, and a stake in one of the world’s largest nylon producers. Its recent foray into battery-grade chemicals—a nod to the EV boom—suggests another phase of expansion. The question isn’t whether Indorama will remain profitable; it’s whether its net worth will surpass $20 billion within the next decade.
What sets Indorama apart isn’t just its financial scale but its operational agility. While competitors fret over carbon taxes or trade wars, Indorama adapts—diversifying into renewable energy-linked chemicals, lobbying for favorable regulations, and even exploring direct listings to raise capital without losing control. The company’s net worth is no longer just a number; it’s a barometer of the petrochemical industry’s future.
Conclusion
Indorama Ventures didn’t become a global powerhouse by accident. It did so by rewriting the rules of an industry that had long been dominated by Western multinationals. From its Bangkok origins to its European acquisitions, every move was calculated to increase leverage, reduce risk, and inflate its net worth. Today, as the world transitions to green chemistry, Indorama’s ability to pivot—without losing its core strengths—will determine whether it remains a titan or just another relic of the fossil fuel era.
One thing is certain: the company’s net worth isn’t just a reflection of its past. It’s a blueprint for how Asian conglomerates can challenge Western giants—not through brute force, but through strategic precision.
Comprehensive FAQs
#### Q: How did Indorama Ventures’ net worth grow so rapidly?
A: The company’s net worth surged through three key strategies: vertical integration (controlling feedstocks), timed acquisitions (buying European assets during the 2008 crisis), and geographic diversification (spreading risk across Asia, Europe, and the Middle East). Its polyester dominance—backed by Saudi ethylene deals—further locked in margins.
#### Q: Is Indorama Ventures publicly traded?
A: No. It remains privately held, with the Sukplang family controlling stakes. This allows for long-term investments without shareholder pressure, though rumors of a partial IPO have circulated in recent years.
#### Q: What’s the biggest risk to Indorama’s net worth?
A: Regulatory shifts (e.g., EU carbon border taxes) and competition from renewable-based chemicals pose the greatest threats. Indorama’s response—diversifying into battery materials—suggests it’s hedging against these risks.
#### Q: How does Indorama’s net worth compare to rivals like LyondellBasell or Formosa Plastics?
A: While exact figures are private, Indorama’s $15+ billion valuation places it below LyondellBasell ($50B+) but above many Asian peers. Its growth trajectory, however, is among the fastest in the sector.
#### Q: Has Indorama Ventures ever faced major financial setbacks?
A: Yes. The 2015-16 polyester glut (due to overcapacity in China) temporarily squeezed margins, but Indorama’s feedstock control and cost-cutting measures limited losses. Unlike pure traders, it weathered the storm better than peers.
#### Q: What’s next for Indorama’s net worth?
A: Analysts speculate on three potential paths:
1. Expansion into green chemicals (e.g., bio-based polymers).
2. A partial IPO to unlock capital for new projects.
3. Further Middle East investments (leveraging Saudi Arabia’s JV deals).
#### Q: Does Indorama Ventures have any environmental controversies?
A: Like most petrochemical firms, it faces scrutiny over emissions and plastic waste. However, its recent sustainability pledges (e.g., recycled polyester initiatives) aim to preempt regulatory crackdowns—though critics argue these are PR moves rather than systemic change.

