Where It All Began
India’s journey toward a significant ultra high net worth cohort began not with the dot-com boom of the 2000s, but with the liberalization of 1991—a turning point that unlocked capital flows, foreign investment, and the rise of a new corporate class. Before then, wealth in India was largely tied to land, industry, or government contracts. The post-liberalization era introduced stock markets to the masses, and with it, the first generation of self-made millionaires. By the late 1990s, the early signs of what would become India’s ultra high net worth ecosystem emerged in the form of tech entrepreneurs like N.R. Narayana Murthy of Infosys, whose IPO in 1993 created instant paper billionaires. These were the pioneers, but their numbers were still sparse. The real inflection came in the mid-2000s, when a perfect storm of global liquidity, commodity price surges, and India’s infrastructure push created a wealth multiplication effect. The Sensex crossed 10,000 for the first time in 2006, and suddenly, the country had its first notable cluster of ultra high net worth individuals—not just the industrialists, but also the new breed of professionals who had leveraged global markets. The Mumbai stock exchange became a wealth factory, turning retail investors into instant millionaires during the bull run of 2007–2008. Yet this boom was short-lived, crushed by the global financial crisis. The survivors of that crash—those who held onto assets or pivoted into cash-rich sectors like pharmaceuticals or IT—laid the foundation for the next wave.The Early Signs
The post-crisis recovery was slow, but by 2012, two trends became undeniable. First, the number of ultra high net worth individuals in India began to diversify geographically, moving beyond Mumbai to Delhi, Bengaluru, and Hyderabad. Second, wealth was no longer just about traditional industries. The rise of the Indian startup ecosystem—backed by venture capital from Silicon Valley and Dubai—began producing billionaires at an unprecedented rate. In 2014, Flipkart’s co-founders, Sachin and Binny Bansal, became the youngest self-made billionaires in India, their wealth tied not to family businesses but to e-commerce and digital infrastructure. The second half of the decade saw another shift: the entry of global capital into Indian real estate and private equity. Sovereign wealth funds from the Middle East and Asia began snapping up luxury residential projects in Mumbai and Goa, while domestic families consolidated wealth through real estate and gold. By 2019, India’s ultra high net worth population had grown to around 8,000, according to Credit Suisse’s Global Wealth Report. The COVID-19 pandemic then acted as an accelerant. Lockdowns forced a reevaluation of asset classes, with tech stocks and digital gold surging while traditional businesses faltered. The billionaire count nearly doubled in 2020–2021, with sectors like fintech, renewable energy, and space tech emerging as new wealth generators.The Turning Point
The true turning point arrived in 2021, when two parallel developments converged. First, India’s startup ecosystem matured, with unicorn valuations soaring and exit opportunities expanding. By mid-2022, India had over 100 unicorns, and the average valuation of a Series B round had crossed $100 million. Second, the government’s push for "Atmanirbhar Bharat" (self-reliance) redirected capital toward domestic industries, creating a feedback loop: more liquidity chasing fewer high-growth sectors, driving up asset prices. The result was a wealth creation engine that showed no signs of slowing. The final catalyst was the global reconfiguration of supply chains post-pandemic. India positioned itself as an alternative to China, attracting manufacturing investments in electronics, pharmaceuticals, and renewable energy. The projected increase in ultra high net worth individuals by 2025 is directly tied to this shift—foreign direct investment in manufacturing alone is expected to add $500 billion to India’s GDP by 2030, with a significant portion of that wealth trickling down to founders, investors, and executives."We’re not just creating billionaires; we’re creating a new class of wealth builders who think globally but operate locally. The next decade will see India’s ultra high net worth individuals become a force in global capital markets—not as recipients, but as players." — Rakesh Jhunjhunwala (deceased), legendary Indian investor, 2022
The Build-Up, Year by Year
| Period | Key Developments |
|---|---|
| 2015–2017 |
|
| 2018–2020 |
|
| 2021–2023 |
|
| 2024–2025 (Projected) |
|
Lessons From the Journey
- Wealth creation is no longer linear. The path to ultra high net worth status now includes exits, acquisitions, and global investments—not just organic business growth.
- Geographical diversification is critical. While Mumbai remains the wealth hub, Delhi’s policy influence and Bengaluru’s tech ecosystem are becoming equally vital.
- Asset class evolution is inevitable. Gold and real estate still dominate, but digital assets, private equity, and infrastructure are gaining ground.
- Global capital flows are a double-edged sword. Foreign investment fuels growth but also creates volatility, particularly in sectors like real estate.
- Succession planning is becoming urgent. As the first generation of self-made billionaires ages, the question of wealth transfer—whether to family, employees, or philanthropy—will define the next phase.
Where Things Stand Today
As of 2024, India’s ultra high net worth landscape is characterized by three dominant trends. First, the number of ultra high net worth individuals in India has already surpassed 12,000, with projections suggesting it will cross 15,000 by 2025. Second, the composition of this group is shifting: while industrialists and IT tycoons still dominate, a new cohort of founders in niche sectors—agritech, deep tech, and green energy—is rising. Third, wealth management is becoming increasingly sophisticated, with families and individuals turning to private banks, family offices, and offshore trusts to navigate tax complexities and global opportunities. The challenges, however, are equally pronounced. Infrastructure gaps, regulatory uncertainties, and social inequality threaten to undermine the potential. For every new billionaire, there are thousands of small businesses struggling with access to capital. The projected growth in ultra high net worth individuals by 2025 will only exacerbate these tensions unless structural reforms—from education to healthcare—keep pace with economic expansion.
Conclusion
India’s ultra high net worth story is far from over. The number of ultra high net worth individuals in India by 2025 will not just reflect economic growth; it will signal a broader transformation in how wealth is created, managed, and inherited. The country’s ability to harness this growth—without repeating the pitfalls of inequality and exclusion—will determine whether this wealth becomes a force for national development or a source of new divisions. What is clear is that India’s wealth elite are no longer passive beneficiaries of global trends. They are architects of change, investing in everything from space startups to sustainable cities. The question for policymakers, businesses, and society at large is how to ensure that this new era of prosperity is inclusive—and that the rise in ultra high net worth individuals translates into broader progress, not just concentrated power.Comprehensive FAQs
Q: What defines an ultra high net worth individual in India?
An ultra high net worth individual (UHNWI) in India is typically defined as someone with liquid assets exceeding $30 million. This includes cash, investments, real estate (excluding primary residence), and business interests. The threshold is higher than for high-net-worth individuals (HNWIs), who generally have assets between $1 million and $30 million.
Q: Which cities will see the most growth in ultra high net worth individuals by 2025?
Mumbai will remain the epicenter, followed by Delhi (driven by policy and diplomacy), Bengaluru (tech and startups), and Hyderabad (pharma and IT). Emerging hubs like Ahmedabad and Pune may also see significant growth as manufacturing and services expand.
Q: How does India’s ultra high net worth population compare globally?
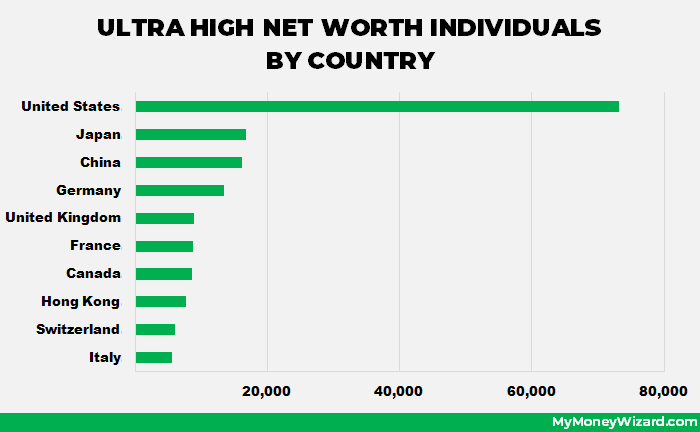
India’s number of ultra high net worth individuals is growing faster than most developed nations, though the absolute count remains lower than in the U.S., China, or Europe. By 2025, India could rank among the top 5 countries in terms of UHNWI growth rate, though its total population of such individuals will still lag behind China and the U.S.
Q: What sectors are driving the increase in ultra high net worth individuals?
Tech (especially fintech and SaaS), renewable energy, manufacturing (post-China relocation), and healthcare are the primary drivers. Traditional sectors like real estate and pharmaceuticals continue to contribute, but the fastest growth is in digital-native industries.
Q: Are there risks to the projected growth in ultra high net worth individuals?
Yes. Key risks include regulatory instability, which could deter foreign investment; asset bubbles in real estate and stocks; and social inequality, which may lead to political backlash. Additionally, global economic downturns or supply chain disruptions could slow the pace of wealth creation.
Q: How are ultra high net worth individuals in India managing their wealth?
Wealth management strategies are evolving. Many are diversifying into private credit, venture capital, and offshore investments, while others are setting up family offices to handle succession planning. Traditional assets like gold and real estate remain popular, but digital assets and alternative investments are gaining traction.
