The Complete Overview of Zerodha’s Net Worth
Zerodha’s rise from a single trader’s vision to a cornerstone of India’s fintech ecosystem is a study in execution. The company’s net worth isn’t just a balance sheet number—it’s a reflection of how India’s middle class now engages with capital markets. By 2024, Zerodha’s client base exceeded 10 million active traders, a milestone that translated into revenue streams spanning equities, derivatives, currency trading, and advisory services. The firm’s ability to cross-subsidize its free trading platform with higher-margin products (like mutual funds and insurance) created a self-sustaining engine, allowing it to reinvest profits into technology and talent. Yet, the net worth of Zerodha isn’t static. It fluctuates with market cycles, regulatory changes, and competitive pressures. For instance, the 2020–2021 bull run in Indian stocks swelled its order volumes, but it also exposed vulnerabilities—like the need to manage risk on its margin funding business. Analysts suggest that while Zerodha’s net worth is robust, its growth trajectory depends on maintaining its cost advantage while navigating a landscape where newer entrants (like Upstox or Groww) are testing the limits of its dominance.Historical Background and Evolution
Zerodha’s origins trace back to 2005, when Nithin Kamath, a former IT professional, began trading stocks with a modest capital of ₹10,000. Frustrated by the high brokerage fees (then as much as 0.5% per trade), he developed a simple trading software to automate orders. By 2010, he formalized the idea into Zerodha, launching with a zero-commission model that initially baffled traditional brokers. The gamble paid off: within a decade, Zerodha’s net worth surged as it captured market share from incumbents like ICICI Direct and HDFC Securities. The turning point came in 2015, when Zerodha introduced Kite, its web-based trading platform. Kite wasn’t just a tool—it was a reimagining of the trading experience, with real-time data, customizable dashboards, and seamless execution. This innovation slashed the learning curve for retail investors, accelerating user growth. By 2018, Zerodha’s net worth had ballooned enough to fund acquisitions, including Rainmatter, its venture capital arm, which later invested in startups like Sensebots (a robo-advisory platform). These moves reinforced Zerodha’s position as more than a brokerage—it became a fintech conglomerate.Core Mechanisms: How It Works
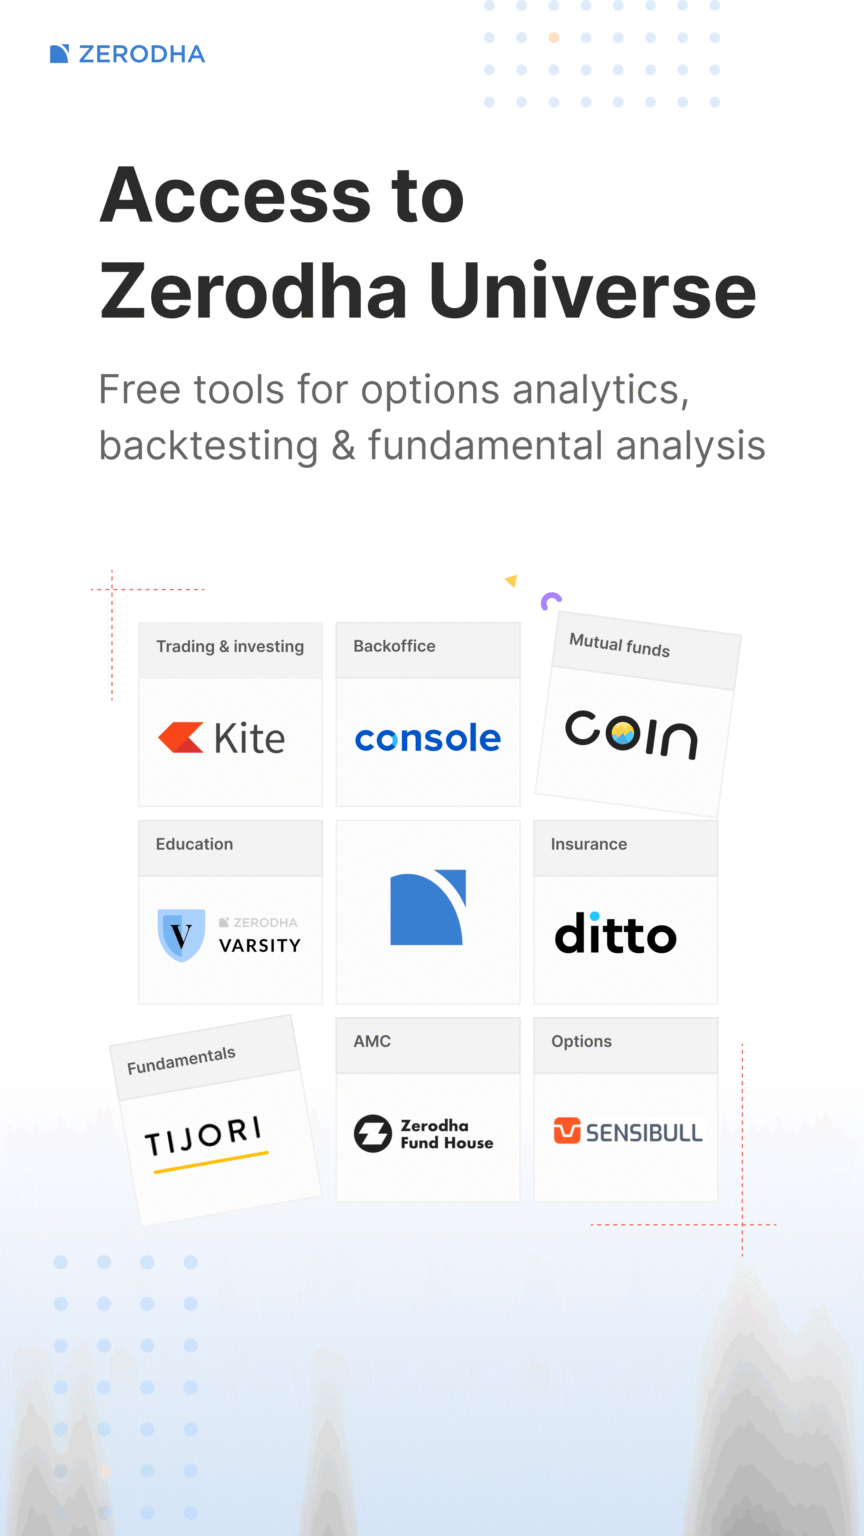
Zerodha’s business model is a masterclass in asymmetric monetization. The company offers zero brokerage on equity and F&O trades, a strategy that attracts volume. However, it compensates for this by charging for ancillary services: margin funding (where it earns interest), mutual fund distributions (via commissions), and insurance tie-ups. This multi-revenue-stream approach ensures that even as its core trading platform remains free, the net worth grows through higher-margin products. The model’s genius lies in its scalability. Zerodha’s technology stack—built in-house—handles millions of orders daily with minimal latency, reducing operational costs. It also leverages data analytics to offer value-added services like SenseX, a portfolio tracker, and Varsity, a free educational platform. These tools deepen user engagement, making customers less likely to switch to competitors. The result? A net worth that compounds as user stickiness increases, even in volatile markets.Key Benefits and Crucial Impact
Zerodha’s influence extends beyond its net worth. It has forced traditional brokers to slash fees, improved market liquidity, and educated a generation of retail investors. The company’s zero-commission model proved that profitability in brokerage isn’t tied to high fees but to volume, technology, and ancillary services. This shift reduced the cost of participation in India’s capital markets, enabling millions to invest who previously couldn’t afford brokerage charges. The broader impact is economic. By democratizing access, Zerodha has contributed to India’s retail investor boom, where first-time traders now account for a significant portion of market activity. Its net worth isn’t just a corporate metric—it’s a barometer of how far India has come in financial inclusion.“Zerodha didn’t just build a brokerage—it built an ecosystem where trading is accessible, transparent, and low-cost. That’s why its net worth matters beyond balance sheets.” — Rahul Gupta, Head of Retail Research at Kotak Securities
Major Advantages
- Cost leadership: Zero brokerage on equities and F&O trades undercuts traditional brokers, making it the default choice for volume traders.
- Technology-driven efficiency: In-house development ensures low latency and high scalability, reducing per-user costs.
- Diversified revenue streams: Margin funding, mutual funds, and insurance provide stable income even if trading volumes dip.
- Regulatory compliance as a strength: Zerodha’s adherence to SEBI norms has earned trust, unlike some unregulated fintech rivals.
- Brand loyalty through education: Platforms like Varsity and SenseX foster long-term engagement, reducing churn.
- Venture capital synergy: Rainmatter investments in fintech startups create a moat against disruptive competitors.
Comparative Analysis
| Metric | Zerodha | Upstox | ICICI Direct |
|---|---|---|---|
| Brokerage Model | Zero on equities/F&O; charges on margin, MFs, insurance | Zero on equities; charges on F&O and ancillaries | Commission-based (0.5%+ on equities) |
| Client Base (Active) | ~10 million | ~3 million | ~2.5 million |
| Revenue Streams | Trading volumes, margin interest, MF commissions, insurance | Trading volumes, margin, third-party products | Commissions, wealth management, loans |
| Net Worth/Valuation | Estimated $2–3 billion (private) | Acquired by RIL for ~$1 billion (2022) | Part of ICICI Bank (~$50B+ parent valuation) |
Future Trends and Innovations
Zerodha’s next phase will likely focus on global expansion and AI-driven advisory. The company has already dipped its toes into international markets via International Kite, catering to NRIs. If successful, this could diversify its net worth beyond India’s domestic cycles. Domestically, integrating AI into portfolio management (beyond its current robo-advisory tools) could further lock in users, especially as millennial investors seek automated solutions. Regulatory challenges remain. SEBI’s push for stricter margin rules or changes in tax policies could pressure Zerodha’s margin funding business—a key revenue driver. However, its net worth suggests it has the balance sheet to adapt. The bigger question is whether it can replicate its Indian success in markets like the UAE or Singapore, where fintech competition is fiercer.
Conclusion
Zerodha’s net worth is more than a financial figure—it’s a testament to how India’s digital-native generation interacts with money. By prioritizing accessibility over commissions, the company didn’t just build a brokerage; it redefined retail investing. Its growth trajectory, while impressive, isn’t without risks, particularly in a market where user acquisition costs are rising and competition is heating up. Yet, Zerodha’s ability to innovate while maintaining its core ethos sets it apart. Whether through Kite Connect (its API for third-party apps) or Rainmatter’s bets on fintech, the company continues to shape the future of wealth management. For investors and policymakers alike, watching Zerodha’s net worth evolve is less about stock prices and more about the broader story of financial democracy in India.Comprehensive FAQs
Q: How does Zerodha make money if it offers zero brokerage?
A: Zerodha monetizes through margin funding (interest on loans), mutual fund commissions, and insurance tie-ups. Its free trading platform attracts volume, while ancillary services ensure profitability. This model is sustainable because the cost per user is offset by high-margin products.
Q: Is Zerodha’s net worth publicly disclosed?
A: No, Zerodha is a private company and does not disclose exact financials. Industry estimates place its enterprise value between $2–3 billion, based on funding rounds, acquisitions, and revenue growth. Exact figures are speculative due to its unlisted status.
Q: Can Zerodha’s net worth be affected by market downturns?
A: Yes. While its core trading platform remains free, revenue from margin funding and mutual funds is sensitive to market conditions. A prolonged downturn could reduce trading volumes and loan demand, impacting its net worth. However, its diversified income streams mitigate some risks.
Q: Has Zerodha ever raised external funding?
A: Zerodha has been bootstrapped since inception, relying on internal cash flows. It has not taken external funding, which has allowed it to maintain full control over its operations and net worth growth without diluting equity.
Q: What role does Rainmatter play in Zerodha’s net worth?
A: Rainmatter, Zerodha’s venture capital arm, invests in fintech startups like Sensebots and Stashfin. These investments create synergies—such as cross-promoting products—and also generate returns that contribute to Zerodha’s overall financial health. They also position Zerodha as an innovator in the broader fintech ecosystem.
Q: How does Zerodha compare to Upstox in terms of net worth?
A: Zerodha’s net worth is estimated significantly higher than Upstox’s. While Upstox was acquired by Reliance Industries for ~$1 billion, Zerodha remains private with a valuation in the $2–3 billion range, reflecting its larger client base, stronger brand, and diversified revenue model.
Q: Could Zerodha go public in the future?
A: There’s no official indication of an IPO, but Zerodha’s net worth and growth make it a potential candidate for a future listing. However, founder Nithin Kamath has historically preferred organic growth over going public, citing risks of short-termism. Any decision would depend on market conditions and strategic priorities.
