The Short Answers
- Your wealth US percentile is your net worth’s rank compared to all US households, adjusted for inflation and household size.
- Top 1% wealth thresholds start around $10–$15 million for a family of four, but vary by state and asset type.
- Percentiles don’t account for debt, illiquidity, or regional cost of living—so a high rank in Texas might not translate to New York.
- Tax brackets, philanthropic deductions, and inheritance rules pivot at specific percentiles, often without public fanfare.
Deep Dive: The Full Picture
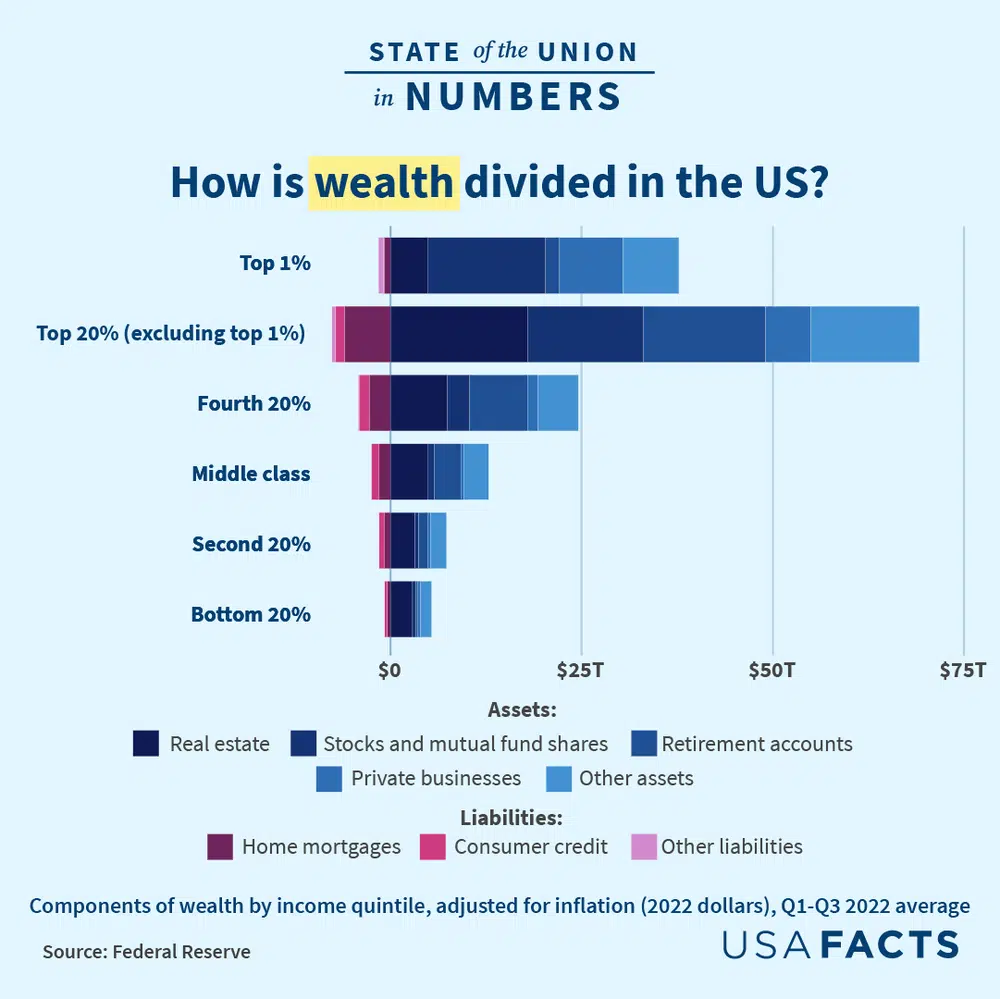
The wealth US percentile isn’t just a number—it’s a fractal of economic privilege. At the highest levels, it correlates with political influence, access to private healthcare, and even longevity. Studies show that top 1% households live an average of 7–10 years longer than those in the bottom quintile, partly due to better healthcare and lower stress. But the percentile also obscures critical details: a family with $20 million in illiquid assets (like a business or farmland) might rank in the top 0.1% on paper, yet face liquidity constraints that force them to sell at a loss. Meanwhile, a tech executive with $5 million in stocks could be in the top 5% but still feel "poor" if their portfolio tanks during a market correction. The data behind these rankings is flawed by design. The Federal Reserve’s Survey of Consumer Finances—the gold standard for wealth distribution—only samples about 5,000 households every three years. That means the percentile you’re assigned might be based on a dataset that’s six years out of date by the time you see it. And it ignores wealth concentration: the top 10% of Americans hold roughly 70% of all liquid assets, while the bottom 50% hold just 2.6%. If you’re not in that top decile, your percentile might as well be a participation trophy.The Context You Need
Wealth percentiles are not the same as income percentiles. Income is what you earn; wealth is what you own minus what you owe. A doctor earning $300,000 a year might have a wealth US percentile in the 85th percentile, while a retired teacher on $60,000 could be in the 90th if they own their home outright. The distinction matters because wealth compounds—literally. A household in the 99th percentile for wealth is 100x richer than one in the 50th percentile, according to Fed data. That’s not a linear gap; it’s exponential. Geography warps the numbers further. In Mississippi, a couple with $1.2 million might be in the top 5% of wealth holders. In Massachusetts, that same couple would rank in the bottom 20%. The Fed’s data adjusts for regional cost of living, but not for cultural capital—the unquantifiable advantage of knowing the right people in finance, law, or real estate. A high wealth US percentile in Silicon Valley won’t get you the same doors it would in Dallas, even if the dollar figures match.The Mechanics
Calculating your percentile starts with net worth: assets (cash, investments, real estate, business equity) minus liabilities (mortgages, student loans, credit card debt). The Fed’s model then ranks you against 124 million US households, using a log-normal distribution (which means the top 1% skews the curve dramatically). For example: - Top 10%: ~$1.1 million for a single person, ~$2.2 million for a family of four. - Top 1%: ~$10–$15 million for a family, but $30+ million in states like California or New York. - Top 0.1%: $30–$50 million+, where estate taxes and philanthropic strategies become critical. The catch? Debt isn’t treated equally. A mortgage reduces your net worth, but so does a private school tuition loan—yet the latter might not be reported in the same way. And if you own a business, its valuation can swing wildly based on market conditions. A tech startup valued at $50 million in 2021 might be worth $10 million in 2023, dropping you from the 99th to the 85th percentile overnight.Details That Change the Picture
Most people assume wealth percentiles are fixed, but they’re dynamic. A sudden inheritance, a stock market crash, or a divorce can reclassify you in months. The wealth US percentile you’re in at 30 might not match the one at 50—even if you never earn another dollar. That’s because wealth accumulation isn’t just about income; it’s about opportunity hoarding. The top 1% don’t just earn more; they invest differently. They use dynasty trusts, private equity, and offshore accounts to shield assets from taxes and inflation. Meanwhile, the middle class is left chasing 401(k) matches and real estate appreciation, both of which are highly volatile. The data also hides intergenerational wealth. A family that’s been wealthy for three generations might have a $50 million portfolio but only $5 million in liquid assets—placing them in the top 0.5% on paper, but the top 5% in spendable cash. That’s why some ultra-high-net-worth individuals underreport assets to avoid scrutiny, while others overreport to qualify for exclusive clubs or loans."Wealth isn’t just about money. It’s about the freedom to say ‘no’—to a job you hate, to a lifestyle you don’t want, to a system that tells you what you deserve. The percentile is the number that tells you whether you’ve earned that freedom… or if you’re still playing catch-up." — Economist Rachel Anderson, author of The Invisible Ledger
| Wealth US Percentile | Net Worth Threshold (Family of 4) |
|---|---|
| 75th Percentile | $1.2 million |
| 90th Percentile | $2.2 million |
| 99th Percentile | $10–$15 million |

Conclusion
Understanding your wealth US percentile isn’t about vanity—it’s about strategy. If you’re in the top 1%, your tax planner, estate attorney, and investment advisor should operate with a different playbook than someone in the 90th percentile. If you’re below the median, you’re playing by rules designed to keep you there. The percentile reveals who gets to write the rules and who has to follow them. But here’s the hard truth: knowing your rank doesn’t change the system. It only tells you whether you’re positioned to exploit its loopholes—or get crushed by them. The next time someone asks, "What’s your wealth US percentile?", don’t just give them a number. Ask them what they plan to do with it. Because the real question isn’t where you stand—it’s whether you’re moving the ladder.Comprehensive FAQs
Q: How often should I check my wealth US percentile?
Annually, but with caveats. Market fluctuations, debt paydowns, and major purchases (like a home or business sale) can shift your rank. However, obsessing over the number can lead to emotional investing—stick to long-term goals rather than percentile chases.
Q: Does my wealth percentile change if I move states?
Yes, dramatically. A $3 million net worth might put you in the top 3% in Texas but the top 1% in New York. The Fed’s data adjusts for regional costs, but local wealth norms (e.g., old-money Southern families vs. tech billionaires in Silicon Valley) create additional layers of disparity.
Q: Can I "game" my wealth percentile to appear richer?
Technically, yes—but it’s risky. Overvaluing assets (like a business or art collection) can inflate your net worth on paper, but audits or market corrections will expose the fraud. Legitimate strategies include converting illiquid assets to cash (e.g., selling a business) or leveraging trusts to optimize taxable wealth.
Q: Why do some people in the top 1% feel "poor"?
Liquidity is the silent killer of high-net-worth households. A family with $50 million in private equity or farmland might have $5 million in spendable cash, forcing them to sell assets at a discount. Meanwhile, tax obligations (capital gains, estate taxes) can eat into wealth faster than inflation. The percentile doesn’t account for cash flow constraints.
Q: How does divorce affect my wealth US percentile?
Catastrophically, if assets are split unevenly. A 50/50 division of a $20 million portfolio drops you from the 99.9th to the 90th percentile overnight. Prenuptial agreements, postnuptial trusts, and asset protection strategies (like holding property in LLCs) can mitigate this—but they require planning years in advance.
Q: Is there a "safe" wealth percentile to retire comfortably?
No single answer, but 75th percentile or higher gives a buffer against market downturns and healthcare costs. The Fed’s retirement rule of thumb suggests 25x annual expenses in savings, but this varies by state. For example, a couple in Florida might retire comfortably at $1.5 million, while one in Connecticut needs $3 million for the same lifestyle.
