
Breaking Down the Numbers
The US household net worth percentile 2025 will be defined by two competing trends: the relentless climb of asset prices for those already invested in the market, and the persistent struggle of households with little to no exposure to equities or real estate. The Federal Reserve’s Survey of Consumer Finances (SCF) remains the gold standard for these measurements, but its triennial snapshots—last updated in 2022—won’t capture the full volatility of 2023–2025. What we do know is that the median net worth (50th percentile) has hovered around $180,000 in recent years, while the 90th percentile sits near $2.2 million. Yet these figures mask critical regional and demographic variations: a household in San Francisco may have a net worth skewed by tech stock options, while one in rural Ohio relies on farm equity or Social Security. The US household net worth percentile 2025 will also be shaped by inflation-adjusted returns. If the S&P 500 delivers mid-single-digit gains annually—historically robust but not unprecedented—the top decile could see net worth growth outpace the bottom 50% by a factor of three or more. The challenge lies in separating signal from noise. For example, the Fed’s balance sheet reduction in 2023–2024 tightened liquidity, potentially cooling asset bubbles in commercial real estate and crypto. Meanwhile, the Biden administration’s proposed capital gains tax hikes (if enacted) could deter high-net-worth individuals from realizing gains, further compressing the top percentiles’ growth.The Verified Baseline
The most reliable data comes from the Federal Reserve’s 2022 SCF, which showed that the US household net worth percentile distribution had widened since the pandemic recovery. The median net worth for households headed by someone under 35 was $42,000, compared to $320,000 for those aged 55–64—a gap that reflects both delayed homeownership and the compounding effects of student debt. The 90th percentile threshold, meanwhile, was $2.2 million, with the top 1% clearing $17 million. These figures are static, but they provide a baseline for projecting 2025 outcomes. What’s verifiable is that homeownership remains the single largest driver of wealth accumulation for the middle class. In 2022, owner-occupied housing accounted for 65% of total net worth for the median household, while financial assets (stocks, bonds, retirement accounts) made up 25%. The remaining 10% consisted of business equity, vehicles, and other illiquid holdings. This structure suggests that any slowdown in housing appreciation—or a correction in valuations—would disproportionately affect the US household net worth percentile 2025 rankings of those relying on home equity.What the Estimates Suggest
Industry estimates for the US household net worth percentile 2025 vary widely, but most models converge on a few key assumptions. First, if the labor market remains tight and wage growth outpaces inflation (a big if), the median net worth could inch upward by 2–4% annually, assuming steady home price appreciation. However, this growth would be concentrated in high-cost metros where inventory constraints keep prices elevated. For the bottom 40% of households, net worth gains would likely stagnate or decline, as stagnant wages fail to offset rising costs for healthcare, education, and childcare. Second, the top decile’s wealth is expected to grow at a 5–7% annualized rate, driven by equity markets and private asset classes. BlackRock and Goldman Sachs projections suggest that by 2025, the US household net worth percentile for the top 10% could exceed $3 million, with the top 1% nearing $25 million. These figures assume continued strong performance in AI-related stocks, venture capital, and real estate syndications—sectors where wealth concentration is accelerating. The caveat? These estimates rely on sustained low interest rates, which may not hold if the Fed pivots aggressively in response to inflation.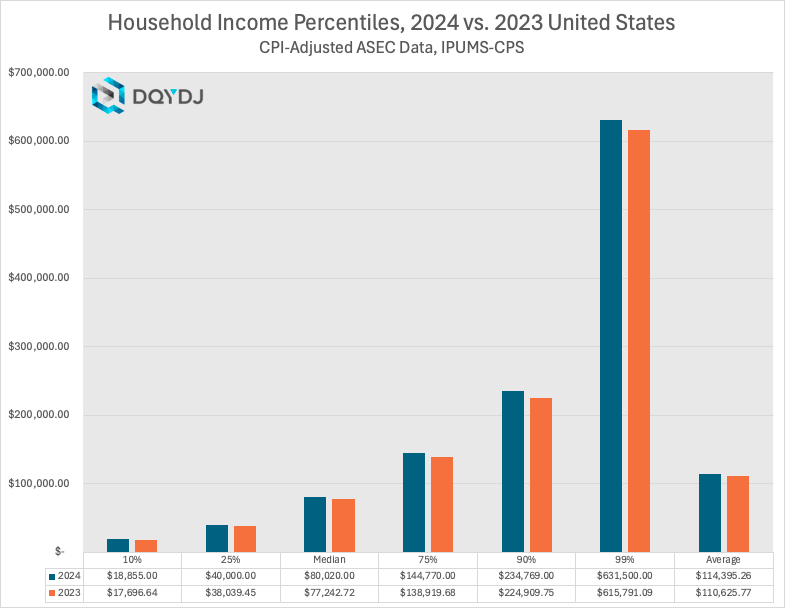
Case Study: A Closer Look
Consider the hypothetical case of the Smith family, a middle-class couple in Austin, Texas, with two children. In 2023, their net worth sits at $650,000, placing them in the 80th percentile of the US household net worth percentile 2025 projections. Their wealth is split evenly between home equity (a $500,000 primary residence) and retirement accounts ($150,000). Their financial strategy hinges on maximizing 401(k) contributions and refinancing their mortgage at current rates. If home prices in Austin rise by 5% annually and their 401(k) earns 6%, their net worth could reach $900,000 by 2025—moving them into the 85th percentile. Yet this outcome depends on critical variables. A 3% drop in home values (plausible in a recession) would erase $15,000 in equity annually, pushing their percentile down to the 78th. Conversely, if one spouse lands a high-paying tech job with stock options, their net worth could spike to $1.2 million, catapulting them into the 92nd percentile. The case illustrates how US household net worth percentile 2025 rankings are less about fixed thresholds and more about exposure to volatile asset classes."The percentile you’re in today might not mean much if your asset mix shifts. A homeowner in 2025 could be wealthier on paper but cash-poor if they’re underwater on a variable-rate mortgage." — Diane Lim, Senior Economist at Moody’s Analytics
| Factor | Estimated Impact on 2025 Percentile |
|---|---|
| Home Price Appreciation (+5%) | +3–5 percentile points (if equity is primary asset) |
| Stock Market Correction (-15%) | –2–4 percentile points (if 401(k) is 30%+ of net worth) |
| Wage Growth (+4% vs. Inflation +3%) | +1–2 percentile points (if savings rate remains high) |
What This Means Going Forward
The US household net worth percentile 2025 will force a reckoning with how wealth is measured—and who benefits from its growth. For policymakers, the data underscores the need for targeted interventions, such as expanded access to retirement accounts for gig workers or tax incentives for first-time homebuyers. For individuals, the takeaway is simpler: liquidity matters more than ever. A household with a high net worth but little cash flow (e.g., tied up in a rental property or private equity) may struggle in a downturn, even if their percentile ranking stays high. The other critical shift is the rise of alternative wealth metrics. Traditional percentiles ignore the value of human capital (e.g., skills in AI or healthcare) and social capital (networks that unlock opportunities). By 2025, the US household net worth percentile may need to incorporate these factors to reflect real economic mobility. For now, though, the numbers tell a story of deepening inequality—and the tools to navigate it are unevenly distributed.
Conclusion
The US household net worth percentile 2025 will not be a single, static line on a graph but a moving target influenced by policy, technology, and global shocks. What’s certain is that the gap between those who own assets and those who don’t will widen, unless deliberate steps are taken to broaden participation in wealth-building. For the median household, the path to higher percentiles will require aggressive saving, strategic debt management, and—crucially—a willingness to take calculated risks in volatile markets. For those already in the top tiers, the challenge is different: preserving wealth in an era of potential tax reforms and geopolitical instability. The US household net worth percentile 2025 will ultimately be a reflection of who could adapt to change—and who got left behind.Comprehensive FAQs
Q: How often are US household net worth percentiles updated?
The Federal Reserve’s Survey of Consumer Finances is released every three years, with the most recent data from 2022. For 2025 projections, analysts rely on annual Fed reports, private sector estimates (e.g., from BlackRock or Goldman Sachs), and real-time market indicators like the S&P 500 and Case-Shiller home price indices.
Q: Will student debt affect my net worth percentile in 2025?
Absolutely. Student loan balances reduce net worth directly, and borrowers under 40—who carry $300+ billion in federal student debt—are more likely to be in the bottom 60% of the US household net worth percentile 2025 distribution. Even if loans are forgiven, the lost decade of compounding savings (due to high monthly payments) can depress net worth by 15–25% compared to non-borrowers.
Q: Are there regional differences in net worth percentiles?
Yes. The median net worth in New York or California is ~40% higher than in Mississippi or West Virginia, largely due to home values and stock ownership. For example, a household in San Francisco with a $1.5 million home may rank in the 95th percentile nationally but only the 70th percentile locally—because local home prices are so elevated.
Q: How does inflation impact net worth percentiles?
Inflation erodes the real value of assets like cash and bonds, but it can boost home equity if wages rise faster than prices. In 2025, households with short-term debt (credit cards, auto loans) will see their net worth percentiles shrink more than those with long-term fixed-rate mortgages or equity exposure. The Fed’s inflation targeting will be the wild card.
Q: Can I improve my net worth percentile by 2025?
Yes, but it requires asset diversification and risk tolerance. For example, a household in the 60th percentile could jump to the 75th by:
- Maximizing 401(k) contributions (especially if the employer matches)
- Refinancing high-interest debt (e.g., credit cards at 20% APR)
- Investing 10% of income in index funds (historically, this strategy adds $50K+ to net worth over a decade)
Q: What’s the biggest threat to net worth growth in 2025?
The Fed’s monetary policy poses the greatest risk. If rates rise sharply to combat inflation, home values could drop 10–15% in some markets, and stock valuations may revert to historical averages. For the US household net worth percentile 2025, this would mean:
- Bottom 50%: Little to no growth (wages stagnant, debt burdens high)
- Top 10%: Slower growth (illiquid assets like private equity less attractive)
- Middle class: Mixed results (homeowners gain if they refinance; renters lose)
Q: How do generational differences play into net worth percentiles?
Millennials and Gen Z are 10–15 percentile points behind Boomers at the same life stage due to:
- Higher student debt loads
- Delayed homeownership (median age for first purchase: 36 vs. 32 in 2000)
- Lower unionization rates (wage suppression)
Q: Are there any bright spots for lower percentiles?
Yes, but they require structural shifts:
- Child Tax Credit expansions (if renewed) could lift the bottom 30% by $5K–$10K annually
- Employer-sponsored retirement plans for gig workers (e.g., Uber’s pilot program) may boost savings rates
- Down payment assistance programs (e.g., in Texas and Florida) help first-time buyers enter the housing market
