The Short Answers
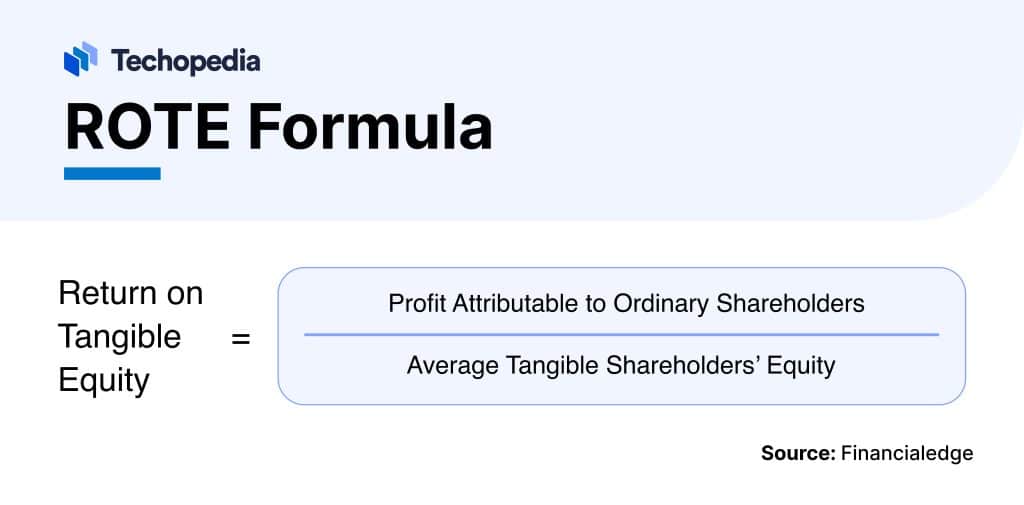
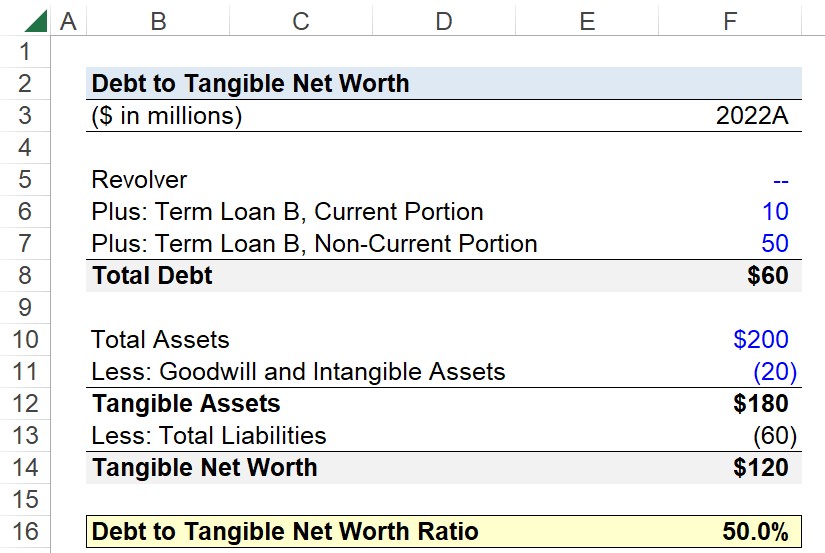
- Return on tangible net worth isn’t a single formula—it’s a framework for measuring how physical assets generate cash flow, tax shields, or appreciation beyond traditional financial returns.
- Liquidity and time horizons matter more than with paper assets; a 10-year hold on timberland might yield 12% annually, but selling too soon could erase gains.
- Tax efficiency is often the hidden driver—depreciation schedules, 1031 exchanges, and carried interest can turn a 3% paper return into an 8% after-tax effective return.
- Overleveraging tangibles (e.g., mortgaging a farm to buy more land) can backfire if cash flow doesn’t cover debt service during downturns.
- The biggest mistake? Treating all tangibles as "safe" investments—vintage wine might appreciate, but a warehouse in a shrinking market might not.
Deep Dive: The Full Picture
Wealth isn’t passive. It’s a series of trade-offs between control, risk, and return. Paper assets—stocks, bonds, crypto—trade on liquidity and market sentiment. Tangibles, by contrast, demand operational expertise. A portfolio of rare books requires climate-controlled storage, insurance, and a network of buyers. A commercial building needs tenants, maintenance, and zoning compliance. These aren’t just investments; they’re small businesses with overhead. The return on tangible net worth isn’t just about appreciation. It’s about what the asset does for you while you own it—whether that’s a steady rental income stream, a tax write-off from depreciation, or the ability to hedge against inflation by holding hard assets. The challenge lies in the data. Financial advisors rarely track tangible assets with the same rigor as public equities. A client might list "real estate" as a single line item on a balance sheet, but that obscures critical details: Is it raw land, developed property, or a mixed-use complex? What’s the cap rate? Are there hidden liabilities like environmental remediation costs? Without granularity, you can’t measure true return on tangible net worth. Take a private aircraft: Its value might drop 20% in five years, but if it generates $1 million annually in charter revenue while depreciating, the effective return could still be positive. The same logic applies to a vineyard—grapes don’t trade like S&P 500 shares, but their yield, weather risks, and wine auction trends dictate real returns.The Context You Need
The rise of tangible asset investing mirrors a broader shift: disillusionment with financialized returns. After the 2008 crash and the subsequent era of near-zero interest rates, institutional investors piled into alternatives—private equity, hedge funds, and, increasingly, hard assets. The S&P 500’s long-term average return of ~10% no longer feels like a given. Meanwhile, inflation erodes cash’s purchasing power, and geopolitical risks make supply chains—and the commodities they rely on—more volatile. In this environment, tangibles offer three distinct advantages: 1. Inflation hedging: Land, gold, and collectibles often outpace consumer price increases. 2. Control: You set the terms—rent prices, operational costs, or even whether to sell. 3. Tax efficiency: Depreciation, expense write-offs, and like-kind exchanges can defer or eliminate capital gains. Yet these benefits come with asymmetrical risks. A stock portfolio might drop 30% in a year but recover. A vineyard hit by drought or a shift in consumer tastes might never rebound. The key isn’t avoiding risk; it’s aligning your tangible assets with a strategy that accounts for their unique lifecycle.The Mechanics
Measuring return on tangible net worth requires breaking free from traditional finance’s playbook. Start with cash flow, not just appreciation. A $2 million apartment building might appreciate 4% annually, but if it generates $120,000 in net rent after expenses, that’s a 6% unlevered yield—before factoring in debt or tax benefits. Now add leverage: a 70% LTV mortgage at 5% interest could push the after-debt return to 18%. But if vacancy rates spike, maintenance costs rise, or interest rates climb, that yield evaporates. Then consider time decay. A classic car might appreciate for 20 years before its engine fails and parts become scarce. A timberland investment’s return depends on the rotation cycle—how long it takes to harvest and replant. Even art requires a holding period to prove its worth; a painting bought for $100,000 might sell for $150,000 in five years, but if it costs $5,000 annually to insure and store, the real return is closer to 3%—not the 10% headline. The mechanics aren’t about picking winners; they’re about matching the asset’s rhythm to your financial goals.Details That Change the Picture
Not all tangibles behave the same. A portfolio of blue-chip real estate in gateway cities might deliver steady cash flow, but it’s vulnerable to interest rate shocks. Commodity-linked assets—like farmland or oil wells—benefit from inflation but require deep sector knowledge. Collectibles—wine, watches, rare stamps—can outperform stocks over decades, but they demand provenance, storage, and exit liquidity. The mistake? Assuming tangibles are "safe" because they’re "real." A warehouse in Detroit’s empty downtown isn’t a hedge; it’s a bet on urban revival. The real leverage comes from stacking strategies. A family might hold: - Income-generating assets (rental properties, timberland leases) - Appreciation plays (vineyards, development land) - Liquidity buffers (gold, short-term leases) Each serves a different role in the portfolio. The goal isn’t to maximize one metric—it’s to balance risk, control, and return across the tangible spectrum."You can’t manage what you can’t measure. Most people look at their net worth once a year. We track tangible assets monthly—cash flow, depreciation, and market signals. That’s how you spot opportunities before they become obvious." — James Chen, CIO of a $4B family office specializing in alternative assets
| Asset Class | Key Return Driver |
|---|---|
| Commercial Real Estate | Net operating income (NOI) + appreciation (if leveraged) |
| Agricultural Land | Crop yields + inflation-linked rental income |
| Collectibles (Art/Wine) | Provenance + auction demand (long-term holding) |
Conclusion
Return on tangible net worth isn’t a niche concern—it’s the future of wealth management for those who refuse to bet everything on paper. The shift isn’t about abandoning stocks or bonds; it’s about recalibrating the balance. A portfolio that ignores tangibles risks missing out on the most resilient wealth generators: assets that produce, preserve, and protect value in ways no ETF can. The catch? It requires active management, not passive indexing. You can’t set and forget a vineyard or a warehouse. You need to understand its operational DNA—what makes it tick, what breaks it, and how to extract value without destroying it. The good news? The tools exist. Data providers now track tangible asset performance with granularity. Family offices and institutional investors are allocating more capital to direct ownership of hard assets. The question isn’t whether return on tangible net worth matters—it’s whether you’re positioned to capture it before the market does.Comprehensive FAQs
Q: How do I calculate return on tangible net worth for my own portfolio?
A: Start by categorizing assets into cash-flowing (rental income, leases) and appreciation-based (land, collectibles). For cash-flowing assets, divide annual net income by current value. For appreciating assets, use a weighted average cost basis and track market comps. Tools like Costar (real estate) or ArtTactic (art) can help, but a CPA familiar with tangible assets is essential for tax-adjusted returns.
Q: Are tangibles always better than paper assets in a downturn?
A: No. While land and commodities often hold value, leverage exposure can amplify losses. A highly mortgaged property portfolio can collapse faster than a diversified stock index. The key is asset selection: raw land may survive recessions, but a luxury hotel might not. Always stress-test your tangible holdings against worst-case scenarios (e.g., 100% vacancy, commodity price crashes).
Q: Can I use a 1031 exchange to defer taxes on tangible assets indefinitely?
A: Technically, yes—but the IRS limits exchanges to like-kind properties (e.g., swapping one rental building for another). You can’t 1031-exchange into stocks or land held for personal use. Also, timing matters: If you sell a building for a gain and reinvest in another, you must close the new purchase within 180 days. Missteps can trigger unexpected tax bills. Consult a tax attorney specializing in alternative asset structuring before executing.
Q: What’s the biggest misconception about return on tangible net worth?
A: That it’s automatic. Many assume owning an asset guarantees returns, but management kills more portfolios than market downturns. A vineyard left to vine (literally) won’t produce. A rental property with deferred maintenance will lose tenants. The return isn’t in the asset itself—it’s in how you steward it. This requires either expertise or a trusted team (property managers, farm advisors, auctioneers).
Q: How do I know if my tangible assets are overperforming or underperforming?
A: Benchmark against peer groups. For real estate, compare your cap rate to local averages. For collectibles, track auction results in your category (e.g., Bordeaux wine vs. Burgundy). For commodities, monitor futures prices and storage costs. If your returns consistently trail peers, ask: Are you underleveraged (missing growth) or overleveraged (risking collapse)? Adjust accordingly—or consider selling underperformers and redeploying capital.
