
Common Myths About Retiree Net Worth Percentiles
The first myth is that retiree net worth percentiles are a reliable predictor of retirement success. They’re not. A retiree in the 75th percentile—say, with a net worth of $500,000—might still face cash-flow crises if they’ve underestimated healthcare costs or overestimated Social Security benefits. Percentiles are static measurements; retirement is a dynamic process. The second myth is that hitting a certain percentile guarantees comfort. In reality, a retiree in the 90th percentile could be drowning in debt if they’ve leveraged their portfolio aggressively or if their investments are concentrated in volatile assets. Percentiles tell you where you stand relative to others, not whether you’re prepared for the unexpected. The third persistent myth is that retiree net worth percentiles are the same across regions, income brackets, and lifestyles. They’re not. A retiree in San Francisco with a $1.2 million net worth might be in the 85th percentile locally but the 50th percentile nationally. Meanwhile, a retiree in rural Iowa with $800,000 could be in the top 5% of their community. These figures are context-dependent, yet most financial advice treats them as universal. The result? Retirees either overconfidently assume they’re ahead or underestimate their true position because they’re comparing apples to oranges.Myth 1: "If you’re in the top 20% of retiree net worth percentiles, you’re set."
The assumption here is that the top 20% have solved all retirement problems. In truth, the top 20% often face different challenges: managing large portfolios, navigating estate taxes, or dealing with the pressure of maintaining a high standard of living. A retiree with a $2 million net worth might still struggle with sequence-of-returns risk—losing 20% of their portfolio early in retirement can erode decades of savings. Additionally, the top percentiles are disproportionately concentrated in home equity, which isn’t liquid. Selling a primary residence to access cash isn’t always an option, especially in tight housing markets. What’s more, the top retiree net worth percentiles are heavily skewed by those who’ve benefited from inheritance, real estate booms, or defined-benefit pensions—none of which are replicable for the average worker. The data shows that even within the top 20%, there’s a vast divide between those who’ve optimized their wealth (through tax-efficient withdrawals, for example) and those who’ve simply been lucky. Percentiles don’t account for these nuances; they only show where you stand in a snapshot, not how well you’re positioned for the long haul.Myth 2: "The median retiree net worth percentile is a good target to aim for."
Aiming for the median—often cited as around $280,000—is like aiming for "average" health. It’s a statistical middle ground, but it doesn’t account for the fact that the median retiree may still face liquidity issues, high debt-to-income ratios, or inadequate healthcare coverage. The median is also misleading because it doesn’t reflect the concentration of wealth at the top. If you’re in the median, you’re likely better off than the bottom 50%, but you’re still vulnerable to inflation, rising costs, and unexpected expenses. Worse, the median retiree net worth percentile is a moving target. Due to inflation, rising healthcare costs, and stagnant wage growth, what was once considered a comfortable median net worth may no longer be sufficient. For example, a retiree who retired in 2010 with a median net worth might find that their purchasing power has eroded significantly by 2024. Percentiles are backward-looking; they don’t predict future needs. The real question isn’t whether you’ve hit the median but whether your assets can generate enough income to cover your expenses in retirement.Myth 3: "Your retiree net worth percentile stays the same after retirement."
This is one of the most dangerous assumptions. A retiree’s percentile can shift dramatically depending on market conditions, spending habits, and unexpected events. For instance, a retiree in the 60th percentile who experiences a bear market early in retirement might drop to the 40th percentile if they’re forced to sell assets at a loss. Conversely, a retiree in the 40th percentile who inherits $500,000 could jump to the 70th percentile overnight. Percentiles aren’t fixed; they’re fluid, and they react to both personal decisions and external shocks. The confusion arises because most financial planning tools treat net worth as a static number, when in reality it’s a dynamic variable. A retiree’s percentile can change based on how they manage withdrawals, how their investments perform, and even how long they live. The longer you’re in retirement, the more your percentile can fluctuate. This is why focusing solely on a retiree net worth percentile is shortsighted—it ignores the reality of retirement as an ongoing process, not a single moment in time.
What Holds Up to Scrutiny
What actually matters isn’t just where you stand in the retiree net worth percentile rankings but whether your assets can generate sustainable income. The data shows that retirees who focus on income replacement—ensuring their withdrawals don’t exceed 4% of their portfolio annually—are far more likely to maintain their standard of living than those who chase a specific percentile. This approach, popularized by the Trinity Study, has held up under decades of backtesting, even through multiple market crashes. Another verifiable truth is that home equity plays an outsized role in retiree net worth percentiles. Studies consistently show that homeowners have significantly higher net worth in retirement than renters, not because they’re better investors but because housing wealth compounds over time. However, this equity isn’t always liquid, which is why strategies like reverse mortgages or downsizing are critical for those who rely on home equity to boost their percentile. The key takeaway? Percentiles are useful for benchmarking, but they’re meaningless if they don’t translate into reliable income."Percentiles are like weather reports—they tell you what’s happening now, not what’s coming next. The real work of retirement planning isn’t hitting a number; it’s building a system that adapts to whatever the market throws at you." — Michael Kitces, Director of Planning Strategy at Buckingham Wealth Partners
| Common Belief | What the Evidence Says |
|---|---|
| Being in the top 10% of retiree net worth percentiles means you’re financially secure. | Top percentiles often face unique challenges like estate taxes, portfolio complexity, and maintaining lifestyle inflation. |
| The median retiree net worth percentile is a safe target. | The median doesn’t account for rising costs, healthcare inflation, or liquidity needs—many median retirees still struggle with cash flow. |
| Your retiree net worth percentile stays stable after retirement. | Percentiles fluctuate based on market returns, spending habits, and unexpected events like inheritance or medical expenses. |
| Investment returns alone determine your retiree net worth percentile. | Debt levels, healthcare costs, and lifestyle choices often have a bigger impact than market performance. |
| Percentiles are the same across regions and lifestyles. | Cost of living, local tax policies, and housing markets create vast regional differences in what a given percentile actually means. |
Why the Confusion Persists
The confusion around retiree net worth percentiles is partly due to how financial media simplifies complex data. Headlines like "You Need $1 Million to Retire" overshadow the reality that $1 million might be enough in a low-cost state but insufficient in a high-tax, high-healthcare-cost area. Additionally, the rise of robo-advisors and algorithmic financial planning has led many to assume that hitting a certain percentile is the end goal, when in reality, it’s just one piece of a much larger puzzle. Another factor is the lack of standardized reporting. Different studies use different methodologies to calculate retiree net worth percentiles—some include home equity, others don’t; some adjust for inflation, others don’t. This inconsistency means that when you see a headline claiming "the average retiree has X," it’s often comparing apples to oranges. Without a universal framework, retirees are left guessing whether they’re ahead or behind, and financial advisors struggle to provide clear, actionable advice.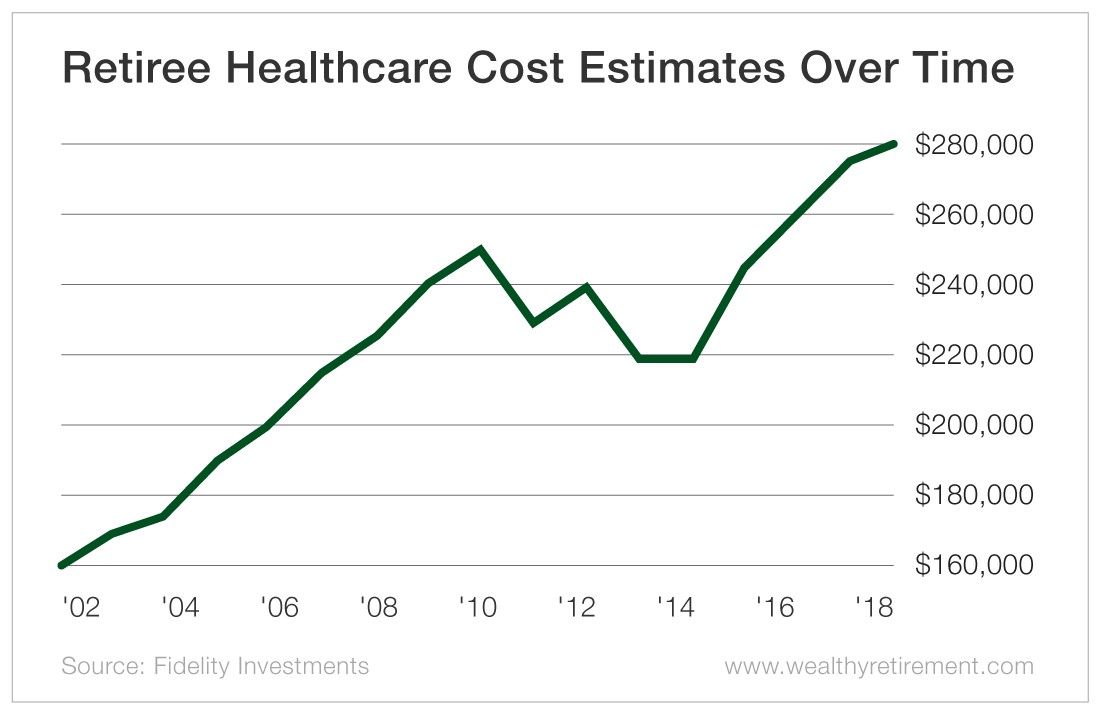
Conclusion
Retiree net worth percentiles are useful for understanding where you stand relative to your peers, but they’re far from the complete picture. The real measure of retirement readiness isn’t a percentile—it’s whether your assets can generate enough income to cover your expenses for the rest of your life. This requires a focus on sustainable withdrawals, diversification, and adaptability, not just hitting a benchmark. Percentiles are a starting point, not an endpoint. The best approach is to use retiree net worth percentiles as a tool for reflection, not a rulebook. If you’re in the bottom 20%, the goal isn’t to climb the ladder—it’s to ensure your existing assets are working as efficiently as possible. If you’re in the top 10%, the challenge is managing complexity and avoiding lifestyle inflation that could derail your long-term security. In both cases, the focus should be on income, not just net worth. A high percentile means little if you can’t convert it into reliable cash flow.Comprehensive FAQs
Q: How often should I check my retiree net worth percentile?
A: Annually is sufficient unless you’ve had major life changes—inheritance, divorce, early retirement, or a significant market shift. Obsessing over quarterly fluctuations can lead to emotional decisions, like selling assets at the wrong time. Percentiles are a long-term gauge, not a short-term stressor.
Q: Does my retiree net worth percentile change if I move to a lower-cost state?
A: Yes, but not in the way you might think. While your absolute net worth stays the same, your percentile could shift because the cost of living and local wealth distribution differ. For example, a $1 million net worth might put you in the 90th percentile in Mississippi but only the 70th in California. The key is whether your income needs adjust proportionally to your new expenses.
Q: Can I improve my retiree net worth percentile before retiring?
A: To some extent, but the levers are limited. The most effective strategies are maximizing 401(k)/IRA contributions, paying off high-interest debt, and optimizing tax-efficient withdrawals in retirement. However, late-career windfalls (like bonuses or inheritances) can have a disproportionate impact. The earlier you start, the more your percentile will benefit from compounding.
Q: Does Social Security count toward my retiree net worth percentile?
A: No, because Social Security benefits are an annuity, not an asset. Net worth calculations typically exclude future income streams like pensions or Social Security. That said, your Social Security benefit amount will directly affect your cash flow in retirement, which is why it’s a critical factor in sustainability—even if it doesn’t show up in percentile rankings.
Q: What’s the biggest mistake retirees make with their net worth percentile?
A: Assuming it’s a fixed achievement rather than a dynamic metric. Many retirees stop planning once they hit a "comfortable" percentile, only to face unexpected costs (like long-term care) that erode their position. The biggest mistake is treating percentiles as a destination rather than a checkpoint in an ongoing process.
Q: How do healthcare costs affect my retiree net worth percentile?
A: Healthcare is the silent wealth destroyer. A retiree in the 60th percentile might drop to the 40th within five years if they underestimate Medicare premiums, prescription drugs, or long-term care. The data shows that healthcare expenses can account for 20-30% of retirement spending, yet most percentile benchmarks don’t account for this. A better approach is to set aside a dedicated healthcare fund.
Q: Are retiree net worth percentiles different for couples vs. singles?
A: Yes, significantly. Couples often have higher percentiles due to dual incomes, but they also face joint liabilities (like shared debt or caregiving responsibilities). Singles, meanwhile, may have lower percentiles but benefit from simpler financial structures. The key difference is that couples’ percentiles are more volatile—divorce, one spouse’s health decline, or unequal wealth accumulation can shift rankings dramatically.
Q: What’s the most overlooked factor in retiree net worth percentiles?
A: Longevity risk. Most percentile calculations assume a retirement lifespan of 20-30 years, but with life expectancy rising, many retirees now face 30+ years in retirement. A retiree in the 75th percentile at 65 might drop to the 50th by 85 if they haven’t accounted for an extended retirement horizon. The solution? Dynamic withdrawal strategies that adjust for inflation and health declines.
