Breaking Down the Numbers
The primary residence as percentage of net worth serves as a stress test for personal finance. When this ratio exceeds 50%, households enter a high-risk zone where external shocks—job loss, medical expenses, or market corrections—can force distress sales or reverse mortgages. The threshold varies by lifecycle stage: a 35-year-old with a 30-year mortgage may tolerate a 40% exposure, while a 65-year-old with no other assets might see 75% as necessary. The key variable isn’t the percentage itself but the liquidity gap it creates. A home worth $500,000 against $600,000 in net worth (83% exposure) offers no buffer for unexpected costs. This concentration also distorts financial behavior. Studies from the Urban Institute show that homeowners with high primary residence exposure delay retirement, avoid career risks, or skip investments in volatile markets—all to preserve home equity. The phenomenon isn’t uniform. In high-cost cities like San Francisco or New York, the primary residence as a share of net worth often exceeds 90% for median-income earners, while in lower-cost regions, it may hover around 50%. The disparity reflects both local housing markets and cultural attitudes toward debt. In some communities, a mortgage is seen as a rite of passage; in others, it’s a last resort.The Verified Baseline
Public data confirms that homeownership remains the single largest asset for most Americans. The 2022 Federal Reserve data shows that median home equity (primary residence value minus debt) accounts for $280,000 of the $330,000 median net worth for households headed by someone aged 55–64. For those 65+, the figure jumps to $320,000 in equity against a $350,000 median net worth—meaning the home represents 91% of total assets. These aren’t outliers but the norm for retirees who’ve paid off mortgages. The pattern holds globally: in the UK, the primary residence as percentage of net worth for over-65s averages 70-80%, while in Canada, it’s 65% due to higher rental costs. The baseline also reveals generational divides. Millennials, despite higher student debt, enter homeownership with primary residence exposure starting around 30-40% of net worth—lower than previous generations at the same age. This reflects delayed entry into the market and higher down payment requirements post-2008. For Gen X, the ratio typically peaks in their late 50s at 60-70%, aligning with peak earning years and mortgage paydowns. The data underscores a critical truth: the primary residence as a percentage of net worth isn’t fixed—it’s a moving target shaped by debt, income growth, and market cycles.What the Estimates Suggest
Industry projections suggest that primary residence exposure will rise in the coming decade, driven by two forces: stagnant wage growth and persistent housing inflation. The National Association of Realtors estimates that by 2030, home equity as a share of net worth could climb to 85% for retirees in high-cost metros, assuming no major policy interventions. This would exacerbate the "wealth gap" between homeowners and renters, with the latter accumulating zero primary residence exposure and thus no collateral for loans or inheritance. Economists at Goldman Sachs have warned that such concentration could amplify systemic risks during recessions, as forced sales of primary residences depress local markets further. Regional estimates paint a varied picture. In Sun Belt cities like Phoenix or Austin, where homeownership rates are rising but prices remain below coastal levels, the primary residence as percentage of net worth is estimated at 55-65% for median-income buyers—lower than historical norms due to affordability. Conversely, in Boston or Seattle, figures around the 70-80% range have been suggested for similar demographics, reflecting both higher prices and slower wage growth. The estimates also highlight a demographic shift: younger homebuyers in expensive markets may never achieve the 50% primary residence exposure that defined their parents’ retirement planning, forcing a reevaluation of traditional wealth-building strategies.
Case Study: A Closer Look
Consider the decision of a couple in their early 60s with a $1.2 million primary residence in Los Angeles, carrying a $200,000 mortgage and $800,000 in other assets (retirement accounts, investments). Their primary residence as percentage of net worth stands at 60%—a figure that would seem stable until they factor in California’s 13.3% capital gains tax on primary sales. If they downsize to a $600,000 condo, they’d realize $600,000 in gains, owing $80,000 in taxes while freeing up $600,000 in liquidity. The trade-off? Their new home would represent 75% of their reduced net worth, leaving them vulnerable to another market dip. The dilemma isn’t unique: financial planners report that 60% of clients over 60 face similar calculations, where the primary residence exposure becomes a liability rather than an asset. The case exposes a flaw in conventional wisdom: that home equity is always "safe" wealth. In reality, the primary residence as a share of net worth can become a wealth trap. For this couple, the optimal path might involve partial liquidation—selling a secondary property or tapping home equity lines—rather than a full downsizing move. The decision hinges on three factors: tax efficiency, liquidity needs, and tolerance for market risk. A table of estimated impacts might look like this:| Factor | Estimated Impact |
|---|---|
| Downsizing to $600K | Reduces primary residence exposure from 60% to 75% of net worth; gains $600K after taxes but loses market upside. |
| Home Equity Line (HELOC) | Accesses $300K liquidity while keeping primary residence exposure at 60%; risk of higher interest rates or foreclosure if values drop. |
| Renting Out Primary | Generates $4,000/month rental income but increases primary residence exposure to 70% (due to debt servicing costs); taxed as ordinary income. |
"Clients assume their home is their safety net, but when it’s 60% of their net worth, it’s not a net—it’s a single point of failure. The math changes when you realize you can’t sell it and move to a cheaper state without triggering capital gains that wipe out your other assets."
What This Means Going Forward
The rising primary residence as percentage of net worth is reshaping retirement planning. Advisors are increasingly recommending diversification strategies that reduce home concentration before age 60, such as: - Accelerated mortgage paydowns to lower leverage. - Investing home equity proceeds in tax-advantaged accounts (e.g., IRAs) rather than reinvesting in real estate. - Geographic arbitrage: downsizing to lower-cost areas where the primary residence exposure remains manageable. The shift reflects a harsh reality: the primary residence as a share of net worth is no longer a passive metric but an active risk factor. For younger buyers, the solution may lie in delayed homeownership or co-ownership models (e.g., multi-generational homes) to spread exposure. For older homeowners, the focus is on partial liquidity—using reverse mortgages or sale-leasebacks to access capital without abandoning the home entirely. The common thread is a move away from treating the primary residence as a default wealth store toward treating it as one component of a balanced portfolio. Policy responses are lagging behind the trend. While some cities offer property tax relief for seniors, no federal framework addresses the primary residence concentration risk at scale. The closest analogy is the Financial Stability Oversight Council’s scrutiny of systemic risks in housing finance—but that’s focused on mortgages, not asset allocation. As the primary residence as percentage of net worth climbs, the gap between personal finance and macroeconomic stability will only widen, demanding either individual adaptation or systemic change.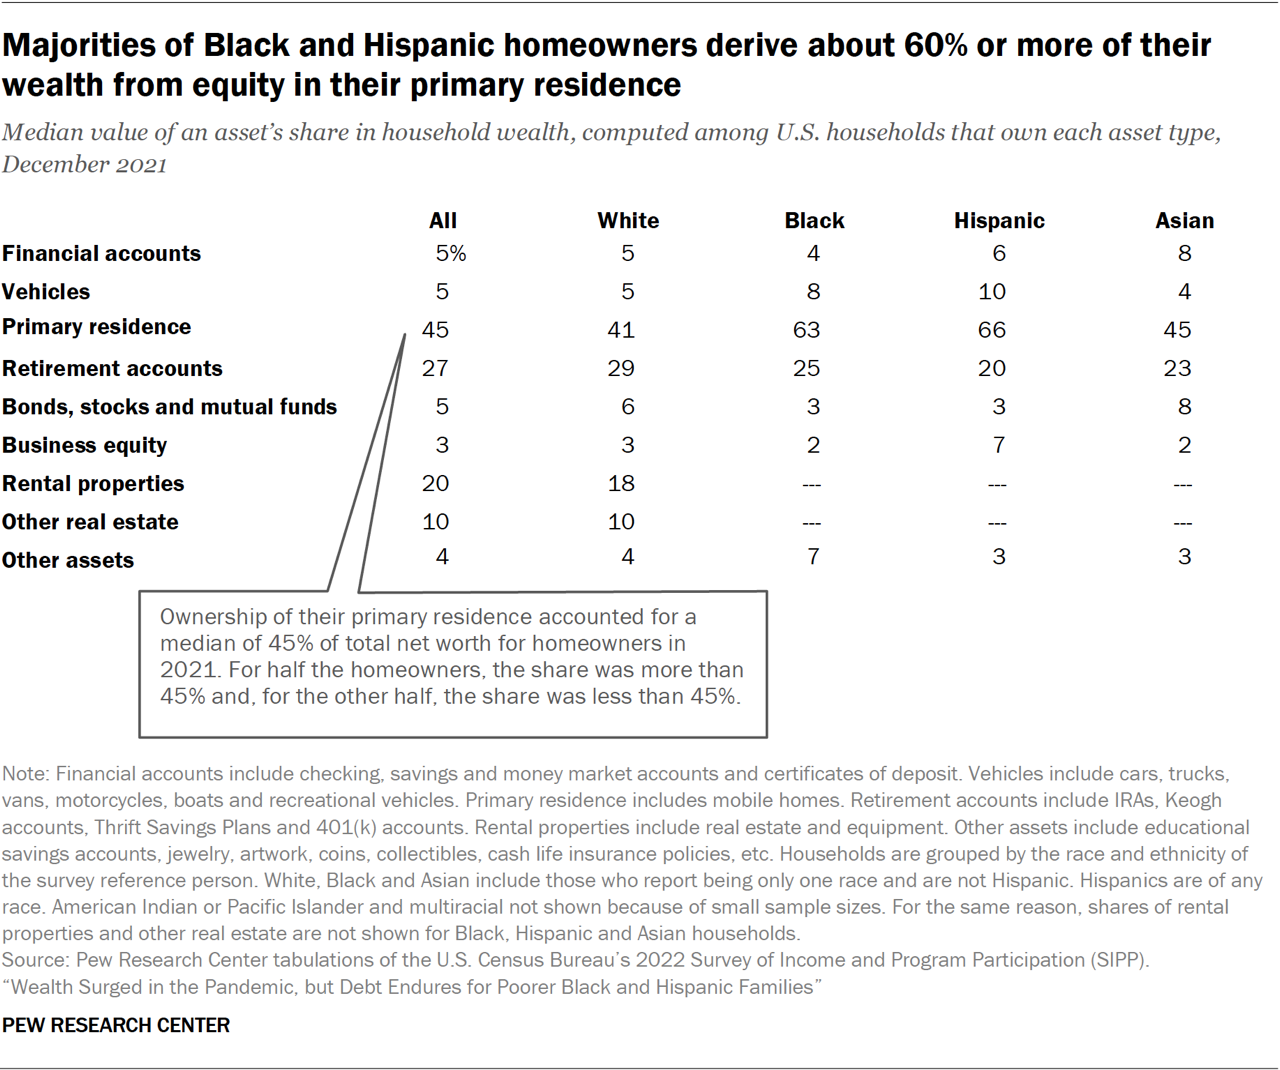
Conclusion
The primary residence as percentage of net worth is more than a household balance sheet line item—it’s a reflection of economic priorities, generational shifts, and unspoken fears about the future. The data shows that for many, the home isn’t just shelter but the cornerstone of wealth. Yet that same concentration creates fragility, exposing households to risks they can’t control. The solution isn’t to abandon homeownership but to rethink its role in a diversified life. The math is clear: when a primary residence dominates net worth, financial freedom becomes conditional. The question for individuals—and the systems that serve them—is whether to accept that trade-off or demand tools to rewrite the equation.Comprehensive FAQs
Q: At what percentage does my primary residence become a financial risk?
A: Financial advisors typically flag 50% or higher as a high-risk threshold, though the safe zone depends on your age, debt levels, and other assets. For retirees, 60%+ often signals vulnerability to market or health shocks, while younger homeowners may tolerate higher exposure if they have low debt and diversified income.
Q: How does a reverse mortgage affect my primary residence as a percentage of net worth?
A: A reverse mortgage converts home equity into liquidity but increases your primary residence exposure over time, as the loan balance grows. For example, tapping 50% of equity might reduce your net worth temporarily, but the home’s value as a share of total assets could rise if other investments underperform. The risk is that you’re left with an illiquid asset and no remaining equity to sell.
Q: Can downsizing reduce my primary residence exposure enough to matter?
A: Yes, but the math must account for capital gains taxes, transaction costs, and new mortgage terms. If you sell a $1M home for $900K after taxes and buy a $500K property, your primary residence as a percentage of net worth might drop from 70% to 60%—a meaningful shift. However, if you reinvest proceeds into another high-value home, the exposure could remain unchanged or even increase.
Q: Does renting instead of buying lower my primary residence exposure?
A: Absolutely—but it also means zero primary residence exposure, which eliminates home equity as a wealth anchor. Renters accumulate wealth through investments, savings, or business assets, but they lack the forced savings mechanism of a mortgage paydown. The trade-off is liquidity for stability; the choice depends on whether you prioritize flexibility or long-term asset growth.
Q: How do high home prices in cities like NYC or SF distort the primary residence as percentage of net worth?
A: In these markets, primary residence exposure often exceeds 80-90% for median-income earners because other asset classes (stocks, bonds) are priced out of reach. The distortion forces homeowners to rely on home equity for retirement, education, or emergencies—effectively turning their residence into a living ATM. The result? Lower mobility, higher risk tolerance, and a greater dependence on local market conditions.
Q: Are there tax strategies to reduce the impact of primary residence exposure?
A: Yes, but they require planning. Strategies include: - 1031 exchanges (for investment properties, not primary residences). - Installment sales to spread capital gains over time. - Charitable remainder trusts to donate appreciated value while retaining use of the home. - Primary residence capital gains exclusion ($250K single/$500K married) to defer taxes on downsizing. The key is to act before the home’s value as a share of net worth becomes unmanageable.
