Common Myths About Your Personal Net Worth
The first myth is that your personal net worth is a reliable indicator of success. It isn’t. A tech founder with a $50 million valuation on paper might have $5 million in liquid cash after paying salaries, legal fees, and equity stakes to early investors. Meanwhile, a dentist with no debt, a paid-off practice, and a modest retirement fund could have a net worth twice as high—yet never make a headline. The confusion stems from conflating market potential with realizable assets. What looks like wealth on a balance sheet often vanishes when you try to access it. The second myth is that your personal net worth is solely about assets. In reality, it’s a net calculation: assets minus liabilities, with liabilities including not just mortgages or loans but also opportunity costs. A stay-at-home parent’s net worth might appear lower on paper, but the unpaid labor of childcare—worth hundreds of thousands in lost earning potential—is rarely factored in. Even for high earners, intangible liabilities like legal exposure (for public figures) or the cost of maintaining a certain lifestyle (for the ultra-wealthy) can erode net worth faster than most realize. A third persistent myth is that your personal net worth is a fixed number. It’s not. For most people, it fluctuates wildly over time. A 2022 Federal Reserve study found that median net worth in the U.S. dropped by 12% for households under 35 between 2019 and 2021—thanks to inflation, job losses, and market downturns. Meanwhile, the top 1% saw their net worth grow by 18% in the same period, but not because of organic growth; asset concentration (stocks, real estate, private equity) and tax-efficient structures did the work. The number you see today may bear little resemblance to tomorrow’s.Myth 1: Higher net worth means financial freedom
The assumption that a seven-figure net worth equals financial independence is dangerous. A 2023 study by the Schwab Center for Financial Research found that only 38% of Americans with net worth between $1 million and $5 million could cover essential expenses for 30 years without touching principal. The rest were trapped by sequence-of-returns risk, high living costs, or illiquid assets. A Silicon Valley executive might have a net worth of $15 million on paper, but if 60% of it is tied up in restricted stock units (RSUs) with vesting schedules, they’re not free to spend it—or even access it—without penalties. The reality is that your personal net worth’s utility depends on liquidity, not just size. A farmer with $2 million in land might be asset-rich but cash-poor, while a freelancer with $500,000 in a high-yield savings account and no debt could retire tomorrow. The myth persists because wealth is often judged by headlines (e.g., "Tech CEO’s Net Worth Hits $1B") rather than by the cold math of living expenses versus sustainable withdrawals.Myth 2: Debt always drags down your net worth
Not all debt is created equal. A mortgage on a primary residence, for example, can increase your net worth over time—assuming home values rise and you stay in the property long enough. The Federal Reserve’s Report on the Economic Well-Being of U.S. Households (2023) noted that homeowners with mortgages had 30% higher median net worth than those without, thanks to forced savings via amortization and equity buildup. Meanwhile, student loans—often lumped into the "bad debt" category—can be an investment if they lead to higher-earning careers, even if the net worth impact isn’t immediate. The confusion arises from treating all debt as a liability. In truth, your personal net worth’s relationship with debt hinges on interest rates, asset appreciation, and personal cash flow. A business owner with a $1 million line of credit might see their net worth grow if the business generates $1.5 million in revenue annually, while a consumer with $50,000 in credit card debt at 20% APR is hemorrhaging wealth. The key isn’t avoiding debt entirely; it’s ensuring the debt serves as a leverage tool, not a drag.Myth 3: Your personal net worth is private
For most people, it is—but for the wealthy and public figures, it’s a carefully curated narrative. Take Elon Musk, whose net worth fluctuated between $180 billion and $200 billion in 2023 depending on Tesla’s stock price and whether he was selling shares. Yet his realizable wealth—the amount he could access without triggering market sell-offs—was likely far lower. Forbes and Bloomberg’s estimates rely on public filings, but private transactions (e.g., off-market stock sales, family trusts) are often omitted. Even for private individuals, social media bragging or leaked tax documents can turn personal net worth into a public spectacle, distorting perceptions of both the wealthy and the aspirational. The illusion of privacy is further shattered by wealth tracking tools like Wealth-X or Credit Suisse’s Global Wealth Report, which aggregate data from tax records, property registries, and luxury purchases. For the average person, privacy is still possible—but for those with assets above $30 million, anonymity is a myth. The result? A feedback loop where perceived net worth (what the public assumes) diverges sharply from actual net worth (what the balance sheet shows).
What Holds Up to Scrutiny
At its core, your personal net worth is a three-legged stool: assets you own, liabilities you owe, and the time horizon over which you can convert assets into cash. The first two are straightforward—though valuing assets like art, collectibles, or private business stakes requires expertise. The third is often overlooked. A 2021 study in the Journal of Financial Planning found that only 18% of high-net-worth individuals had a clear exit strategy for illiquid assets, meaning their net worth was more theoretical than real. What’s verifiable? The median net worth by age group in the U.S.: - Under 35: ~$50,000 - 35–44: ~$180,000 - 45–54: ~$300,000 - 55–64: ~$450,000 - 65+: ~$420,000 These figures come from the Federal Reserve’s Survey of Consumer Finances and reflect realizable wealth, not paper valuations. The data also show that homeownership is the single biggest driver of net worth growth for the middle class, while for the top 1%, business ownership and financial assets dominate."Net worth is a snapshot, not a movie. The real question isn’t ‘How much do I have?’ but ‘How much can I access, and when?’" — Carl Richards, financial planner and author of The Behavior Gap
| Common Belief | What the Evidence Says |
|---|---|
| Real estate always appreciates. | Only 60% of U.S. counties saw home price growth between 2010–2020; rural and distressed markets often stagnate. |
| Stocks are the safest long-term asset. | Since 1926, the S&P 500 has lost value in 23 separate years, including 2008 (-37%) and 2022 (-19%). |
| High net worth = low stress. | Wealthier individuals report higher stress levels due to complexity of tax, estate, and investment management (2023 American Psychological Association study). |
| Debt is always bad. | Mortgage debt held by homeowners correlates with higher net worth over 10+ years (Fed data). |
| Your net worth doubles every decade. | Only true for the top 10% of earners; median net worth growth has averaged 1–3% annually since 2000. |
Why the Confusion Persists
The gap between perception and reality is widening because wealth is no longer just a financial metric—it’s a cultural one. Social media platforms like Instagram and TikTok glorify lifestyle inflation (e.g., "I spent $20K on a vacation—here’s my net worth!"), while financial influencers peddle over-simplified rules (e.g., "50/30/20 budget = wealth"). Meanwhile, traditional media focuses on outlier stories—the overnight millionaire, the trust-fund baby—rather than the slow, steady accumulation that defines most people’s net worth trajectories. There’s also the halo effect of titles. A CEO might have a net worth of $5 million, but if they’re paying $500,000/year in school tuition for their kids, their effective net worth is far lower. The confusion extends to tax strategies: offshore accounts, dynasty trusts, and charitable remainder trusts can legally reduce taxable net worth without increasing liquidity. The result? A system where what you see isn’t what you get, and the numbers are only as reliable as the people reporting them.
Conclusion
Your personal net worth is less about the number and more about what it can do for you. A $1 million net worth in a high-cost city like San Francisco might buy you a modest home and a modest lifestyle; the same $1 million in rural Mississippi could set you up for life. The key isn’t chasing a target figure but aligning your assets with your goals—whether that’s early retirement, legacy building, or simply avoiding financial stress. The biggest mistake people make isn’t tracking their net worth; it’s treating it as a destination rather than a tool. A farmer’s net worth might look modest on paper, but if it funds food security for their community, it’s serving a purpose. A freelancer’s net worth might fluctuate monthly, but if it funds their creative work, it’s sustainable. The obsession with absolute numbers distracts from the real question: Is your net worth working for you, or are you working for it?Comprehensive FAQs
Q: How often should I update my net worth?
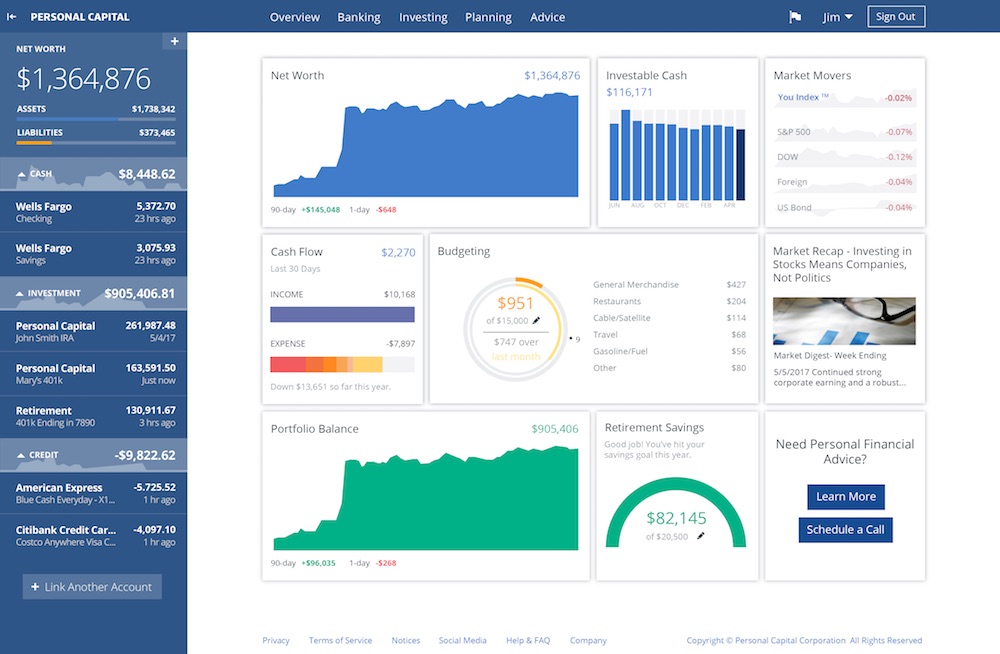
A: Quarterly is ideal for most people, but annually is sufficient if your assets and debts change slowly. High-net-worth individuals (net worth >$5M) should track monthly due to volatility in investments, real estate, and taxable events. Use a simple spreadsheet or tools like Personal Capital to automate tracking—just remember to adjust for fair market value (not purchase price) of assets like homes or stocks.
Q: Does my spouse’s or partner’s debt affect my net worth?
A: Only if it’s joint debt. Separate debts (e.g., a spouse’s credit card) don’t impact your net worth calculation unless you’re legally responsible. However, if you’re planning to combine finances (e.g., for a mortgage or retirement), their liabilities will factor into your joint net worth. For unmarried couples, it’s critical to clarify ownership of assets and liabilities to avoid surprises.
Q: Can my net worth be negative?
A: Yes—especially for young adults, students, or entrepreneurs in early-stage businesses. A negative net worth simply means your liabilities exceed your assets. This isn’t inherently bad; many successful people (e.g., Steve Jobs in the early Apple days) operated with negative net worth for years. The risk comes when high-interest debt (credit cards, payday loans) spirals out of control. If your negative net worth is driven by strategic leverage (e.g., a mortgage on appreciating real estate), it may be a temporary phase.
Q: How do I account for assets like a side hustle or freelance income?
A: Treat side hustles as future assets if they generate recurring revenue. For example: - Liquid assets: Add the value of a business bank account or prepaid client invoices. - Illiquid assets: If you own a business, estimate its fair market value (e.g., 3–5x annual profit for small businesses). - Skills-based income: Don’t count future earnings as an asset, but track retainer agreements or long-term contracts as deferred revenue. The key is conservatism: Overestimating the value of a side hustle can lead to false confidence in your net worth.
Q: What’s the difference between gross worth and net worth?
A: Gross worth is the total value of all your assets (home, investments, business equity, etc.) without subtracting liabilities. Net worth subtracts debts (mortgages, loans, credit cards) to show your true financial position. For example: - Gross worth: $1.2M (home) + $300K (401k) + $50K (car) = $1.55M - Net worth: $1.55M – $800K (mortgage) – $20K (car loan) = $730K Most financial planning focuses on net worth because it reflects what you could realistically access in an emergency.
Q: Should I include my pension or retirement accounts in my net worth?
A: Yes, but with caveats. - 401(k)/IRA: Include the full balance if it’s invested in liquid assets (stocks, bonds). If it’s in annuities or employer stock, adjust for liquidity risk. - Pension: Include the present value (what it’s worth today if cashed out), not the future payout. Many pensions are backloaded, meaning early withdrawals reduce benefits. - Roth accounts: Include the full value, as withdrawals are tax-free. Warning: If you’re nearing retirement, treat these as illiquid assets—accessing them early may trigger penalties or reduce future income.
Q: How does inflation affect my net worth over time?
A: Inflation erodes the purchasing power of your net worth even if the dollar amount grows. For example: - If your net worth grows from $500K to $600K in 5 years but inflation is 3% annually, your real net worth (adjusted for inflation) is closer to $540K. - Asset classes behave differently: Cash and bonds lose value in inflation; real estate and equities often outpace it long-term. - Strategy: Allocate a portion of your net worth to inflation-resistant assets (TIPS, real estate, commodities) to preserve spending power.
Q: Can I hide assets to protect my net worth?
A: Legally, yes—but ethically and strategically, no. Common (but often risky) tactics include: - Offshore accounts: Legal in many cases, but the Foreign Account Tax Compliance Act (FATCA) requires disclosure if balances exceed $10K. - Trusts: Can protect assets from lawsuits or creditors, but self-settled trusts (e.g., for your own benefit) may be challenged. - LLCs or corporations: Used by business owners to shield personal assets, but piercing the corporate veil is possible if courts find personal and business finances commingled. Reality check: Hiding assets from taxes or creditors is illegal. The better approach is legal protection (e.g., asset protection trusts in states like Nevada or Delaware) and diversification to reduce exposure.
Q: What’s the most common mistake people make when calculating net worth?
A: Overvaluing assets and undervaluing liabilities. People often: - Use purchase price (not current market value) for their home or car. - Ignore future liabilities (e.g., college tuition for kids, upcoming medical bills). - Forget opportunity costs (e.g., the net worth impact of quitting a job to start a business). - Exclude intangible assets (e.g., a professional license, a loyal client base) that have real value but no market price. Fix: Use a conservative valuation—if you’re unsure of an asset’s worth, assume it’s worth 70–80% of what you’d sell it for today.
