
Breaking Down the Numbers
The Federal Reserve’s Survey of Consumer Finances remains the gold standard for net worth percentile by age analysis, but its latest 2022 data (the most recent full snapshot) is already two years out of date. Even so, the trends are clear: wealth accumulation is no longer linear. A 25-year-old in the 90th percentile today may have a net worth of $180,000—mostly from inherited assets or early-career tech equity—but that same percentile at 55 could drop to $1.2 million, while their peer in the 50th percentile at 25 might have $15,000 and end up with $350,000 by retirement. The divergence isn’t just about effort; it’s about structural advantages. Someone born in 1980 had a 30-year head start on homeownership and defined-benefit pensions. Their 2024 counterpart faces a rental market where 30% of income goes to housing, and a 401(k) that’s now their sole retirement vehicle. The net worth percentile by age conversation often ignores the elephant in the room: liquidity. A homeowner in their 50s might have a $500,000 net worth on paper, but if their mortgage is $300,000 and they’ve tapped home equity for college or medical bills, their usable wealth is a fraction of that. Meanwhile, a renter in the same age bracket with $200,000 in cash and investments could be in a higher percentile for financial flexibility. The Fed’s data doesn’t distinguish between "illiquid wealth" (a paid-off house) and "flexible wealth" (stocks, savings, or a side business). That’s why a 60-year-old couple in Florida with a $1.5 million home might be in the 85th percentile, while a tech worker in Austin with $1.2 million in crypto and no debt could be in the 95th—even though their total assets are lower.The Verified Baseline
What’s verifiable in 2024? The net worth percentile by age benchmarks from the Fed’s 2022 report, adjusted for inflation, show these rough ranges: - Age 35: Median net worth sits at $92,000 (50th percentile). The 75th percentile jumps to $250,000, while the 90th percentile is $500,000+, often tied to professional licenses, inherited capital, or early real estate investments. - Age 45: The median climbs to $165,000, but the 75th percentile is now $450,000, reflecting peak earning years and homeownership. The top 10% here often have $1 million+, thanks to stock options, business ownership, or family wealth transfers. - Age 55: The median is $250,000, but the 90th percentile reaches $1.5 million. This is where the "wealth gap by education" becomes stark: someone with a graduate degree and a white-collar job will outpace their high school-educated peer by 3x to 5x in net worth. The data also confirms what behavioral economists have long suspected: net worth percentile by age growth plateaus after 60. The 75th percentile at 65 is $1 million, but the 90th percentile is $2.5 million+, and the gap between these tiers widens because the ultra-wealthy (those in the top 1%) are no longer just relying on salaries—they’re deploying wealth in private equity, real estate syndications, or family offices.What the Estimates Suggest
Where the Fed’s data ends, industry estimates begin—and here, the picture gets murkier. According to net worth percentile by age projections from wealth managers like Schwab and Fidelity, adjusted for 2024’s market conditions, the following ranges are often cited (with heavy caveats): - Under 30: The median is estimated at $50,000, but the 75th percentile is $150,000, largely due to student debt write-offs or parental financial gifts. The 90th percentile? $300,000+, often from tech equity, freelance gigs, or early real estate flips. - 30–40: The median jumps to $120,000, but the 75th percentile is $350,000, reflecting peak earning power and homeownership. The top decile here is $800,000+, with many in this group having multiple income streams (rental properties, side businesses, or passive investments). - 40–50: The median is $200,000, but the 90th percentile is $1.2 million, thanks to defined-contribution plans (like 401(k)s) and tax-advantaged accounts. The ultra-wealthy in this bracket often have $3 million+, with significant holdings in illiquid assets like private companies or collectibles. The biggest variable? Geography. A 40-year-old in New York might be in the 60th percentile with $250,000, while their identical-earning counterpart in Omaha could be in the 85th percentile with the same figure—because the cost of living and local tax burdens eat into net worth differently. The net worth percentile by age calculations also assume average risk tolerance, but in reality, someone who’s aggressively invested in crypto or startup equity could swing from the 50th to the 99th percentile—or vice versa—in a single year.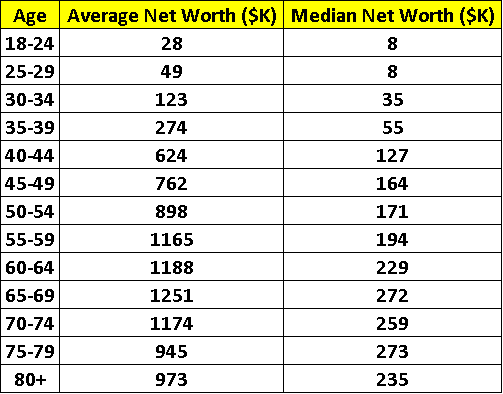
Case Study: A Closer Look
Take the example of two 38-year-olds in 2024: Alex, a software engineer in Seattle, and Jamal, a high school teacher in Indianapolis. Both earn $120,000 annually, but their net worth percentile by age could differ by 40 percentage points. Alex’s $850,000 net worth (75th percentile) comes from a mix of stock options, a paid-off condo, and a side hustle in AI consulting. Jamal’s $350,000 (40th percentile) includes a mortgage, a modest 401(k), and a car loan. The difference isn’t just salary—it’s compounding leverage. Alex’s early investments in tech startups (even failed ones) gave them a 10-year head start on wealth accumulation, while Jamal’s student loans and lower local home values kept their assets liquid but less scalable. What separates them isn’t raw talent or hours worked—it’s asymmetric opportunities. Alex’s employer offers RSUs (restricted stock units), which vest over time and have appreciated 5x since issuance. Jamal’s district offers a pension, but its projected value is 20% lower than promised due to underfunding. The net worth percentile by age gap here isn’t a moral failing; it’s a product of institutional design."Wealth isn’t just about what you earn—it’s about what you own, what you can liquidate, and what the system lets you keep." — Dr. Meirav Furst-Nichols, economist at the Urban Institute
| Factor | Estimated Impact on Net Worth Percentile |
|---|---|
| Early-career stock options/RSUs | Can boost a 30-year-old from the 60th to the 85th percentile within 5 years if vested assets appreciate. |
| Student loan debt (average $30K balance) | Drops a 35-year-old’s percentile by 10–15 points due to reduced liquidity for investments. |
| Homeownership vs. renting | Owning a home in a high-appreciation market (e.g., Austin, Miami) adds 20+ percentile points by age 45 vs. renting. |
| Side income (freelance, gig work) | Can shift a 40-year-old from the 50th to the 70th percentile if reinvested, but carries tax and volatility risks. |
| Inheritance or family gifts | Accounts for 30% of wealth in the top decile by age 50, often pushing recipients from the 75th to the 95th percentile. |
What This Means Going Forward
The net worth percentile by age metrics are less about judgment and more about strategic awareness. If you’re in the 50th percentile at 35, the goal shouldn’t be to "catch up" to the 75th percentile—it should be to understand the levers that move you there. For most people, that means asset allocation flexibility: Can you shift from a 401(k) to a self-directed IRA? Can you leverage home equity without triggering capital gains? The ultra-wealthy don’t just earn more—they optimize their tax drag, liquidity, and risk exposure in ways that keep them in higher percentiles even during downturns. The other reality? Percentiles are a lagging indicator. By the time you hit the 75th percentile, the benchmark may have shifted. The key is to focus on wealth velocity—how fast your net worth grows relative to your peers. A 28-year-old in the 60th percentile with a 15% annualized growth rate in investable assets will outpace someone in the 70th percentile with stagnant wealth. The net worth percentile by age conversation is useful, but the real question is: What’s your trajectory, and what’s holding it back?
Conclusion
The data on net worth percentile by age in 2024 tells us two things: 1) The system is rigged—not in a conspiracy-theory sense, but in a structural one, where timing, location, and family background matter more than grit alone. 2) The percentiles themselves are less important than what they reveal about your financial ecosystem. A 45-year-old with $500,000 in net worth might be in the 75th percentile, but if their monthly expenses are $10,000 (thanks to a mortgage, private school tuition, and a second home), they’re functionally in the 40th percentile for financial freedom. The takeaway? Stop comparing yourself to the median. Instead, ask: What’s the highest percentile I can realistically reach given my constraints? Then work backward. The net worth percentile by age isn’t a finish line—it’s a checkpoint. Ignore it at your peril, but don’t let it dictate your strategy.Comprehensive FAQs
Q: How does student loan debt affect my net worth percentile by age?
Student loans suppress liquidity, which drags down your net worth percentile by age because they reduce your investable assets. For example, a 30-year-old with $40,000 in student debt and $80,000 in net worth might sit in the 45th percentile, while an identical-earning peer with no debt and the same net worth could be in the 60th. The impact varies by income—high earners recover faster, but for those in the bottom 40% of percentiles, debt can delay homeownership or retirement savings by a decade.
Q: Can I move up two percentiles (e.g., from 50th to 70th) in five years?
Yes, but it requires asymmetric effort. For a 35-year-old, this might mean: - Increasing investable income by 20% (side hustle, career switch). - Reducing fixed expenses by 15% (refinancing debt, downsizing housing). - Allocating 30% of savings to high-growth assets (stocks, real estate, or a business). The net worth percentile by age jump isn’t linear—it’s exponential when you combine leverage (e.g., a mortgage paid off early) with compounding (e.g., tax-advantaged accounts). However, market downturns or unexpected costs (medical, caregiving) can reset progress.
Q: Does homeownership always boost my net worth percentile by age?
Not necessarily. A home improves your net worth percentile by age only if: - It appreciates faster than your mortgage balance grows. - You avoid tapping equity for non-essential expenses (e.g., college, vacations). - Your local market isn’t in a bubble (e.g., Miami in 2024 vs. Detroit in 2010). For those in the bottom 50% of percentiles, a home can be a wealth anchor—the equity gets locked in while other assets (stocks, cash) grow. Renters in high-opportunity areas (e.g., Austin, Nashville) often outpace homeowners in stagnant markets (e.g., Cleveland, Pittsburgh) because their cash flow is higher.
Q: How does divorce impact net worth percentile by age?
Divorce can halve your net worth percentile by age overnight, depending on asset division. For example: - A 45-year-old in the 80th percentile with $1.2 million in joint assets might drop to the 50th percentile ($400,000) post-split. - If one spouse keeps the home and the other takes liquid assets, the percentile gap widens because illiquid wealth (a house) doesn’t translate to spending power. - Alimony or child support can temporarily offset the drop, but long-term, it reduces investable income. The net worth percentile by age recovery time varies—some rebound in 3–5 years with a new career or side income, while others stay in the bottom 30% for decades.
Q: Are there industries where the net worth percentile by age grows faster?
Yes. Fields with high earning potential, equity upside, or asset control accelerate percentile growth: - Tech (engineering, product management): Early stock options can push a 30-year-old from the 60th to the 90th percentile in 5 years. - Healthcare (specialists, executives): Low volatility in income + high demand = steady percentile climbs. - Real estate (developers, property managers): Leverage (mortgages) amplifies net worth growth, but illiquidity risks can stall progress. - Finance (private equity, hedge funds): Top earners see net worth percentile by age jumps of 20+ points per decade, but the bottom 60% in these fields often underperform due to high overhead costs.
Q: How does inflation affect my net worth percentile by age?
Inflation erodes nominal net worth but doesn’t always drag percentiles down because: - Asset classes (stocks, real estate) often outpace inflation, preserving percentile rank. - Debt (mortgages, student loans) becomes cheaper over time, improving liquidity. - Wages don’t keep up, so those in the top 20% of percentiles see their real wealth grow faster than peers. For example, a 50-year-old in the 75th percentile in 2010 ($800,000 net worth) might be in the 65th percentile today ($1.2 million) if inflation was 4% annually—but if their assets (stocks, business ownership) grew at 7%, they’d still be in the 80th percentile. The net worth percentile by age resilience depends on asset mix.
Q: What’s the biggest mistake people make when tracking net worth percentile by age?
Assuming percentiles are static benchmarks. The biggest error is: - Chasing the median: Aiming for "average" wealth without accounting for liquidity, risk tolerance, or personal goals. - Ignoring illiquid assets: A $1M home might put you in the 85th percentile, but if it’s your only asset and you need cash flow, you’re functionally in the 50th percentile. - Over-indexing on salary: Two people with the same income can have net worth percentiles 30 points apart due to debt, geography, or investment choices. The fix? Track not just net worth, but net worth velocity—how fast it’s growing relative to your peers—and adjust strategies (taxes, spending, asset allocation) accordingly.
