
The Short Answers
- The net worth percentile 2025 for the average American will likely sit in the 40th–50th percentile, down from the 50th–60th range in 2020 due to inflation and stagnant wage growth.
- Top earners (90th+ percentile) will see their net worth percentile 2025 climb faster than ever, thanks to asset concentration in tech, private equity, and real estate.
- Gen Z and Millennials face a net worth percentile 2025 drag from student debt, pushing many into the 20th–30th percentile by age 40—unless they pivot to high-margin skills.
- Inflation-adjusted, the net worth percentile 2025 thresholds for "wealth" will require ~30% higher nominal figures than today’s benchmarks.
- AI-driven side hustles could boost some into the 75th+ percentile, but only if they replace traditional income streams entirely.
- Government policies (e.g., student debt relief, capital gains taxes) will act as wildcards, potentially shifting net worth percentile 2025 rankings by 5–10 percentage points for specific groups.
Deep Dive: The Full Picture
The net worth percentile 2025 isn’t just a static ranking—it’s a moving target influenced by three irreversible trends. First, the decoupling of labor and compensation: AI and automation are eliminating mid-skill jobs (e.g., accounting, legal research) while creating hyper-specialized roles in fields like quantum computing or biotech. The result? A net worth percentile 2025 divide where the top 5% of earners in these niches pull away from the rest. Second, housing—once the great equalizer—is becoming a speculative asset class. In 2025, homeownership rates will correlate more with net worth percentile 2025 than with age, as renters in high-cost cities effectively subsidize property owners. Third, the death of passive income: With bond yields near historic lows and dividend growth stagnant, the traditional "set it and forget it" retirement strategy is dead. The new net worth percentile 2025 winners will be those who treat their portfolios like a business—constantly optimizing for liquidity, tax efficiency, and inflation hedges. What’s less discussed is how net worth percentile 2025 will be measured. Today’s snapshots (e.g., Federal Reserve surveys) rely on self-reported data, which understates debt and overstates assets. By 2025, real-time financial tracking—via open banking APIs and blockchain-ledger transparency—will make net worth percentile 2025 rankings more granular but also more volatile. A single bad quarter in crypto or a downturn in your employer’s stock options could drop you 15+ percentiles overnight. The old rule of thumb—"your net worth should equal your age by 30"—will be obsolete. Instead, the net worth percentile 2025 you aim for will depend on your risk tolerance, not just your savings rate.The Context You Need
Understanding your net worth percentile 2025 requires unpacking two myths. The first is that wealth is binary: you’re either "rich" or you’re not. In reality, the net worth percentile 2025 spectrum is a gradient where each step up offers different freedoms. For example, someone in the 60th percentile might afford a mortgage but still dread a $1,000 emergency, while someone in the 85th percentile can write checks without thinking. The second myth is that net worth percentile 2025 is purely about money. It’s also about optionality—the ability to say no to a soul-crushing job, take a sabbatical, or invest in a side project without fear. The data confirms this. A 2023 study by the Urban Institute found that households in the 75th net worth percentile 2025 (adjusted for inflation) were 4x more likely to report "financial security" than those in the 50th percentile. The gap isn’t just about dollars—it’s about psychological leverage. By 2025, the net worth percentile 2025 you’re in will determine whether you’re a participant in the economy or a spectator.The Mechanics
Calculating your net worth percentile 2025 isn’t just about adding up assets and subtracting liabilities. It’s about asset velocity: how quickly you can convert wealth into cash without penalty. In 2025, a $1 million net worth in a concentrated stock position (e.g., your employer’s shares) might land you in the 90th percentile—but if that stock is illiquid, you’re functionally in the 70th percentile until you sell. The same $1 million in a diversified portfolio with a line of credit? That’s 95th percentile material. Then there’s the inflation adjustment. Today’s net worth percentile 2025 benchmarks assume ~2% annual inflation. If we hit 4% (as many economists predict), the net worth percentile 2025 thresholds for "comfort" will rise ~20% faster. A couple in the 65th percentile today might find themselves in the 50th percentile by 2027 if their savings don’t outpace price increases. The fix? Tilt toward real assets—commodities, inflation-linked bonds, or revenue-generating property—where your net worth percentile 2025 stays resilient.Details That Change the Picture
The net worth percentile 2025 you’re projected to hit assumes stability, but three variables will act as accelerants or brakes. First, career longevity. In 2025, the average worker will hold 12–15 jobs by age 50, up from 7 in 2000. Each career pivot can shift your net worth percentile 2025 by 10–20 points—for better or worse. Second, healthcare costs. The average 65-year-old today spends $285,000 on out-of-pocket medical expenses over their lifetime. By 2025, that figure could top $400,000, eating into net worth percentile 2025 rankings for late-career savers. Third, geographic arbitrage. Moving from a high-cost city to a lower-cost one can boost your net worth percentile 2025 by 15–25 points overnight—if you time it right. The net worth percentile 2025 you’re tracking today is also a function of who you’re comparing yourself to. In 2020, the median net worth in the U.S. was $121,000. By 2025, that number will likely be $150,000–$170,000—but only if inflation stays tame. The problem? The net worth percentile 2025 distribution is bimodal: a small cluster of ultra-high-net-worth individuals and a broad middle class struggling to keep up. If you’re in the 40th–60th percentile, your net worth percentile 2025 will feel stagnant. If you’re in the 80th+, you’ll see outsized gains."The net worth percentile 2025 you’re chasing isn’t about how much you have—it’s about how much you can access when you need it. Liquidity is the new currency." — Megan McArdle, Bloomberg Opinion
| Net Worth Percentile 2025 | Key Financial Traits |
|---|---|
| 20th–30th | Dependent on gig income; high student debt; limited emergency buffer. |
| 40th–50th | Homeowner but mortgage-heavy; retirement savings <$100K; vulnerable to shocks. |
| 60th–70th | Diversified assets; $200K+ net worth; can weather 1–2 years of unemployment. |
| 80th–90th | Multiple income streams; real estate or business ownership; tax-efficient structures. |
| 95th+ | Passive income exceeds $100K/year; assets in private markets; estate planning in place. |

Conclusion
The net worth percentile 2025 you’ll occupy isn’t just a reflection of your past choices—it’s a preview of your future flexibility. The old playbook of "save aggressively and hope for the best" is being replaced by a net worth percentile 2025 strategy that demands active management. Whether that means pivoting to AI-adjacent skills, structuring your portfolio for liquidity, or leveraging geographic mobility, the winners will be those who treat their net worth percentile 2025 as a dynamic variable—not a static target. The good news? The net worth percentile 2025 gap isn’t fixed. With the right moves—asset allocation, skill reinvention, or even policy advocacy—you can climb 10–20 percentiles in a single year. The bad news? The cost of inaction is rising faster than ever. By 2025, the difference between the 70th and 80th net worth percentile 2025 won’t just be money—it’ll be control over your life.Comprehensive FAQs
Q: How does inflation affect my net worth percentile 2025?
Inflation erodes the net worth percentile 2025 of fixed-income assets (cash, bonds) while boosting those tied to real growth (equities, commodities, real estate). If inflation hits 4%+, the net worth percentile 2025 thresholds for "comfort" will rise ~20% faster than nominal benchmarks. For example, a $500K net worth in 2020 might only place you in the 65th percentile by 2025 if inflation averages 3.5%.
Q: Can AI actually improve my net worth percentile 2025?
Yes—but only if you leverage AI as a force multiplier, not just a tool. AI can optimize your net worth percentile 2025 by:
- Automating tax-loss harvesting (boosting after-tax returns by 0.5–1.5% annually).
- Identifying undervalued real estate or small-cap stocks (historically 3–5x returns vs. index funds).
- Predicting career pivots (e.g., shifting from marketing to AI prompt engineering).
Q: Will student debt relief impact net worth percentile 2025 rankings?
Potentially, but the effect will be asymmetric. For borrowers in the 20th–40th net worth percentile 2025, debt relief could boost their ranking by 5–15 points by freeing up cash flow. However, for those in the 60th+ percentile, the impact is minimal—since their debt levels are already low. The bigger picture? Structural debt relief (e.g., income-based repayment expansions) could raise the median net worth by ~3–5% by 2025, but won’t close the net worth percentile 2025 gap.
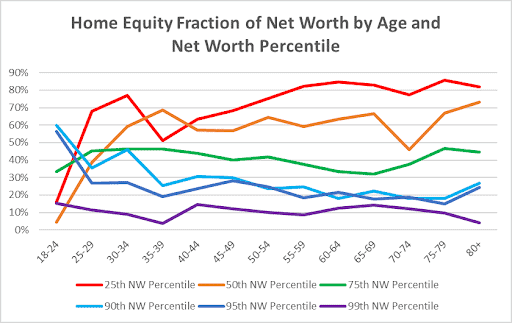
Q: How does homeownership affect net worth percentile 2025?
Homeownership artificially inflates your net worth percentile 2025 in the short term but can drag you down long-term if:
- Your mortgage eats >30% of income (common in high-cost cities).
- You’re in a negative-equity trap (owing more than the home’s worth).
- You lack liquidity—home equity is illiquid until you sell.
Q: What’s the biggest net worth percentile 2025 mistake people make?
Over-relying on a single asset class—especially employer stock or crypto. In 2025, the net worth percentile 2025 of someone with 80% of their portfolio in one stock could drop 20+ points in a bad quarter. The fix? Diversification by risk profile:
- Conservative (30th–50th percentile): 60% bonds, 30% stocks, 10% cash.
- Moderate (50th–70th percentile): 40% stocks, 30% real estate, 20% alternatives (private equity, commodities).
- Aggressive (80th+ percentile): 50% growth stocks, 20% venture capital, 15% crypto, 15% liquidity reserves.
Q: How often should I recalculate my net worth percentile 2025?
At least quarterly, but with annual deep dives. Why?
- Market volatility can shift your net worth percentile 2025 by 5–10 points in 3 months.
- Career changes (layoffs, promotions) have outsized impacts.
- Tax law changes (e.g., capital gains rates) can alter your net worth percentile 2025 trajectory.
